

How does the cash buyer determine the offer price for your property?
A cash buyer usually determines the offer by assessing your property’s location, size, condition, title position and likely market value, using comparable local sales as a guide. The calculation may also account for required repairs, purchase costs, resale prospects and the risks or complexity of the transaction.
The offer price is normally calculated by starting with an evidence-based estimate of the property’s achievable value and then adjusting it for the buyer’s total costs, required work, financing or holding exposure, and the return needed to make the purchase commercially viable. A cash offer is therefore not automatically the same as the price an owner might achieve through an estate-agent sale.
A professional valuation process usually involves several stages:
- Initial information review: The buyer considers the address, property type, approximate floor area, tenure, number of rooms, occupancy and any information supplied by the owner. Details should be accurate because a valuation based on incomplete information may be revised later.
- Evidence gathering: Recent sales of genuinely comparable properties provide a reference point. The most useful comparisons are similar in type, size, specification and setting, rather than simply properties within the same broad area. Asking prices can provide context, but completed sale prices are stronger evidence of what buyers have actually paid.
- Property verification: The buyer may arrange a viewing, inspection or independent survey to check whether the description matches the property’s actual state. Issues such as structural movement, damp, outdated services, defective roofing, poor access or non-standard construction can affect the calculation because they may create uncertainty or additional expenditure.
- Legal and planning checks: Searches and title information can reveal matters that influence value or the practicality of resale. Examples include restrictive covenants, rights of way, lease conditions, missing permissions, boundary disputes, short lease terms or unresolved ownership issues. These matters do not always prevent a sale, but they may affect the offer or require a solution before completion.
Once the underlying value has been assessed, the buyer models the expected cost of acquiring and reselling the property. This can include legal fees, survey and search charges, taxes, clearance, refurbishment, insurance, utilities, management, marketing and resale costs. Where the buyer expects to undertake substantial works, the estimate may include contractor quotations or a contingency for unforeseen defects. The offer reflects the total project rather than only the building’s apparent value on the day of inspection.
The buyer may also consider how readily the property could be resold. A property with unusual features, a restricted buyer pool, complicated access or uncertain documentation may require a larger allowance for risk than a straightforward home. This is not necessarily a judgement on the owner or the property; it reflects the possibility that the eventual sale could take longer, cost more or produce a different result than forecast.
Tenure can be particularly important. For a leasehold property, the remaining lease term, service-charge position, ground-rent provisions, major-works exposure and management information may all affect the calculation. For a property subject to probate, separation or another legal process, the buyer may also need to establish who has authority to sell and whether all necessary parties agree to the transaction.
The proposed payment structure should be read carefully. Ask whether the figure is the purchase price before deductions, whether the buyer expects any contribution towards specific costs, and whether the offer is conditional on survey, searches, title review or other checks. A headline figure is easier to compare when each buyer is using the same assumptions.
It is reasonable to request an explanation of the valuation, including the comparable sales used, the assumptions about works and the deductions included in the calculation. You can also obtain an independent valuation or ask a local estate agent for a market appraisal. These sources may produce different figures because an open-market appraisal estimates a potential marketing outcome, while a cash buyer is pricing a direct purchase with its own costs and risks.
An offer should remain subject to proper verification. If an initial figure changes after inspection or legal checks, the buyer should explain which new fact caused the revision. Significant unexplained reductions, pressure to accept immediately, or requests for upfront fees should be treated cautiously. Comparing the net amount you would receive, the conditions attached and the certainty of the proposed transaction gives a more useful assessment than comparing headline offers alone.
For a UK homeowner considering a cash sale, the most reliable approach is to provide complete property and legal information, check the assumptions behind the valuation, and take independent advice where the circumstances are complex. This allows the offer to be assessed on its actual terms rather than on an unverified initial estimate.
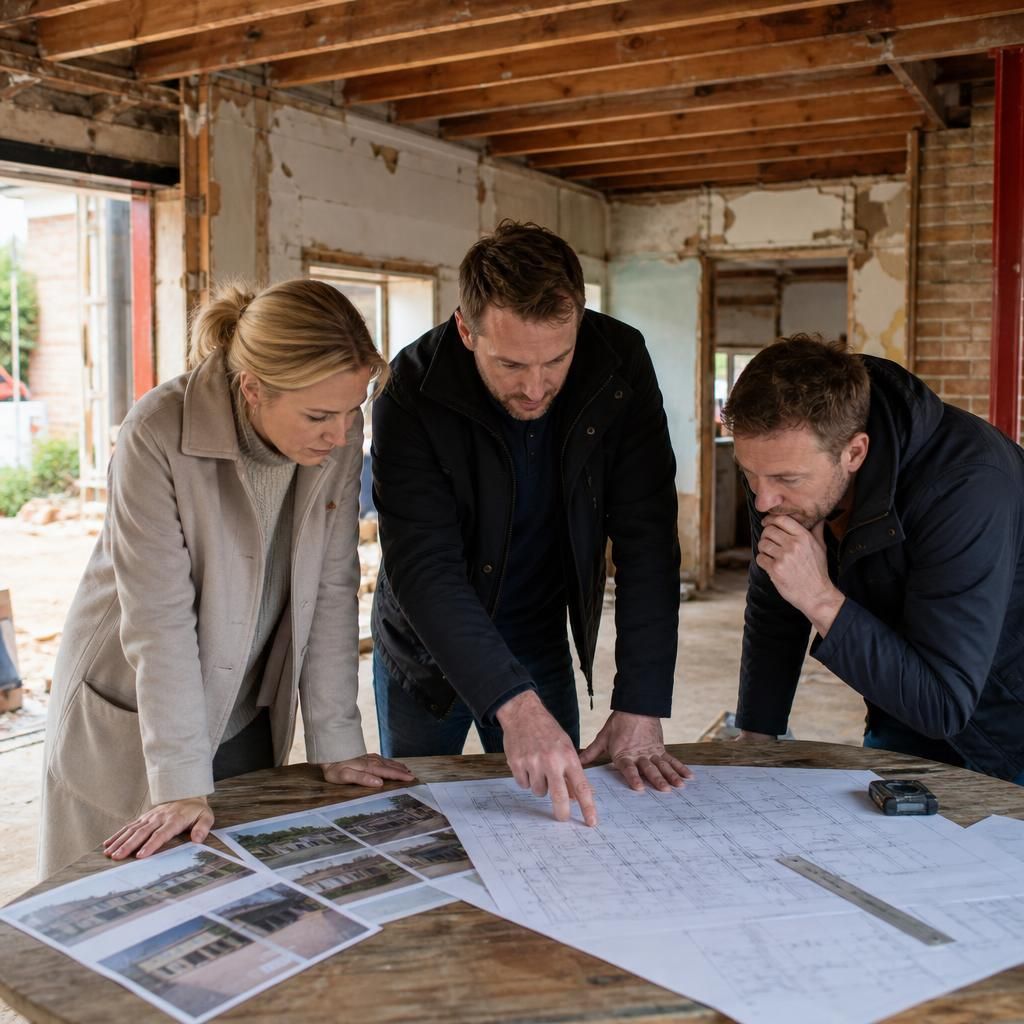
For a property requiring substantial refurbishment, conversion or redevelopment, the buyer may use a residual valuation. This starts with an estimate of the property’s value once the proposed works are complete, then deducts the expected construction, professional, planning, compliance and resale costs, together with an allowance for development risk. The remaining amount helps establish the maximum purchase price that makes the project viable.
This approach means two properties with similar current appearances can receive different offers if their potential uses, permissions or work requirements differ. It also explains why planning uncertainty, difficult access or an unclear scope of works can reduce an offer even where the existing building appears sound.