

What are the advantages and disadvantages of selling a property as-is for cash?
Selling a property as-is for cash can reduce the need for repairs, viewings and prolonged marketing, making the process more straightforward than a traditional sale. However, the offer may be below the price achievable after improvements, and you should review the valuation, costs, legal terms and buyer’s credibility before accepting.
Selling a property as-is for cash means agreeing a sale based on its present condition, without making the transaction dependent on a mortgage application by the buyer. The main advantages are reduced reliance on lender approval, greater flexibility in negotiating the transaction and less exposure to some uncertainties associated with a conventional sale. The disadvantages include a potentially lower net return, limited room to correct mistakes after agreeing the price, and the need to check carefully that the proposed buyer and terms are genuine.
Advantages of an as-is cash sale
- Less dependence on mortgage finance: A cash buyer does not normally need a mortgage valuation or formal lending decision to fund the purchase. This can remove one source of delay and reduces the risk of a lender declining the buyer’s application after the parties have agreed terms. You should still ask for suitable evidence that the buyer has the funds available.
- Potentially simpler negotiations: A cash transaction may involve fewer conditions connected with borrowing, such as a lender’s requirements about the property’s condition, title or market value. This does not eliminate conveyancing or searches, but it may make the agreement less dependent on third-party finance.
- More control over the transaction structure: The parties can discuss the proposed completion date, included fixtures and fittings, vacant possession and any arrangements for leaving belongings at the property. Written terms are important because informal agreements can lead to disputes.
- Reduced exposure to a property chain: If the buyer is purchasing without needing to sell another property, the sale may be less vulnerable to another transaction collapsing. This point must be verified rather than assumed: a buyer describing themselves as a cash purchaser may still have a related sale or other funding condition.
- Less public marketing information: A direct sale can reduce the amount of information and photography circulated publicly compared with a widely marketed listing. This may be relevant where privacy is important, although the buyer, conveyancer and relevant authorities will still need accurate information.
- Useful where circumstances make a conventional sale difficult: An as-is cash sale may be considered for inherited property, an empty house, a property with an unresolved defect or a home affected by complicated personal circumstances. Suitability depends on the title, occupancy, condition and the seller’s legal position, not simply on the fact that cash is available.
Disadvantages and risks
- The headline offer may not equal the amount you receive: Ask for a written breakdown showing the agreed price, any proposed deductions, legal costs, redemption of a mortgage or other secured borrowing, and the final amount payable to you. A comparison should be made using net proceeds rather than the headline figure alone.
- There may be less opportunity to renegotiate upwards: Once the buyer has assessed the property and the condition has been reflected in the offer, discovering that an improvement could have added value may not provide a realistic basis for changing the agreed price. Obtain an independent opinion of value before accepting an offer if the difference would affect your decision.
- “As-is” does not remove disclosure duties: You should answer property information forms accurately and disclose known issues, disputes, notices, alterations without approval, boundary matters, rights of way and problems affecting services or occupancy. Deliberately withholding a material fact can create legal and financial consequences after completion.
- Cash does not mean that checks can be skipped: The buyer’s solicitor will still need to investigate title and may raise enquiries or request searches. The buyer and their representatives may also need to complete identity, source-of-funds and anti-money-laundering checks. An apparently simple sale can stall if documents are missing or ownership is unclear.
- Fraud and poor-practice risks remain: Be cautious of pressure to sign immediately, requests for unexplained upfront payments, unclear deductions, contracts that allow the buyer to withdraw broadly, or claims that independent legal advice is unnecessary. Confirm the buyer’s identity, funding position and contractual role, particularly if the buyer is acting through a company or intends to transfer the contract.
- Personal financial consequences may apply: If the property is mortgaged, check whether early repayment charges or other redemption costs will be deducted. Depending on the property and your circumstances, tax may also need consideration. A conveyancer or tax adviser can explain the position, particularly where the property is inherited, jointly owned, rented out or not your main residence.
How to assess whether it is suitable
- Obtain a realistic independent view of the property’s market value and estimate the net proceeds from each available sale route.
- Request the cash buyer’s offer and all conditions in writing, including the proposed completion arrangements and every deduction.
- Use a solicitor or licensed conveyancer who acts for you alone. Do not rely solely on documents or advice supplied by the buyer.
- Check title documents, mortgage details, planning and building-regulation records, tenancy arrangements and any known disputes before committing.
- Verify proof of funds and establish whether the buyer is purchasing directly, through a company or as an intermediary.
- Read the contract carefully before signing and make sure you understand what happens if either party withdraws or fails to complete.
An as-is cash sale is most suitable when certainty, reduced dependence on finance or a negotiated transaction structure is more important than achieving the highest possible sale price. It is less suitable where the property has substantial unrecognised value, the offer is based on unclear deductions, or the seller has not had enough time to obtain independent legal and financial advice.
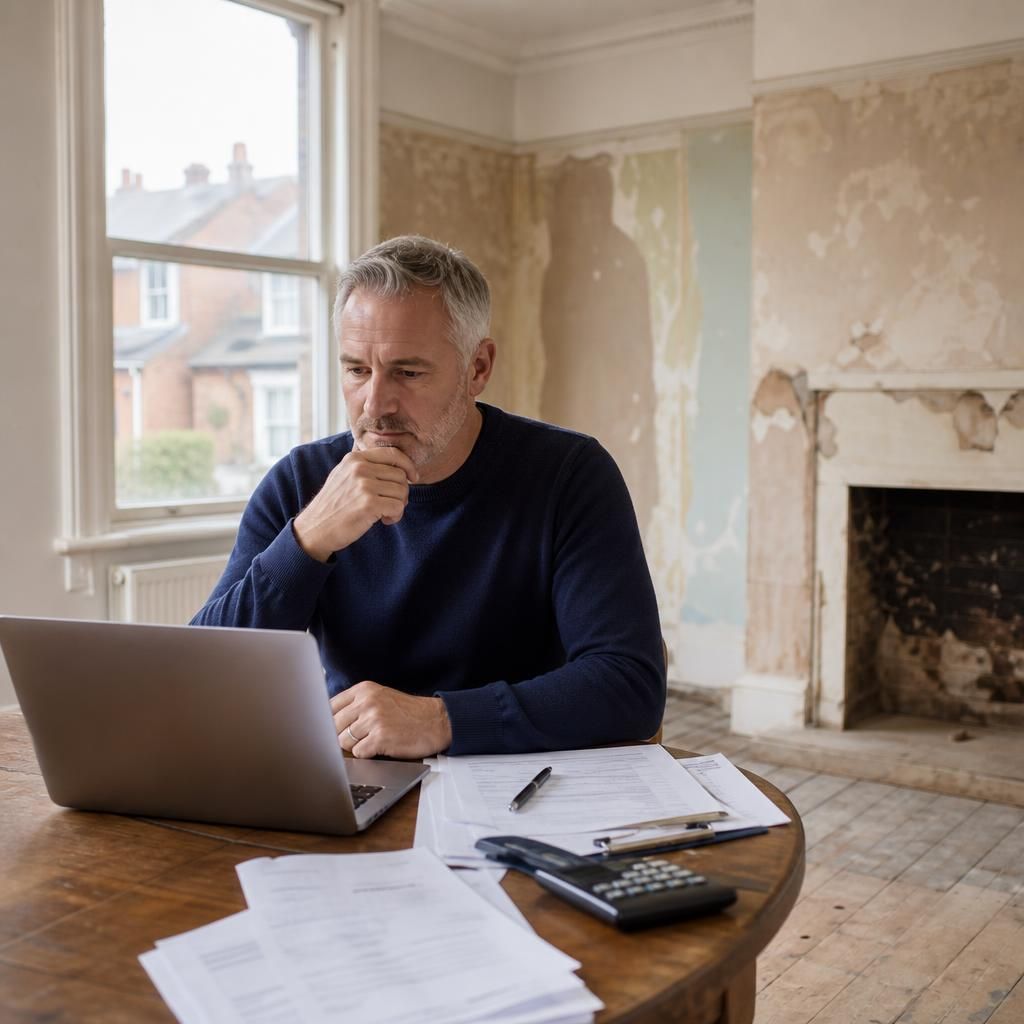
An as-is cash offer should be assessed against the value of avoiding the work and uncertainty involved in a conventional sale, not only against the property’s potential value after refurbishment. A buyer may allow for repairs, clearance, compliance work, resale risk and the cost of holding the property before it can be sold. This can make the offer lower than an improved-market valuation without necessarily indicating that it is unreasonable.
To compare options properly, estimate the likely cost of preparing and marketing the property, the time involved, professional fees and the risk that unexpected defects reduce the eventual price. Then compare the resulting net amount with the cash buyer’s written offer. This provides a more useful basis for deciding whether the convenience of selling in its current condition justifies accepting a lower potential return.
Assess your options for selling your property as-is for cash
If you are considering an as-is cash sale, contact buyhousesfast.co.uk to discuss your property and request an offer based on its current condition. Review the proposed terms with your own solicitor or licensed conveyancer before deciding whether to proceed.