

How does selling a house as-is fast differ from traditional home sales?
Selling a house as-is fast usually means accepting the property in its current condition, without completing repairs or marketing it through an estate agent. Traditional home sales typically involve preparing the property, arranging viewings, negotiating with buyers and managing a longer transaction process before completion.
Selling a house as-is fast differs from a traditional home sale mainly in the balance between certainty and open-market exposure. An as-is sale generally prioritises a direct assessment of the property and a straightforward cash transaction, while a traditional sale is structured around testing the market, attracting suitable purchasers and progressing through the usual buyer and lender checks.
The main differences are:
- How the price is established: An as-is cash offer reflects the property’s current condition, its location, likely resale value and the cost and risk of any work the buyer may need to undertake. A traditional sale usually starts with an asking price designed to attract market interest. The final price then depends on competing offers, negotiations and the buyer’s valuation.
- Choice of buyer: A traditional sale exposes the property to a wider pool of potential purchasers, including people buying with a mortgage. An as-is fast sale is more likely to involve a cash buyer who is prepared to assess the property in its present state. This can be relevant where the condition, title or circumstances make the property less suitable for an ordinary retail buyer.
- Mortgage dependency: A traditional purchaser may need a mortgage offer before the transaction can proceed. The lender can also require a valuation and may raise concerns about the property’s condition or legal status. A cash purchase does not depend on mortgage approval, although the buyer and their solicitor still need to complete appropriate checks.
- Transaction certainty: In a traditional sale, an accepted offer is not the same as a completed sale. The buyer may withdraw, fail to secure finance or renegotiate after a survey. An as-is cash route can reduce reliance on those particular stages, but it is not risk-free. The proposed price can still change if legal investigations, valuation evidence or material property information reveals an issue.
- Property condition: The phrase “as-is” does not remove the seller’s responsibility to answer questions accurately. Known defects, alterations, disputes, notices, boundary matters and other material information should be disclosed. A buyer accepting the property’s condition is not necessarily accepting undisclosed legal problems or misrepresentation.
- Legal process: Both routes normally require conveyancing, identity checks, title review and responses to property information forms. Traditional sales may involve a buyer’s survey and lender requirements. An as-is sale may involve fewer property-improvement expectations, but the legal title, ownership position, restrictions and completion arrangements still need proper attention.
- Costs and control: A traditional sale can involve estate-agent fees and seller-funded preparation, alongside the cost of maintaining the property while it is marketed. A direct as-is sale may reduce the need for presentation work and can offer a more defined negotiation with one buyer. The seller should compare the proposed net proceeds, including any legal fees or other transaction costs, rather than comparing headline prices alone.
For example, a home with significant repairs, an inherited property, or a house affected by arrears may be difficult to present as a conventional market sale. An as-is cash offer may provide a more relevant route because the assessment is based on the property in its existing state. That does not mean the offer will always be higher or that completion is automatic; the seller must weigh the price against the value of avoiding preparation, market uncertainty and a potentially extended transaction.
In the UK, sellers should also distinguish between an agreed cash offer and cleared funds available for completion. Ask what evidence supports the buyer’s funding, whether the offer is subject to further inspection or valuation, which conditions could lead to renegotiation, and whether the buyer intends to assign or resell the contract. These questions help reveal how firm the proposed transaction is.
Before choosing either route, obtain an independent view of the property’s market value where appropriate and request a clear written breakdown of the offer. Check the buyer’s identity, use a suitably qualified conveyancer and avoid signing documents you do not understand. A direct buyer such as buyhousesfast.co.uk may be relevant to owners seeking a UK cash-sale option, but the same checks should apply as they would to any property transaction.
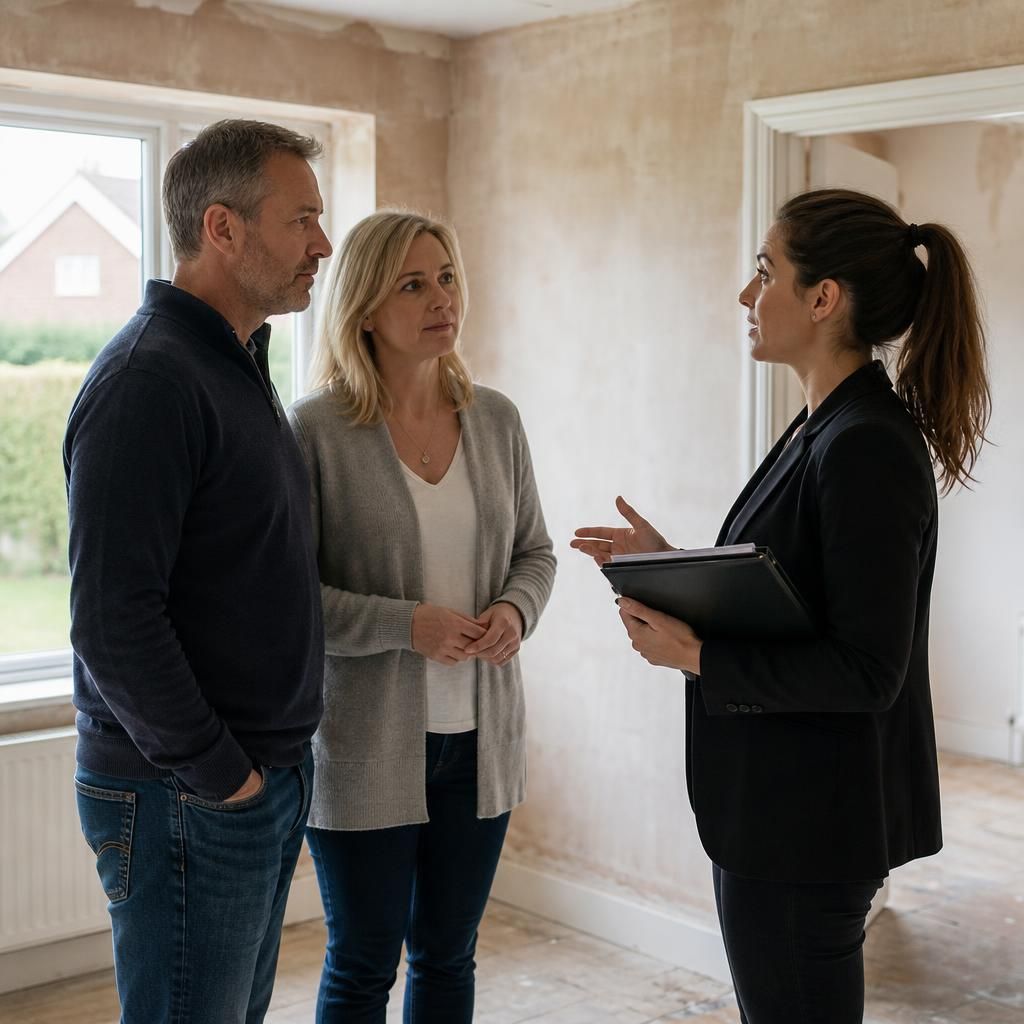
A further difference is the level of public exposure. A traditional sale commonly involves online photographs, floor plans, a public asking price and repeated viewings, which can attract more potential buyers but also disclose that the property is being marketed. An as-is sale negotiated directly with one buyer may involve less public advertising and fewer interruptions, depending on the arrangement.
This discretion can matter where the property is occupied, undergoing probate, affected by personal circumstances or difficult to present. The trade-off is that a privately negotiated sale gives the seller less opportunity to compare competing interest. Before agreeing, clarify what information will be shared, who will access the property and whether any marketing or viewings are expected.