

What are the benefits of selling a complex property for cash?
Selling a complex property for cash can simplify the transaction by reducing reliance on open-market marketing, accommodating an as-is sale and avoiding estate agent fees. It may also provide a more direct route to completion where legal, physical or timing issues make a traditional sale difficult.
Selling a complex property for cash can offer greater control over the transaction, particularly where mortgage finance, a property chain, unusual documentation or an uncertain timetable could make a conventional sale difficult. The main benefits are reduced dependence on third-party finance, more adaptable arrangements and a clearer process for dealing with known complications.
- Less risk of mortgage-related delay: A cash buyer does not normally need to wait for a lender to approve a mortgage, carry out lender-specific checks or issue a mortgage offer. This removes one potential source of delay and reduces the risk of the buyer withdrawing because finance is unavailable. The buyer will still need to complete appropriate legal and financial checks.
- Greater flexibility over completion: Complex sales often involve probate administration, separation arrangements, mortgage arrears, relocation or another deadline. A cash transaction may allow the parties to discuss a completion date that fits the seller’s circumstances, subject to the buyer’s due diligence and the conveyancers’ ability to complete the legal work.
- Fewer dependencies in the transaction: A conventional sale can be affected by the buyer’s mortgage lender, survey requirements, sale of another property and decisions elsewhere in a chain. Selling to a cash buyer can reduce the number of linked events that need to happen before completion. It does not remove the need for searches, title checks or agreed contract conditions, but it may make the transaction less dependent on unrelated buyers and sellers.
- A practical route for properties that need explanation: A property with an unusual title, non-standard construction, planning history, a sitting tenant, damage or an occupancy issue may attract questions from conventional buyers and their lenders. A cash buyer may be able to assess those matters directly rather than relying on standard mortgage criteria. This can help the seller understand which issues must be resolved and which can be reflected in the agreed price.
- Reduced disruption before completion: A cash sale may involve fewer rounds of viewings, repeated negotiations and buyer requests than a typical open-market campaign. That can be useful where the property is occupied, access is difficult, its condition makes viewings impractical or the seller needs to manage a sensitive personal situation. The precise arrangements should be agreed at the outset rather than assumed.
- More straightforward financial planning: Once the price and contractual terms have been agreed, the seller can assess the likely proceeds and outstanding obligations with greater clarity. This is particularly relevant where the property is subject to arrears, secured borrowing, probate expenses or other payments. The seller’s conveyancer should confirm the exact redemption figures, fees and liabilities before completion.
- Potentially greater privacy: A direct transaction can limit the amount of personal information and property detail placed in public marketing materials. This may matter when the sale relates to divorce, financial difficulty, an inherited home or a property that is vacant. Privacy is not absolute, because identity checks, source-of-funds checks and legal disclosures may still be required.
These benefits arise because the transaction is assessed around the property’s actual circumstances rather than solely against the expectations of a standard residential sale. However, a cash sale is not exempt from legal requirements. The buyer’s conveyancer will usually need to investigate ownership, restrictions, rights of way, planning matters, searches and any charges secured against the property. Problems with title or authority to sell can still prevent completion until they are resolved.
The seller should also compare the complete financial outcome, not just the headline offer. A cash buyer may price in the cost of repairs, legal risk, clearance, vacant possession or work needed to make the property acceptable to a future buyer. Ask for the proposed price, deductions, contractual conditions and expected seller costs in writing, and obtain independent legal advice before signing. Where there is a mortgage, charge, tenancy, probate issue or co-owner, the relevant consent and repayment requirements should be established early.
In practical terms, the strongest benefit is often predictability: the seller can evaluate a known proposal against the complications of continuing with a traditional sale. A cash option is most suitable when control over the process, flexibility around completion and reduced reliance on mortgage finance are more important than maximising exposure to the open market. The right choice depends on the property’s condition, legal position, financial commitments and the seller’s priorities.
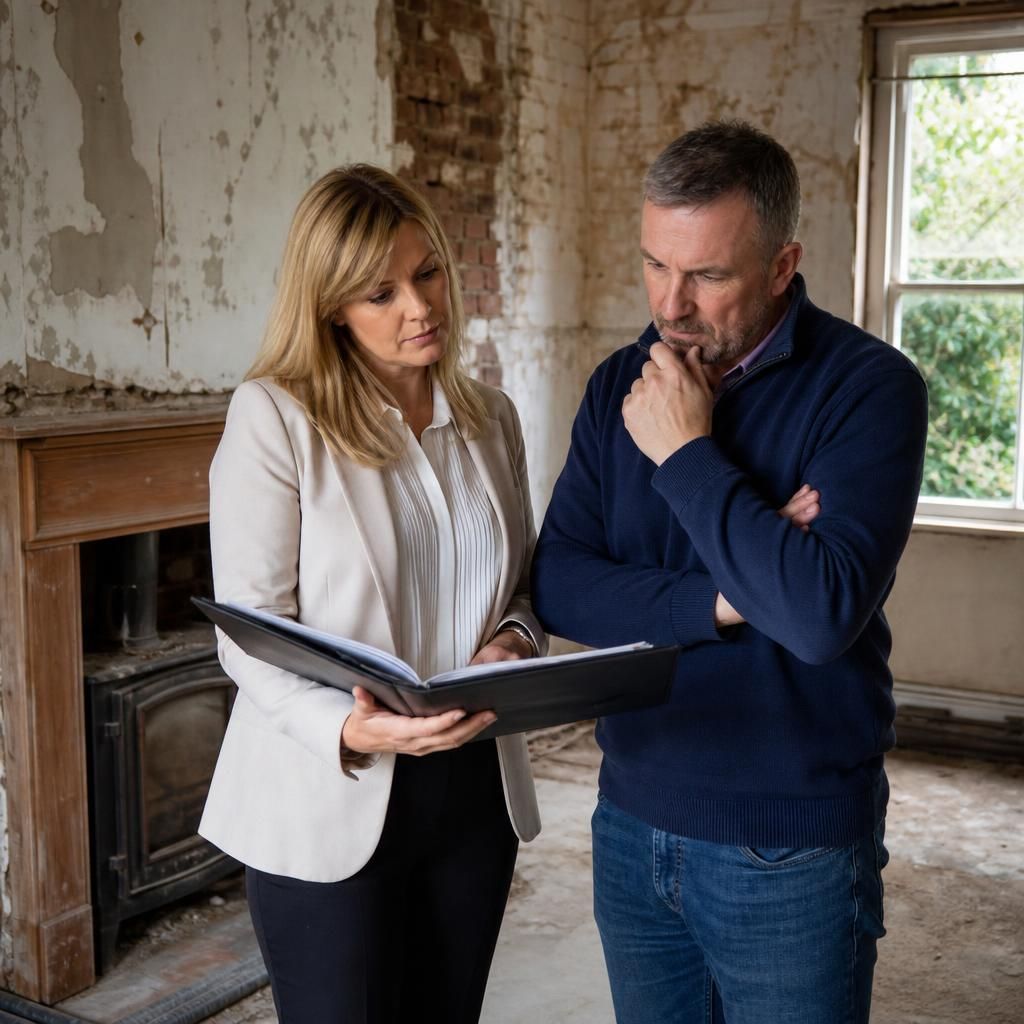
One benefit of a cash sale is that it can provide a clearer comparison when an unusual property is difficult to value through standard market evidence. Instead of relying solely on nearby sales of conventional homes, the seller can assess a proposal against the property’s specific condition, title position, occupancy arrangements and likely preparation costs.
This does not make the offer automatically better than an open-market sale. It gives the seller a practical basis for weighing certainty and convenience against the possibility of achieving a higher price through wider marketing, after allowing for the time, costs and work that route may involve.
Discuss the benefits of selling your complex property for cash
If you are considering a cash sale for a complex property, provide the relevant property and legal details to request an offer based on its circumstances. Review the proposed price, deductions and contractual terms with your conveyancer before deciding whether it suits your priorities.