

What factors can affect the valuation of a complex property in a fast cash sale?
A complex property’s fast-cash valuation can be affected by its location, condition, size, local demand and the likely cost of repairs or clearance. Legal or planning issues, title restrictions, occupancy arrangements, access problems and the timescale or certainty of completion can also influence the offer.
The valuation of a complex property in a fast cash sale is usually based on its probable net value to the buyer, rather than on an optimistic open-market asking price. The assessment considers the evidence available, the work needed to make the property saleable, the risks attached to completing the purchase and the buyer’s likely exit route.
Comparable evidence is a starting point. A valuer may review recent sales of broadly similar properties, but complex homes often have few genuinely comparable examples. Differences in tenure, layout, access, condition, occupancy or legal status can make a direct comparison unreliable. Older transactions may also be less relevant if market conditions have changed. For that reason, the valuer may place more weight on several imperfect comparables and adjust each one to reflect the property being assessed.
The property’s usable potential can be more important than its current presentation. For example, a building may have potential for refurbishment, subdivision, conversion or an extension. That potential does not automatically add its full estimated end value. The assessment may account for design work, professional fees, finance, construction risk, planning uncertainty, holding costs and the time required before the enhanced value could be realised. A potential improvement generally carries more weight when it is supported by planning history, permissions, drawings or other reliable evidence.
Tenure and management arrangements can materially alter the calculation. A freehold house, leasehold flat and property with an unusual form of ownership may not be valued in the same way. Relevant details can include:
- the remaining term of a lease;
- ground rent and service-charge obligations;
- restrictions on alterations, subletting or use;
- shared ownership or other third-party interests;
- responsibility for maintaining shared areas; and
- whether required consents have been obtained.
These points can affect both the property’s attractiveness to a future buyer and the cost of resolving issues before resale.
Occupancy can affect both risk and practical value. A vacant property may be easier to inspect, secure and prepare for resale. A property occupied by tenants, family members or other parties may require additional checks concerning rights of occupation, notice, possession and the handling of belongings. The valuation may therefore reflect uncertainty about control of the property, not simply its physical characteristics.
Documentation quality also matters. A cash buyer will usually need to establish that the seller can transfer good title and that the property can be used and sold as represented. Missing deeds, inconsistent plans, unresolved charges, absent guarantees, boundary discrepancies or incomplete building-regulation records can lead to further investigation. Where a problem cannot be verified or corrected easily, the buyer may allow for professional advice, delay or the possibility that a future purchaser will raise the same issue.
Risk is often reflected through an adjustment rather than a single repair deduction. A valuation may take account of the chance that an anticipated cost is higher than expected, that a permission is refused, that access is unavailable or that a transaction does not complete on the intended terms. The greater the uncertainty, the more cautious the assessment is likely to be. This is why two buyers can reach different figures while using much of the same information.
Specialist features may have limited resale value. Features such as commercial-style fittings, non-standard room layouts, unusual construction methods or highly personalised alterations can be expensive to remove and may appeal to a narrow group of future purchasers. Their original installation cost is not necessarily evidence of their current value. A valuer is more likely to consider whether the feature improves marketability, has a recognised use and is properly documented.
Environmental and building-related issues can influence the net figure. Possible concerns may include contamination, flooding history, structural movement, subsidence, Japanese knotweed, asbestos-containing materials or defective construction. The effect depends on the evidence available and whether the issue can be investigated, insured or remedied. A suspected problem is not the same as a confirmed defect, but insufficient information can still create valuation uncertainty.
For a fast cash sale, the proposed transaction terms can also affect the final offer. A buyer may consider the level of certainty provided by the title documents, the scope for further negotiation after surveys, the required completion arrangements and whether the sale depends on another transaction. These are not qualities of the property itself, but they influence the risk and cost of acquiring it.
To support a more reliable assessment, a seller should provide accurate information at the outset, including title documents, lease details, planning and building-control paperwork, tenancy agreements, guarantees, notices, repair reports and details of known disputes. Concealing an issue can lead to a revised offer or a failed transaction once it is discovered. A clear record allows the buyer to distinguish confirmed costs from assumptions and reduces the need for broad risk allowances.
The most useful comparison is not always between an offer and the highest advertised price nearby. It is between the proposed net proceeds, the certainty of the terms and the risks the seller would retain under other selling methods. Any offer should be reviewed alongside its conditions, deductions, timescales and treatment of known defects. Independent legal or valuation advice may be appropriate where the property has substantial title, tax, planning or ownership complexity.
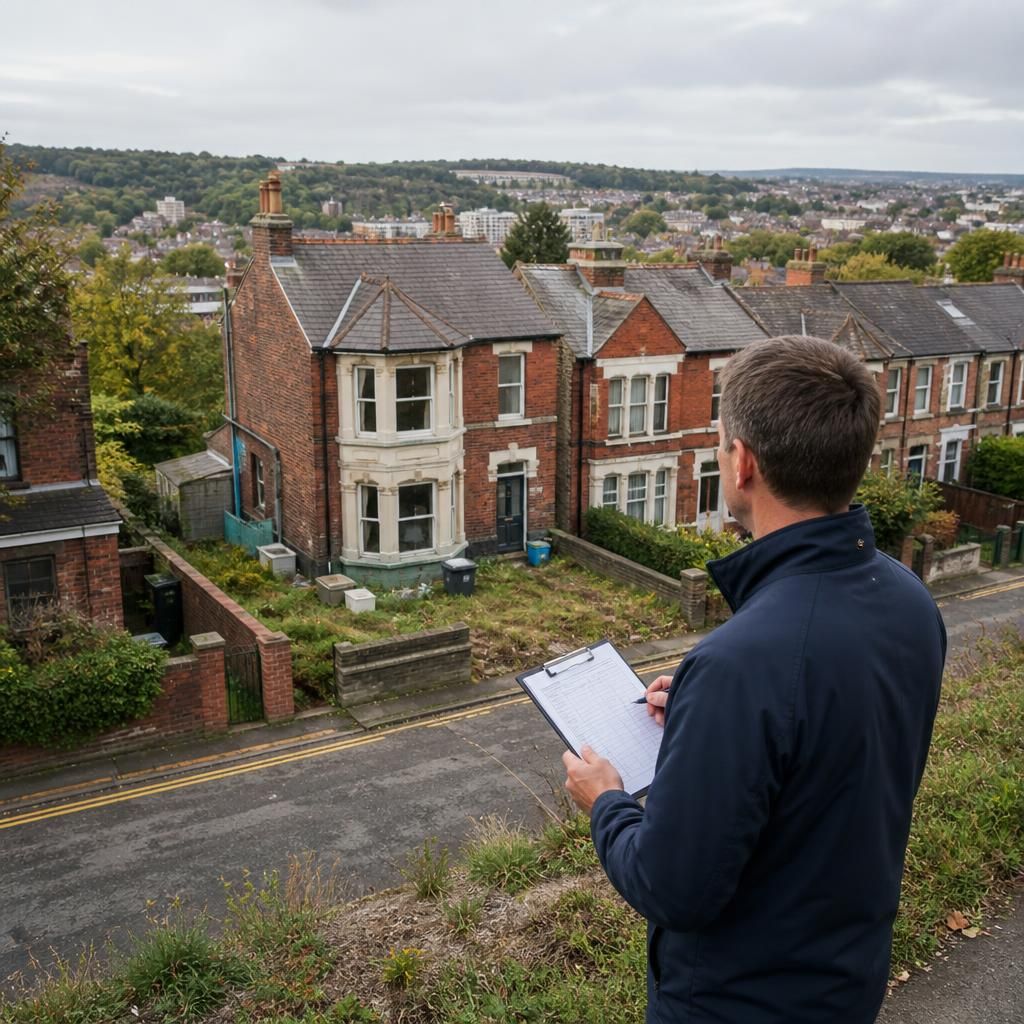
Local market conditions can significantly affect a complex property’s valuation. A home in an area with limited comparable sales, weaker demand or a high level of competing stock may be assessed more cautiously than a similar property in a stronger market. The valuer may consider recent transactions, the time comparable homes take to sell and whether local buyers typically accept the property’s condition, layout or tenure.
Micro-location also matters. Access to the property, parking, nearby infrastructure, flood exposure and the character of the immediate surroundings can influence the number of potential future buyers. These factors may affect the price achievable after purchase and therefore the figure a cash buyer can justify before allowing for the costs and risks of the transaction.