

What legal considerations should homeowners be aware of when selling a complex property for cash?
When selling a complex property for cash, homeowners should verify ownership and title, resolve any restrictions or charges, disclose known defects and legal issues accurately, and ensure the sale contract reflects the agreed terms. Independent advice from a conveyancing solicitor can help identify risks, check the buyer’s documentation and manage completion securely.
Legal considerations in a cash sale extend beyond the agreed price. A cash buyer may not need a mortgage, but the transaction still requires proper conveyancing, identity checks, contract formalities, property investigations and a legally valid transfer. The exact requirements depend on the property, the seller’s circumstances and whether the home is in England, Wales, Scotland or Northern Ireland, so independent advice from a solicitor or licensed conveyancer is important.
Confirm who has authority to sell. Every person with a legal interest or relevant authority should be identified before terms are agreed. This can be more complicated where the property is jointly owned, held by a company or trust, or being sold under a power of attorney. A power of attorney may need to be checked for its scope and continued validity. If an owner lacks mental capacity, additional legal procedures may apply. A solicitor should also consider whether anyone could later argue that the seller was pressured, misled or unable to understand the transaction.
Where a relationship has ended, the property may form part of financial arrangements that have not yet been finalised. A divorce, separation agreement or court order can affect who is entitled to sell and how the proceeds should be distributed. Selling without addressing those rights can create a dispute after completion, even if the transfer itself has been signed.
Take extra care with probate sales. If an owner has died, the personal representatives must usually establish their authority to deal with the estate. This may involve a grant of probate or letters of administration, depending on the circumstances. The will, estate administration and any rights of beneficiaries should be reviewed before contracts are exchanged. A property should not be treated as an ordinary sale simply because a cash buyer is involved.
Check occupancy and possession arrangements. A buyer may expect vacant possession, but that cannot always be provided immediately. Tenants, lodgers, family members and other occupiers may have legal rights that affect the sale or the handover date. Tenancy agreements, notices and any protected deposits should be reviewed. An informal arrangement is not necessarily legally irrelevant, and removing an occupier without following the correct process can lead to further liability.
If the property is being sold with an occupier remaining, the contract should state clearly what arrangement continues after completion. If vacant possession is required, the seller should obtain specific advice about the steps needed to achieve it rather than relying on a verbal understanding with the buyer.
Investigate planning and building matters. Alterations such as extensions, loft conversions, removed walls, changes of use and outbuildings may require planning permission, building regulation approval or completion certificates. Conservation area controls, listed-building requirements, restrictive estate rules and local notices may also be relevant. Missing paperwork does not automatically make a sale impossible, but it can affect the buyer’s assessment, the contract and the need for indemnity insurance or retrospective approval.
Do not assume that a cash sale removes the need to answer property information forms accurately. A buyer can still investigate planning history, drainage, access, environmental matters and local authority records. If information is uncertain, the safer approach is to tell the conveyancer what is known and allow them to advise on the appropriate wording or evidence.
Understand the contract before exchange. Heads of terms or an informal offer are not the same as a binding sale contract. The solicitor should check the purchase price, deposit, completion date, items included or excluded, possession arrangements and any special conditions. Fixtures, fittings, appliances, rubbish, outbuildings and contents should be described precisely where they could cause disagreement.
Once contracts are exchanged, withdrawal may have serious financial consequences. A cash buyer’s lack of mortgage finance does not mean the buyer can change the terms without consequence, nor does it give the seller an automatic right to cancel. The parties should establish whether the proposed arrangement is conditional on surveys, searches, title work or another event. Any condition should be written into the contract rather than left as an informal promise.
Verify the buyer and the funds. Solicitors and conveyancers must comply with anti-money-laundering and identity requirements. The buyer may need to demonstrate where the purchase money comes from, even where no lender is involved. Sellers should be cautious about requests to send money to a new bank account or to alter payment instructions by email. Bank details should be verified through a trusted channel, because property transactions are targeted by payment fraud.
A seller should also establish who is actually buying the property. If an individual, company, trust or nominee appears in the paperwork, the solicitor can explain the effect on the contract and transfer. A proposed cash purchase is not a reason to bypass identification, source-of-funds checks or professional conveyancing.
Allow for redemption and payment arrangements. If borrowing is secured against the home, the conveyancer normally needs to obtain a settlement figure and arrange repayment from the sale proceeds. Other sums may also need to be apportioned or settled, such as service charges, ground rent, rent received, management fees or communal maintenance costs. The seller should ask for a completion statement showing how the money will be applied and what amount is expected to remain.
Consider tax and estate consequences. The sale may have implications for capital gains tax, inheritance tax, income tax or means-tested support, depending on ownership, occupation, the seller’s wider finances and the reason for the sale. A cash buyer does not determine the seller’s tax position. Specialist tax advice may be needed, particularly where the property was inherited, used as a business or rental property, transferred between connected people, or owned through a company or trust.
There may also be consequences for beneficiaries, creditors or parties involved in insolvency proceedings. If the seller is insolvent or at risk of insolvency, obtaining advice before accepting a price is particularly important. A transaction that appears straightforward can be challenged if it disadvantages creditors or involves an undervalue.
Keep the legal process independent. A cash buyer may recommend a preferred solicitor or conveyancer, but the seller is entitled to choose independent legal representation. The adviser should explain the documents in plain language, identify conflicts of interest and confirm that the proposed price and conditions reflect the seller’s instructions. Do not sign a transfer, contract, declaration or authority that is not understood.
Before committing, ask the conveyancer to confirm what searches are being ordered, what information is still outstanding, whether vacant possession is required, how completion money will be transferred and what happens if an agreed date is missed. These checks do not prevent every risk, but they create a clear legal record and reduce the chance that a fast cash sale becomes a later dispute.
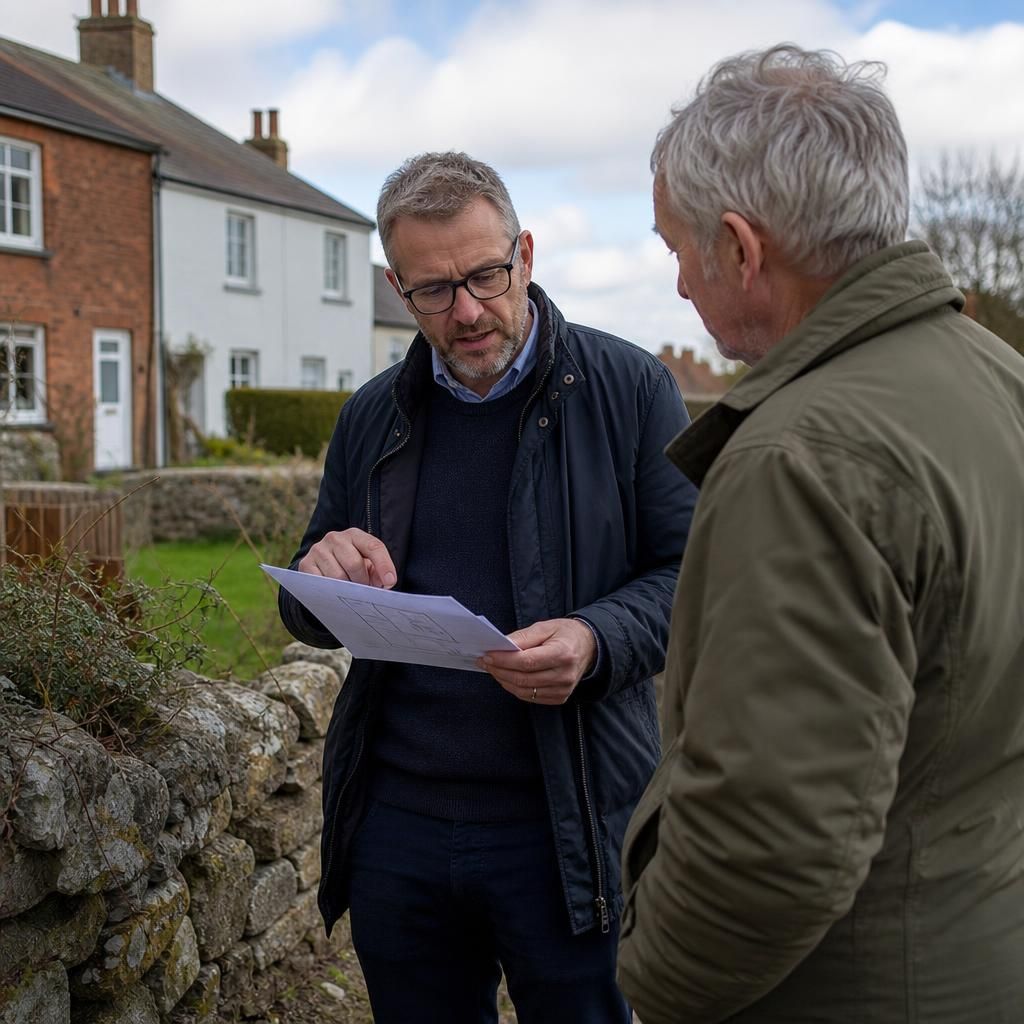
Check boundaries, access and rights affecting the property. A complex sale should account for easements, rights of way, shared driveways, access across neighbouring land, boundary disagreements and restrictive covenants. These matters may appear in the title register or other conveyancing documents, but the position on the ground can differ from the paperwork. Tell the conveyancer about any dispute, informal access arrangement or shared maintenance responsibility, and provide relevant correspondence or agreements. The solicitor can then explain whether the issue needs clarification, a deed, an undertaking or a specific contract provision before completion.