

How does the condition of my property affect an instant cash offer?
The condition of your property can affect an instant cash offer because repair costs, structural problems, damage and legal complications may be reflected in the buyer’s valuation. A property requiring substantial work may receive a lower offer than a comparable home in good condition, although cash buyers may still consider properties that need renovation.
An instant cash offer is normally based on the property’s likely value in its present state, rather than its value after an owner has completed improvements. The buyer will assess the work needed, the uncertainty involved and the property’s resale prospects before deciding the amount offered.
Not every defect has the same effect. A buyer will usually distinguish between cosmetic work, routine maintenance and issues that could affect the building’s safety or usability. For example, dated decoration, worn flooring or an untidy garden may be relatively straightforward to address. Damp, roof defects, subsidence, unsafe electrics, plumbing failures, significant structural movement or extensive water damage can require specialist investigation and more substantial expenditure.
- Cosmetic condition: decorating, flooring, kitchen units, bathroom fittings and general presentation may influence the valuation, but they do not necessarily prevent a sale.
- Maintenance issues: ageing boilers, damaged windows, leaking gutters or defective appliances can lead to deductions based on repair or replacement requirements.
- Structural and safety concerns: movement, roof problems, fire damage, hazardous materials or unsafe installations can increase both the expected cost and the uncertainty of the transaction.
- Occupancy and usability: a property that is vacant, partly unusable or occupied under an existing arrangement may require a different assessment from a straightforward owner-occupied home.
Condition is considered alongside the property’s size, location, layout and comparable market evidence. A home needing modernisation may still attract a reasonable offer if the work is clearly identifiable and the underlying property is suitable. By contrast, undisclosed defects can make the valuation less certain and may lead to revised terms if they emerge during inspections or legal enquiries.
Accurate information helps produce a more reliable initial assessment. Useful details include the age and condition of the roof, boiler, windows and electrics; any history of flooding, subsidence or insurance claims; known damp or structural movement; alterations to the layout; and planning or building-regulations documents for extensions or conversions. Photographs, invoices and survey reports can also help demonstrate what has been repaired and what remains outstanding.
The buyer may arrange a viewing, survey or specialist inspection before confirming the offer. This is not simply a check of decoration. It can identify defects that are not visible during a brief visit, such as timber problems, drainage faults or concealed water damage. If the findings differ materially from the information provided, the buyer may adjust the offer, request further evidence or decide that the property does not meet their criteria.
Before accepting an offer, separate essential work from improvements that are mainly intended to increase presentation or market appeal. Obtain independent estimates where a major defect is involved, and compare the proposed price with the likely value of the property in its current condition. A traditional sale may allow time to carry out improvements, while a cash sale generally assesses the home as it stands; the relevant comparison is therefore between the net proceeds, the work you would undertake and the risks of each route.
Ask for the valuation assumptions to be explained in writing. The offer should make clear whether it depends on a survey, vacant possession, particular documents or further legal checks. Understanding these conditions allows you to identify whether a deduction relates to an evidenced defect, an estimated repair cost or a broader risk allowance. You can then decide whether the price fairly reflects the property’s condition and your circumstances.
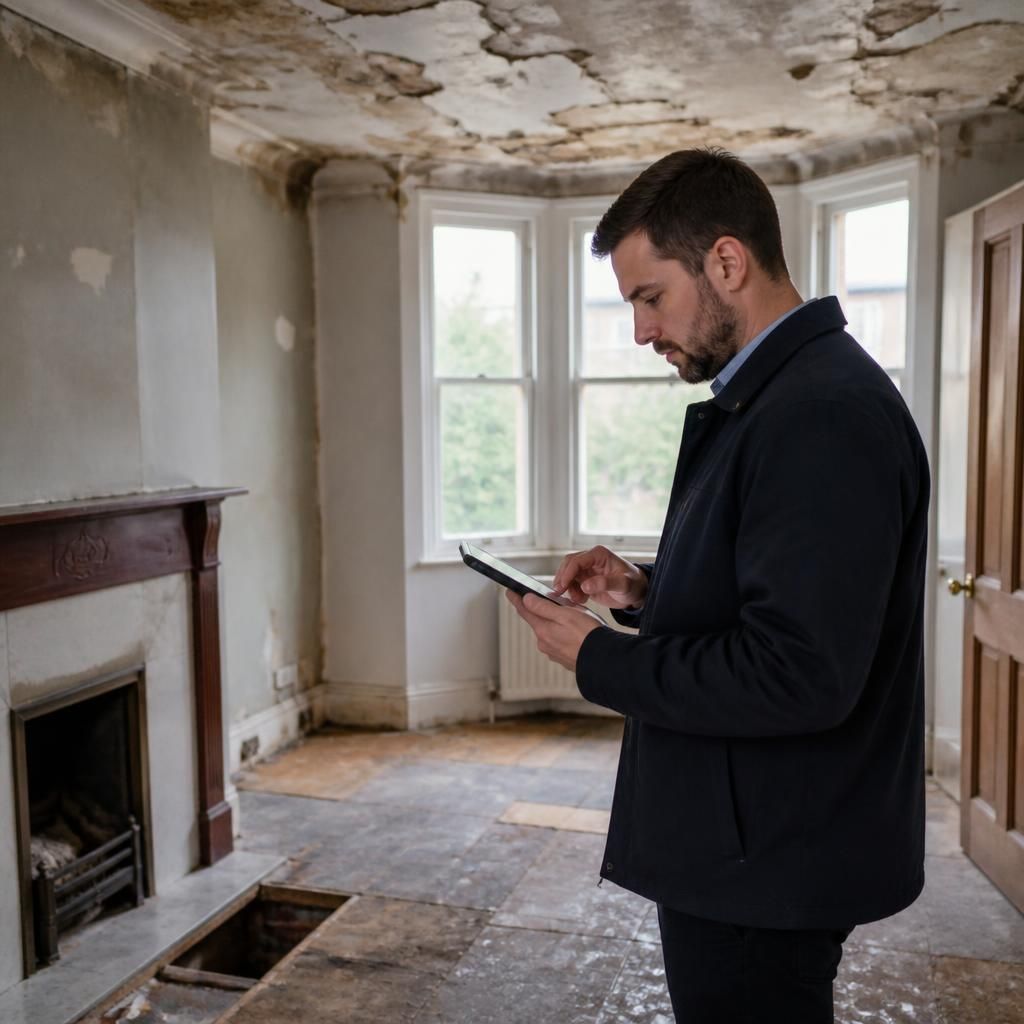
Property condition can affect an instant cash offer through the risk it creates for the buyer, not only through the cost of repairs. A home with severe defects, unresolved damage or uncertain compliance may be harder to insure, resell or value confidently. The buyer may therefore allow for additional risk when assessing the offer, even where the immediate repair estimate appears manageable.
This is why two properties needing a similar level of work can receive different offers. The condition of the surrounding market, the likelihood of finding a future buyer and the clarity of the property’s history may all influence the assessment. Providing dated photographs, relevant certificates and a clear explanation of known defects can help the buyer distinguish an identifiable renovation project from a property with wider uncertainty.