

Is the cash offer guaranteed, and is the buyer financially capable of completing the purchase?
A cash offer is not guaranteed simply because it has been made, as either party can withdraw before contracts are exchanged. To assess whether the buyer can complete, request evidence of available funds, confirm the buyer’s solicitor and verify that the purchase funds and source-of-funds checks are being handled before proceeding.
A cash offer is an indication of what a buyer is prepared to pay, not a guaranteed purchase. In England and Wales, the sale normally becomes contractually binding only when contracts are exchanged. Until then, either party can usually withdraw, and the buyer may still seek to change the price if new information emerges. In Scotland, the equivalent commitment is created through concluded missives, so the conveyancer should explain the position applying to the property.
“Cash buyer” generally means that the buyer does not need a mortgage to fund the purchase. It does not necessarily mean that all the money is already sitting in an immediately accessible account. Funds might be tied up in another property, an investment, a business sale or another transaction. A buyer who describes an offer as cash should therefore be able to demonstrate a realistic route from the agreed price to the completion funds.
The reliability of an offer depends on more than the headline figure. Review the written offer and check whether it is:
- subject to a valuation, survey, planning investigation or another condition;
- dependent on the buyer selling another property or obtaining additional finance;
- made by the person or company that will actually appear on the contract;
- clear about the proposed completion date and any changes that could affect it; and
- conditional on further negotiation after legal or physical investigations.
Some qualifications are normal. A buyer is entitled to investigate title, boundaries, planning matters, structural issues and other risks before exchange. However, an offer becomes less certain where important conditions are vague, the buyer will not identify the contracting party, or the proposed funding arrangements are unexplained. Ask for every material condition to be recorded in writing rather than relying on a verbal assurance.
Financial capability should be assessed through the conveyancing process, not solely through the buyer’s own statements. Your conveyancer can establish who is providing the money, whether the funds are available for the agreed transaction and whether the proposed payment route satisfies anti-money-laundering and source-of-funds requirements. They can also check that the legal buyer matches the party making the offer. These checks do not create an absolute guarantee, but they reduce the risk of progressing with a buyer who cannot complete.
It is also useful to distinguish between the buyer’s ability to pay and the buyer’s willingness to proceed. A financially strong buyer may still withdraw before exchange, renegotiate after a survey or delay instructions to their legal representatives. Ask what happens if the buyer changes the offer, misses an agreed milestone or introduces a new condition. Keep important communications, the offer terms and any agreed timetable in writing.
Warning signs include pressure to bypass independent legal advice, reluctance to provide the information needed for conveyancing checks, repeated changes to the purchasing entity, unexplained requests for money from the seller, and demands for possession before the legal commitment is secure. Do not transfer money to a buyer or make payments that have not been clearly explained and approved by your conveyancer. A genuine cash sale should still follow the normal legal and identity checks.
The strongest protection is to appoint your own conveyancer, ensure the buyer’s position is checked independently and avoid treating an accepted offer as final until the relevant binding stage has been reached. If certainty is particularly important because of arrears, probate or another deadline, tell the conveyancer at the outset so the transaction risks and proposed dates can be considered before you rely on the offer.
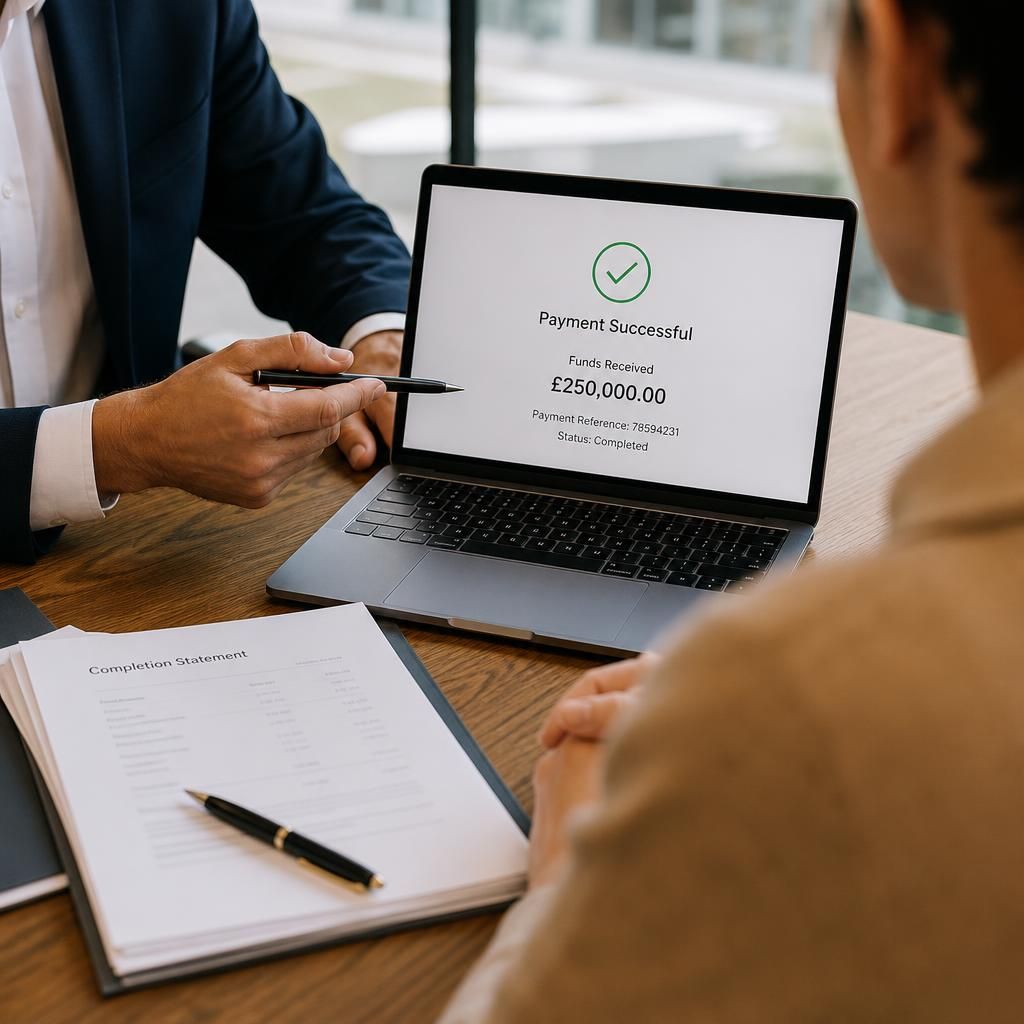
The clearest evidence that a buyer can complete comes at the final payment stage, when the agreed purchase funds are transferred through the conveyancers. Before authorising completion, your conveyancer should confirm that the required money has arrived in cleared funds and that the amount matches the completion statement.
Do not release keys, transfer ownership documents or treat the sale as complete solely because the buyer has sent a payment confirmation. Bank transfers can require verification, and a screenshot or informal message does not replace confirmation from your own conveyancer. Once they confirm receipt and completion, keep the relevant records with the sale papers.
Ask About Your Cash Offer and Buyer Checks
If you are considering a cash sale, ask buyhousesfast.co.uk for a written offer and details of the proposed funding arrangements, then have your conveyancer review them before proceeding. This gives you a clear basis for deciding whether the offer and buyer checks meet your requirements.