

What types of properties are most suitable for a cash sale in the UK?
Properties most suited to a cash sale in the UK are often inherited or probate homes, rundown properties needing substantial work, and houses affected by legal or ownership complications. A cash buyer may also be suitable where avoiding estate-agent marketing and a traditional sale process is important.
The properties most suitable for a cash sale are usually those that may be difficult, slow or impractical to sell through a mortgage-dependent transaction. This includes homes with leasehold, construction, occupancy or title issues that could make mainstream lending less straightforward, as well as properties where the owner values a direct sale over attracting buyers through the open market.
Unmortgageable or hard-to-mortgage homes
Some properties are difficult for buyers to finance with a conventional mortgage. Reasons may include significant structural defects, certain forms of non-standard construction, concerns about the property’s condition, or restrictions affecting its use. A cash purchaser does not need a mortgage lender to approve the property, so these issues may be less of an obstacle to agreeing a sale. They do not, however, remove the need for appropriate surveys, title checks and legal advice.
Properties with unusual construction or design
Homes built using uncommon materials or methods can have a narrower pool of mortgage-funded buyers. The same can apply to properties with unusual layouts, extensive extensions, converted buildings or arrangements that do not fit standard residential lending criteria. A cash sale may be worth considering where a seller wants to avoid relying on a buyer whose lender later declines the property.
Tenanted properties
A house or flat with tenants can be suitable for a cash sale, particularly where the owner wants to sell with the tenancy in place rather than market the property as vacant. The buyer will need clear information about the tenancy agreement, rent, deposit protection, licensing and any notices served. If vacant possession is required, the legal position and the timing of any possession process should be established before a sale is agreed. A seller should not assume that a cash transaction overrides tenants’ rights.
Leasehold flats and properties with management issues
Leasehold homes can attract additional questions about the remaining lease term, service charges, ground rent, major works, building insurance and permissions for alterations. A cash buyer may still consider such a property, but the lease and management information will need careful review. Arrears, disputes with a managing agent or an incomplete information pack can affect the assessment of value and the ability to proceed.
Homes with title or registration matters
Properties may be suitable for a cash sale where the ownership record needs clarification. Examples include missing deeds, discrepancies between the register and the physical property, unregistered land, boundary disagreements, rights of way or restrictions placed on the title. These matters are not automatically deal-breakers, but they should be disclosed at the outset so that a conveyancer can identify what evidence or corrective work is required.
Properties affected by occupancy or ownership arrangements
A home may require additional consideration where more than one person has an interest in it, where an owner is absent, or where an occupier is not named on the title. All relevant parties may need to provide information, sign documents or obtain independent legal advice. A cash buyer can sometimes offer a more direct route for assessing these circumstances, but the sale cannot properly complete until the ownership and occupation position is addressed.
Houses in a chain or with a difficult onward purchase
A cash sale may be appropriate where the seller wants to reduce dependence on a buyer’s mortgage approval or an extended chain. This can be relevant to owners who have already found another property, need greater certainty before making a move, or do not want their sale to depend on several linked transactions. The existence of cash funding does not by itself remove conveyancing, searches or other completion requirements, so the whole chain position should still be discussed with the solicitor.
Properties requiring a flexible assessment
Some homes do not fit neatly into standard estate-agent pricing because their value depends on factors such as potential refurbishment, a large plot, development possibilities or a specialist buyer. A cash purchaser may assess the property based on its condition, title and likely resale or improvement requirements rather than relying solely on comparisons with fully finished homes. Any proposed development value should be treated cautiously and checked against planning policy, existing permissions and restrictions.
Suitability is not determined by property type alone. The location, ownership position, condition, title, occupancy arrangements and the seller’s preferred timescale all affect whether a cash sale is practical and what price may be offered. Before accepting an offer, the seller should request its terms in writing, confirm whether deductions or fees apply, and ask a conveyancer to review the legal paperwork. This helps distinguish a genuinely suitable cash sale from an arrangement that merely appears simpler at the outset.
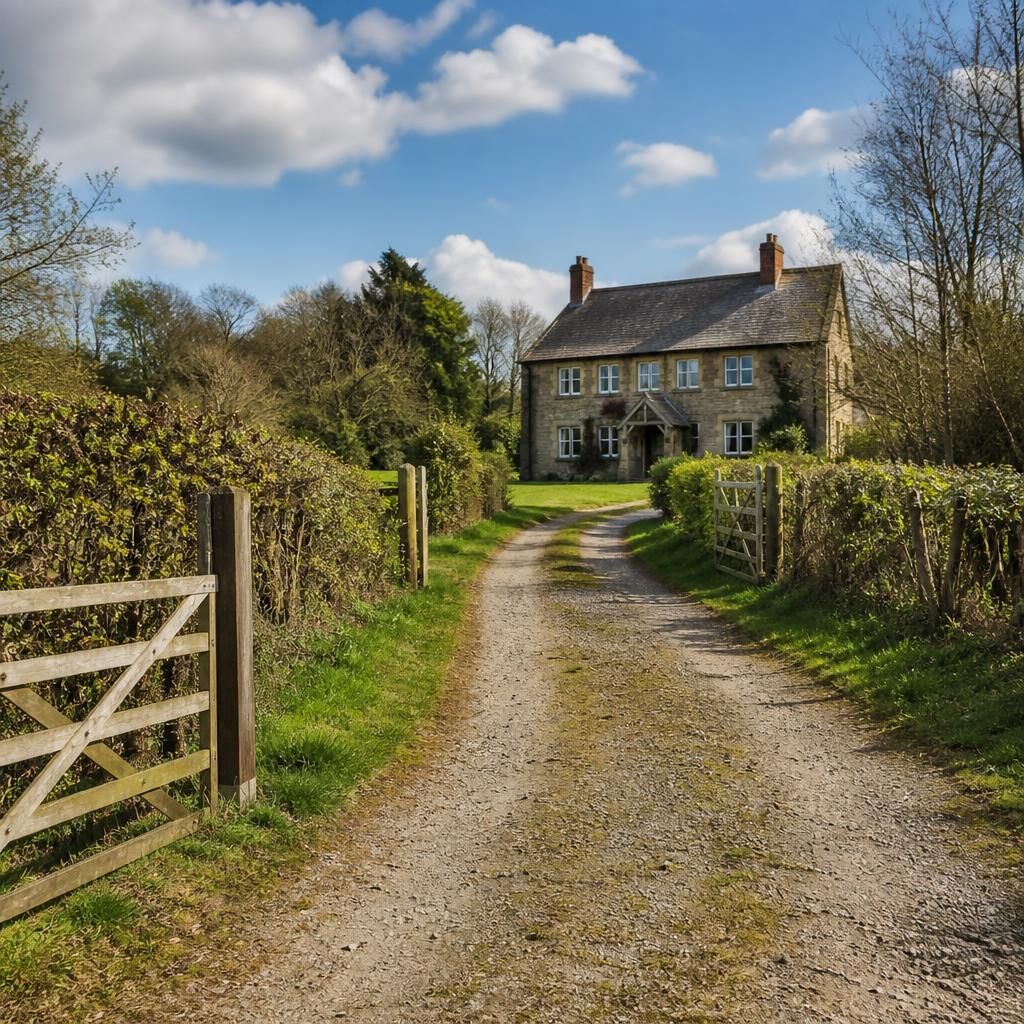
Rural and semi-rural properties with private access or non-standard services can sometimes be suitable for a cash sale. Examples include homes reached by a private road, properties using septic tanks or private water supplies, and houses with limited mains connectivity. These features may require additional checks and can narrow the pool of conventional buyers.
The seller should provide details of access rights, maintenance responsibilities, drainage arrangements, water testing, utility connections and any shared-cost agreements. A cash buyer may assess the property without relying on a standard mortgage valuation, but these arrangements still affect value, insurance and resale prospects. The conveyancer should verify the relevant rights, consents and maintenance obligations before contracts are exchanged.
Discuss Your Property’s Suitability for a Cash Sale
If you are unsure whether your property’s condition, ownership position or legal circumstances are suitable for a cash sale, provide the relevant details for an initial assessment. Review any proposed terms with an independent conveyancer before deciding whether to proceed.