

What are the benefits of selling my property as-is for cash?
Selling your property as-is for cash can reduce the need for repairs, decorating and extensive preparation before marketing. It may also simplify the sale by avoiding some traditional selling steps, which can be useful when you need a more straightforward route to completion.
Selling a property as-is for cash can provide greater control, a more predictable transaction and a practical route for owners whose circumstances or property condition make a conventional sale unsuitable. The main benefit is that the sale is based on the property in its present state, with the cash buyer assessing its condition and circumstances before making an offer.
Greater certainty about the type of buyer
A cash purchase is not normally dependent on the buyer securing a mortgage. This can remove one source of uncertainty from the transaction, particularly where a lender might question the property’s condition, construction, occupancy or legal background. It is still important to verify that the buyer has the funds available and to ensure that the solicitor completes the appropriate checks.
Less exposure to property-chain problems
Traditional transactions can be affected by a chain of linked purchases. A cash buyer may be able to purchase without relying on another sale completing first, which can reduce the risk of delays caused by unrelated buyers or sellers. This does not eliminate every possible delay: conveyancing, searches, title issues and mortgage redemption still need to be dealt with properly.
Useful for properties that may have a limited market
An as-is cash sale can be suitable where a property needs substantial work, has been empty, is occupied, has unusual features or presents legal and practical complications. Such properties may attract fewer conventional buyers, especially when they are seeking a home that is ready to occupy or finance through a mortgage. A buyer specialising in cash purchases may instead assess the opportunity based on the property and its circumstances as they stand.
More flexibility around personal circumstances
A cash sale may be considered by owners dealing with probate, divorce, mortgage arrears or a potential repossession. In these situations, the value of a direct sale is not limited to the property itself. It may help the owner understand the available options, establish what needs to be settled from the sale proceeds and discuss a transaction that reflects their legal and financial position.
However, a sale does not automatically resolve debts or legal obligations. Any mortgage, secured loan, beneficial interest, probate requirement or restriction on the title must be identified and handled through the conveyancing process. Where there is a risk of repossession, independent legal or debt advice should be obtained before agreeing to sell.
Potentially lower transaction costs and disruption
A direct cash sale may reduce the number of third parties involved and can avoid some costs associated with preparing and marketing a property through an estate agent. The exact position depends on the agreement, so check whether any fees, deductions or costs are taken from the proposed offer. You should also account for solicitor’s fees, mortgage repayment charges, removal costs and any tax consequences that apply to your circumstances.
Greater privacy and control
Some sellers prefer not to have photographs, particulars and viewing appointments associated with their property. A direct sale can offer a more private process, although the buyer and conveyancers will still need accurate information and access for valuation, inspections or legal enquiries. You should agree clearly who can access the property and how personal belongings or tenant arrangements will be dealt with.
Important limitations to weigh up
The benefits of an as-is cash sale should be considered alongside the likely offer price. A cash buyer takes on the cost, risk and responsibility of dealing with the property’s condition, so the offer may be below the price that could be achieved through a fully marketed sale. Compare the net amount you would receive, rather than looking only at the headline figure, and ask for the basis of the valuation in writing.
- Confirm the buyer’s identity, funding and buying structure.
- Use an independent conveyancer who acts for you.
- Check the offer for fees, deductions, conditions and proposed timescales.
- Provide accurate information about ownership, occupants, works, leases and debts secured against the property.
- Do not rely on verbal assurances where an important term can be included in the written agreement.
Overall, selling as-is for cash can be beneficial when control, flexibility and transaction certainty matter more than achieving the highest possible open-market price. The right option depends on the property’s condition, your financial position and whether the buyer can demonstrate a transparent, properly documented process.
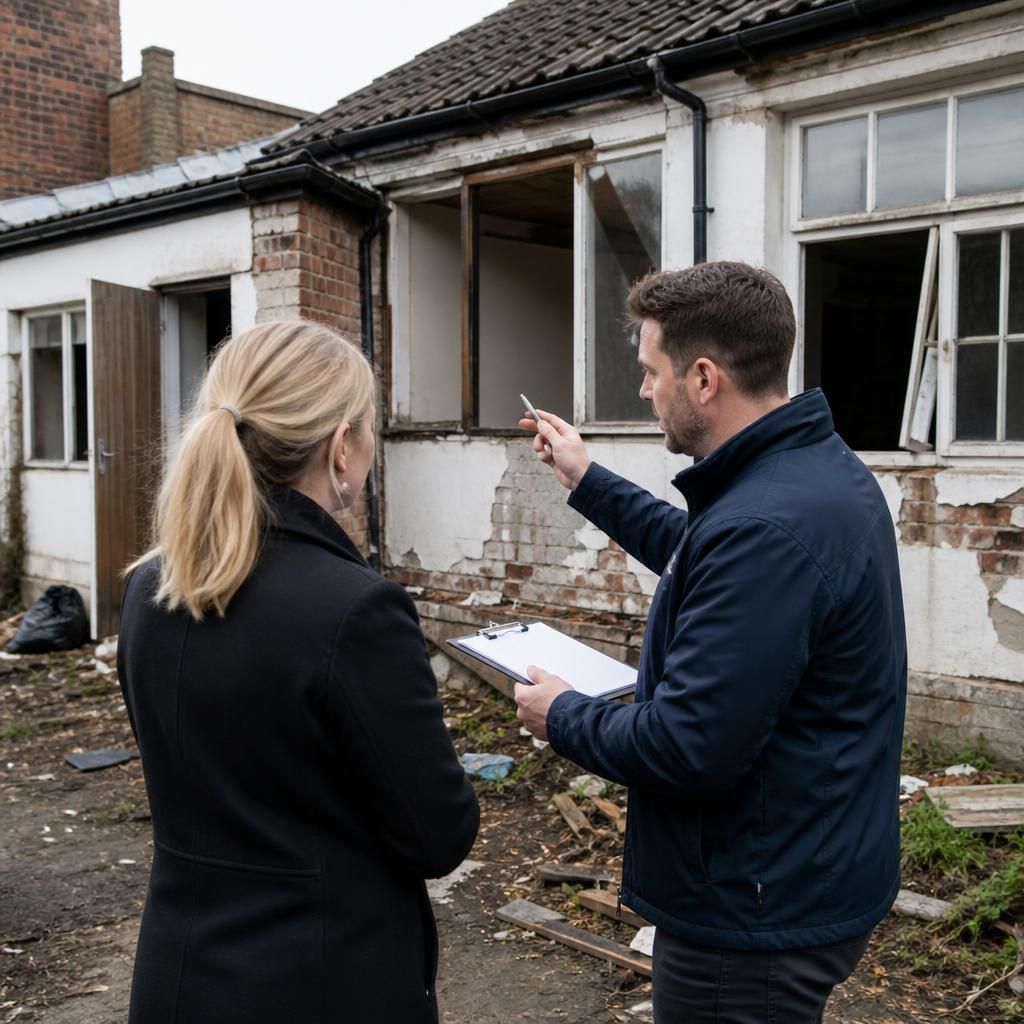
An as-is cash sale can make responsibility for the property’s condition clearer. The buyer assesses the building, fixtures and visible defects in their current state, while the seller is not normally expected to bring the property up to a market-ready standard before agreeing terms. This can reduce uncertainty over which remedial works are required before completion.
That does not remove the need for honest disclosures or legal checks. Provide accurate information about known defects, alterations, leases, occupants and title matters, and ensure the written agreement explains the property’s condition and any agreed arrangements. A solicitor can then confirm what the buyer has accepted and identify issues that still need to be resolved.