

What are the potential risks to consider when opting for a no estate agent cash sale?
A no estate agent cash sale can involve a lower offer than the price achieved through open-market marketing, unclear fees, unreliable buyers, or contractual terms that limit your options. Before proceeding, verify the buyer’s identity and funding, obtain independent legal advice, check every cost and condition, and avoid signing documents you do not fully understand.
The main risks in a no estate agent cash sale are reduced oversight, incomplete information, avoidable legal or financial liabilities, and misunderstandings about how a cash transaction works. Removing an estate agent does not remove the need for valuation, conveyancing, property disclosures, identity checks or a properly documented contract.
The buyer may not be ready to complete. A buyer can describe an offer as “cash” while still needing to sell another property, obtain approval from a third party or resolve a source-of-funds issue. Even where no mortgage is involved, the transaction remains dependent on satisfactory conveyancing, proof of funds and the buyer’s ability to sign and complete the contract. Ask your solicitor to establish whether the buyer is purchasing personally or through a company and whether the funds are immediately available for this specific purchase.
The agreed price may not be the amount you finally receive. Deductions can arise from mortgage redemption charges, secured loans, arrears, legal fees, repair agreements or other liabilities recorded against the property. An offer should therefore be assessed against a written completion statement, not just the headline figure. Request a clear list of proposed deductions and ask your solicitor to confirm which costs you are responsible for before accepting the terms.
Pressure can lead to poor decisions. A seller dealing with probate, separation, arrears or a threatened repossession may feel unable to question the paperwork. This can result in accepting a restrictive timetable, overlooking an important clause or agreeing to leave fixtures, possessions or remedial work without defining what is included. Take time to read the offer, contract and any side agreement, and obtain advice from a solicitor who acts for you rather than for the buyer.
Property information must still be accurate. Selling without an agent does not remove the risk of a claim arising from misleading answers or concealed problems. Issues may include boundary disputes, rights of way, planning breaches, building regulation matters, Japanese knotweed, subsidence, flooding history, lease restrictions or disputes with neighbours. Complete the relevant property information forms carefully, keep supporting documents, and disclose known issues rather than relying on the buyer’s inspection to uncover them.
Title or ownership problems can delay completion. Missing deeds, inconsistent names, unregistered land, restrictions on the title and unresolved probate can prevent a buyer from obtaining good title. Divorce or separation may also mean that more than one person must consent to the sale. Identify every legal owner and provide the conveyancer with probate documents, trust information, marriage or separation documentation and any details of charges affecting the property as early as possible.
There may be tax and debt consequences. The sale itself can affect capital gains tax, inheritance tax, means-tested benefits, insolvency arrangements or the treatment of money received during divorce proceedings. These consequences depend on the seller’s circumstances and the property’s history. A conveyancer can deal with the transaction, but a tax adviser or insolvency professional may also be needed. Do not assume that a cash sale is automatically exempt from tax or that sale proceeds can be distributed without checking existing obligations.
Payment and bank-detail fraud are separate risks. Criminals can intercept emails, impersonate a solicitor or send altered account details. Confirm payment instructions using a trusted telephone number obtained independently, particularly before transferring personal information or relying on a message about completion funds. Never treat an email alone as proof that bank details have changed.
The lack of an agent transfers practical work to the seller. You may need to organise access, answer questions, assemble certificates, negotiate inclusions and keep communication consistent between the buyer, solicitor, lender and other parties. Gaps in information can create delay or disagreement. A written record of the agreed price, included items, vacant-possession requirements, target dates and responsibility for any works helps prevent later disputes.
The contract controls your ability to withdraw. Before exchange of contracts, either party may generally be able to change position, subject to the terms already agreed. After exchange, withdrawing can expose a seller to contractual consequences. The precise position depends on the contract and jurisdiction, so do not assume that an informal agreement, reservation document or deposit arrangement gives you the same protection as a properly reviewed sale contract.
Risk can be reduced by using an independent conveyancer, obtaining a realistic valuation, checking the title and ownership position, preparing complete property information, confirming all deductions in writing and retaining copies of communications. If the property is leasehold, also obtain the lease, service-charge information, ground-rent details and any notices or planned major works. Sellers in Scotland, England and Wales or Northern Ireland should obtain advice relevant to the law applying to their property, because the conveyancing process and contractual rules differ.
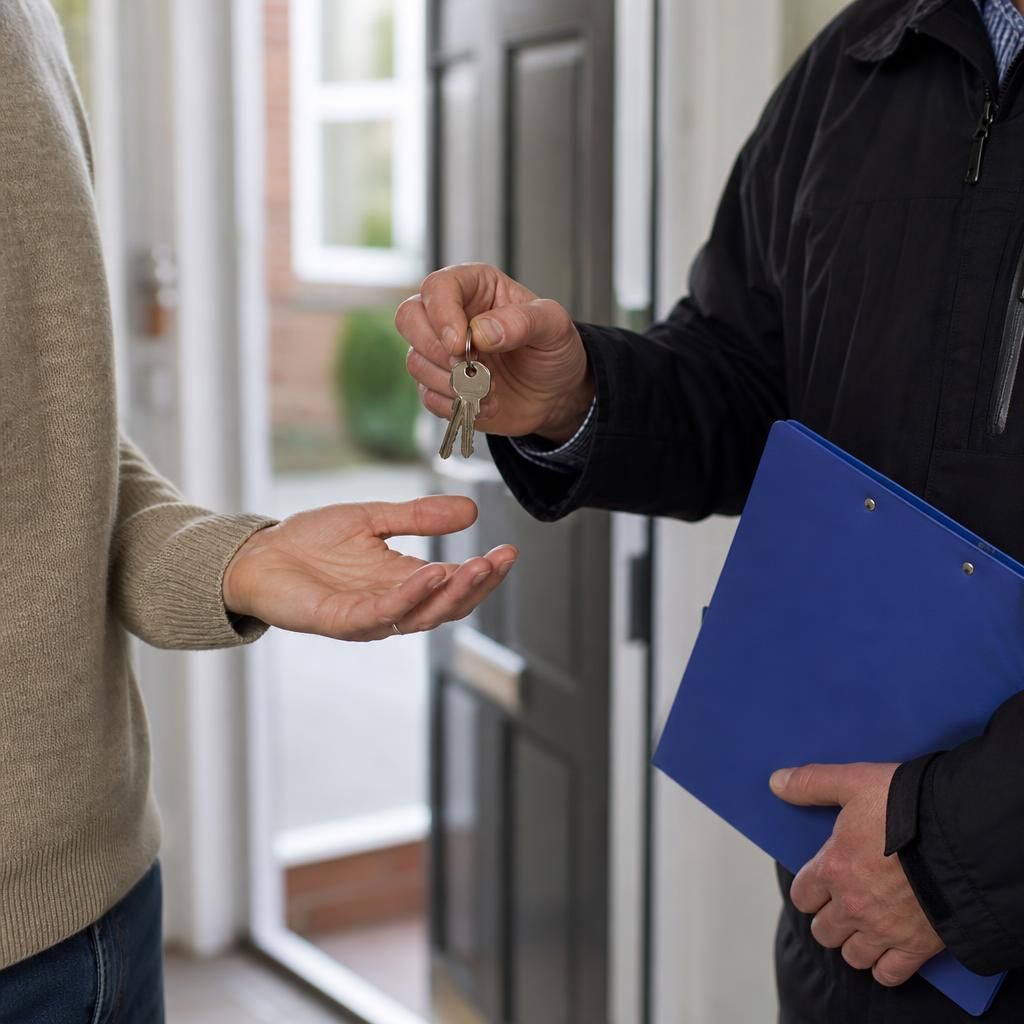
A further risk in a no estate agent cash sale is handing over control of the property before completion has legally and financially taken place. A buyer’s assurance that funds have been sent is not the same as your conveyancer confirming that cleared money has arrived and the transaction has completed.
Do not release keys, allow occupation, sign a blank transfer document or grant a broad power of attorney unless your independent conveyancer has explained the arrangement and confirmed that it is required. Follow written instructions about vacant possession, meter readings and the removal of belongings, and keep evidence of the property’s condition at handover. This helps prevent disputes if completion is delayed, payment is questioned or the buyer later claims that access was granted under different terms.