

What is the process for selling a house in probate?
Selling a house in probate usually involves valuing the property, obtaining the Grant of Probate or Letters of Administration, agreeing a sale, and completing the transaction through the estate’s appointed personal representative. The sale proceeds are paid into the estate and used according to the will or intestacy rules, after any outstanding property-related costs and liabilities are addressed.
The key feature of a probate sale is that the property is dealt with by the deceased person’s personal representative rather than by the beneficiaries themselves. The personal representative must establish legal authority, protect the estate’s interests, comply with the will or intestacy rules, and keep clear records of the transaction from the initial decision to sell through to completion.
1. Identify the person authorised to act
Check the will to establish who was appointed as executor. If there is no valid will, the person applying to administer the estate is usually an administrator. Executors and administrators are collectively known as personal representatives. Where there is more than one, all relevant representatives may need to agree to the sale and sign the required documents.
A beneficiary does not automatically have authority to instruct an agent, accept an offer or sign a contract simply because they are due to inherit the property. If the wrong person gives instructions, the sale can be delayed or challenged.
2. Establish the estate’s legal authority
In England and Wales, the usual authority is a Grant of Probate where there is a will, or Letters of Administration where there is no will or the named executors cannot act. Northern Ireland uses its own grant terminology and procedure. In Scotland, the equivalent authority is generally confirmation rather than a grant of probate.
The application normally requires information about the estate, the death, the will where applicable, and the value of the assets and liabilities. Estate information should be checked carefully before it is submitted, because inaccurate valuations or incomplete details can create further work and affect tax reporting.
There are circumstances in which a property may be marketed before the grant is issued, but the personal representative must ensure that the proposed contract and completion arrangements are legally workable. A conveyancer should explain whether a sale can proceed at that stage and whether any special wording or conditions are needed.
3. Secure and inspect the property
Before marketing, arrange appropriate insurance, secure the building and deal with urgent maintenance. Utilities, council tax, alarms, gardens and standing water should be considered, particularly if the property is vacant. Redirecting post and keeping evidence of inspections can help protect the estate and identify important correspondence.
Inspect the title documents and the physical condition of the house. Check for extensions, alterations, access arrangements, lease terms, restrictive covenants, planning matters and any known disputes. If the property is leasehold, obtain information about the remaining term, service charges, ground rent and the managing agent’s requirements.
4. Obtain a suitable valuation
A valuation should reflect the property’s condition, tenure, location and likely market appeal. The personal representative should retain the valuation evidence because it may be relevant to inheritance tax, capital gains tax and the estate accounts. If the property is sold for materially more or less than an earlier valuation, the reason should be recorded.
Professional advice is particularly useful where the house needs significant work, has an unusual title, is occupied, contains valuable contents or is subject to a dispute. The best sale route is not always the one with the highest headline price if substantial costs, delay or transaction risk would reduce the estate’s net return.
5. Choose how to market the property
The personal representative can usually choose between a conventional open-market sale, an auction, or a direct sale to a cash property buyer. The decision should take account of the property’s condition, the desired degree of certainty, the likely timescale, marketing and legal costs, and whether the estate needs a sale with fewer property-related steps.
Any proposed offer should be assessed on more than price. Check whether the buyer has funding in place, whether the offer is conditional, whether the buyer is in a chain, and whether they can meet the estate’s preferred timetable. A direct cash offer can be an option for a house requiring repairs or where the personal representative wants to avoid preparing it for wider marketing, but the written terms and deductions should be reviewed carefully before acceptance.
6. Instruct a conveyancer with probate experience
The conveyancer checks the title, prepares the contract pack, deals with property information forms and responds to enquiries. Probate transactions may require additional documents, including the death certificate, the grant or confirmation, the will, evidence of the personal representative’s identity and authority, and information about the estate’s ownership.
The conveyancer may also need to address missing deeds, unregistered land, absent beneficiaries, restrictions on the title, occupiers who need to leave, or a mortgage secured against the property. If the deceased owned the house jointly, the legal position depends on how it was owned. The conveyancer should confirm whether the property forms part of the estate and who must sign the transfer.
7. Accept the offer and exchange contracts
Accepting an offer is not normally the same as entering into a binding sale. The buyer and seller become legally committed when contracts are exchanged. Before exchange, the buyer may raise enquiries, arrange a survey and review the title. The personal representative should not distribute sale proceeds or make irreversible commitments on the assumption that an accepted offer will definitely complete.
Before exchange, confirm the agreed price, fixtures and contents, completion date, vacant possession arrangements and any special conditions. If the property is occupied, the personal representative must deal properly with the occupier’s rights and cannot assume that the house can simply be handed over empty.
8. Complete the transaction
On completion, the buyer’s funds are transferred through the conveyancers. The legal transfer is completed, keys are released in accordance with the contract and any mortgage or other registered charge is paid from the proceeds. The personal representative should keep the completion statement, transfer documents, invoices and evidence of payments.
Sale proceeds belong to the estate, not automatically to the person who handled the sale. The conveyancer’s fees, estate agent’s fees, mortgage redemption, necessary repairs and other authorised expenses are deducted or paid from the estate as appropriate.
9. Deal with the proceeds and close the estate
After completion, the personal representative should update the estate accounts, settle outstanding liabilities and address any tax obligations. The remaining funds are distributed in line with the will or, where there is no valid will, the applicable intestacy rules. Beneficiaries may need to wait until debts, claims and tax matters have been considered.
Keep a complete file containing the valuation, marketing or offer documents, correspondence, contract, completion statement, invoices and distribution records. Good records help demonstrate that the property was sold properly and that the estate was administered fairly.
Because probate sales combine property law with estate administration, professional advice is sensible where authority is disputed, the will is unclear, the property is jointly owned, there are vulnerable or missing beneficiaries, or the estate cannot meet its liabilities. A cash buyer may be considered as one route within this process, but the personal representative should compare the full written offer, legal conditions and net proceeds with other available sale options before proceeding.
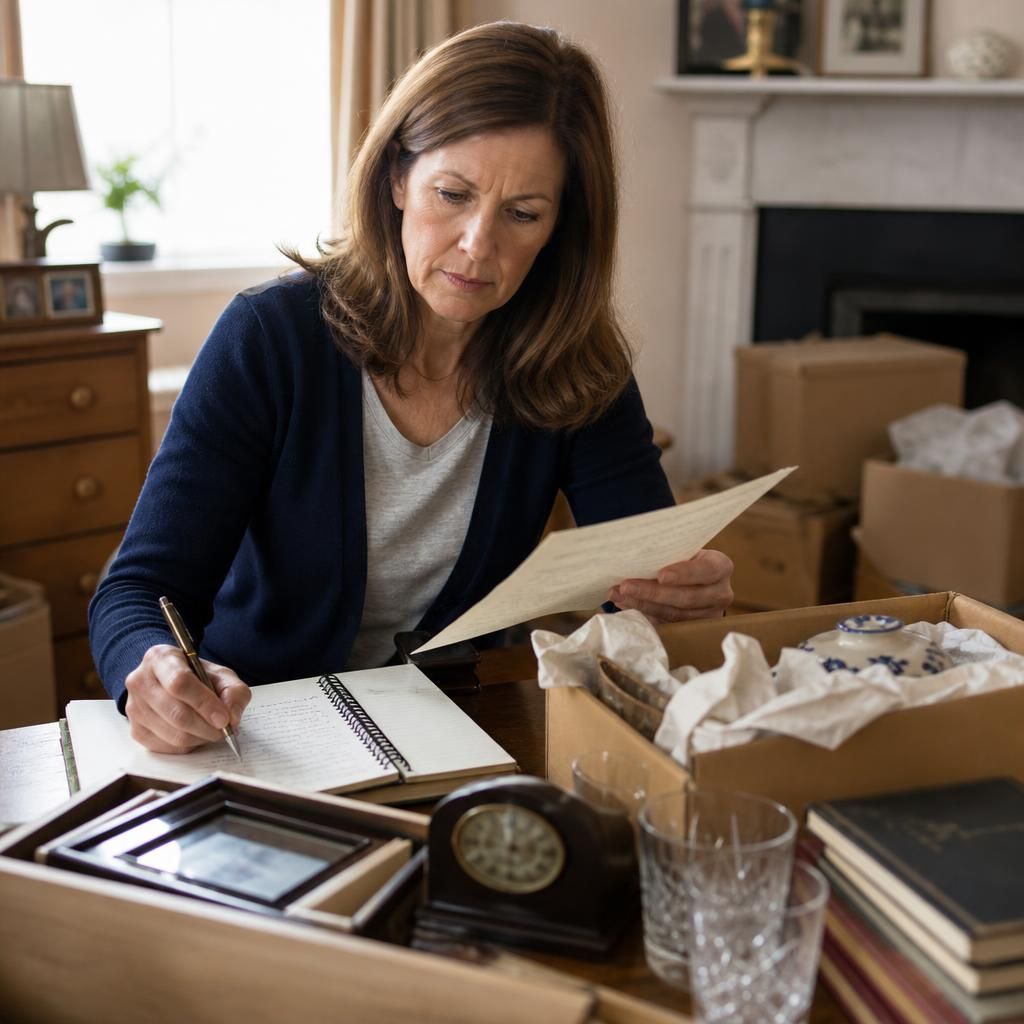
Before the property is marketed, the personal representative should agree how the deceased’s belongings will be handled. Create an inventory, identify items mentioned in the will, and separate personal possessions that beneficiaries are entitled to receive from fixtures and fittings included in the sale. Valuable items may need independent valuations, while unwanted contents may require clearance before viewings or completion.
Keep written records of decisions about the contents, including who collected items and any clearance or storage costs paid from the estate. This reduces the risk of disagreements between beneficiaries and helps the conveyancer confirm exactly what will remain at the property when the sale completes.