

What steps can I take to ensure a smooth and efficient house sale process during my divorce?
To keep a house sale during divorce smooth and efficient, agree the sale terms with your former partner, obtain independent legal and financial advice, prepare the property and paperwork, and choose a suitable selling route. Keep decisions documented, coordinate with your conveyancer and mortgage provider, and confirm how the net proceeds will be divided before completion.
A smooth house sale during divorce depends on controlling four areas at the same time: authority to sell, financial information, transaction administration and communication. Create a written plan with clear decision points, appoint the appropriate professionals, and avoid committing to a sale until ownership, mortgage and proceeds have been properly checked.
1. Confirm who has authority to sell. Check the title register to establish whether the property is owned jointly or by one person. Joint owners will usually both need to participate in the sale, even where one spouse has moved out. A solicitor should also check for restrictions on the title, a matrimonial home rights notice, trust arrangements, an existing court order or any other issue that could affect the transaction.
If the divorce or financial settlement is already before the court, the proposed sale may need to be consistent with an order or agreed settlement. Do not assume that a separation agreement, informal promise or message between former partners is sufficient authority for the conveyancer to proceed. Ask the solicitor to confirm what signatures, consents or documents are required before accepting an offer.
2. Establish the financial position before selecting a buyer. Obtain an up-to-date mortgage redemption statement, including any early repayment charge or administration fee that may apply. Check whether there are second charges, secured loans, equity-release arrangements, arrears or other deductions registered against the property. The sale price alone does not show what either party will receive.
Prepare a completion statement showing the expected sale price, estate agency or buying costs, legal fees, mortgage redemption, secured debts and any agreed adjustments. If the property is leasehold, include likely service-charge, ground-rent and management-pack charges. This gives both parties a realistic view of the net proceeds and helps identify whether the proposed sale price is sufficient to clear the borrowing.
3. Use a defensible valuation. Obtain evidence for the asking price or proposed sale price rather than relying on an informal estimate. This could include written valuations from property professionals and recent comparable sales. The valuation should reflect the property’s condition, tenure, location and any restrictions affecting its use.
Where the parties disagree about value, an independent valuation can provide a neutral reference point. If one person believes the price is too low or the other believes it is too high, record the evidence considered and ask the solicitors how the dispute should be handled. Selling below market value without proper agreement can create problems in the financial settlement and may expose the transaction to challenge.
4. Decide how offers will be assessed. Agree in advance how offers will be communicated, what information must accompany an offer and who has authority to accept it. A higher offer is not necessarily the strongest option if the buyer has a related sale, has not arranged funding or is seeking extensive conditions.
Consider the buyer’s funding, proposed timescale, chain position and willingness to proceed on the property’s actual legal and physical terms. Keep a written record of offers received and the reasons for accepting or rejecting them. If using a cash-buying company, ask how the proposed price was reached, whether the offer is subject to further inspection or valuation, and whether any fees or deductions apply. Compare the certainty and terms of the proposal with other available routes, not just the headline figure.
5. Keep communication structured. Divorce can make direct negotiations difficult, so establish one reliable channel for transaction updates. This might be a shared email thread, communication through the solicitors or instructions routed through one agreed contact. Important decisions should be confirmed in writing, including acceptance of an offer, changes to the completion date, arrangements for vacant possession and approval of deductions.
Do not allow one party to give the buyer, estate agent or conveyancer instructions that contradict the other party’s position. If communication has broken down, tell the conveyancer promptly. They can explain what requires joint authority and may be able to manage communications without either party making unilateral commitments.
6. Prepare for conveyancing without avoidable delays. Return the property information forms accurately and disclose known matters such as alterations, disputes, boundaries, notices, guarantees, flooding history or disputes with neighbours. Gather planning permissions, building-regulation certificates, guarantees, lease documents and information about works before they are requested. Missing or inconsistent answers can lead to additional enquiries and delay exchange of contracts.
For a leasehold property, identify the freeholder or managing agent and check what information is needed for the management pack. Confirm whether there are outstanding service charges, planned major works or restrictions on assignment. For a property with physical or legal complexities, disclose them early so the buyer and conveyancer can assess the position rather than discovering an issue late in the transaction.
7. Coordinate the mortgage and moving arrangements. Tell the mortgage provider that the property is being sold and ask how redemption will be handled. The lender normally needs the conveyancer’s completion statement and must receive the redemption funds before its charge can be removed. If the sale price may not cover the mortgage and other secured debts, obtain specialist advice before agreeing a completion date.
Agree what will happen to furniture, personal belongings, keys, post and utilities. Confirm whether the buyer expects vacant possession and remove items that are not included in the contract. These practical arrangements should be settled before completion, particularly where one former partner no longer lives at the property.
8. Treat exchange and completion as separate milestones. Until contracts are exchanged, the sale is generally not legally binding and the buyer may withdraw or seek changes. Do not make irreversible financial arrangements solely because an offer has been accepted. Before exchange, check the contract price, completion date, fixtures and fittings, vacant-possession terms and any special conditions with the conveyancer.
After exchange, both parties should understand the consequences of failing to complete. On completion, the conveyancer receives the purchase funds, repays the mortgage and other agreed liabilities, pays authorised costs and transfers the remaining balance in accordance with the written instructions or applicable court order. Ask for a final completion statement and retain it with the sale documents.
9. Keep the divorce settlement separate from assumptions about the sale. The division of equity may not automatically be an equal split. It can depend on the financial order, contributions, other assets and liabilities, pension arrangements, housing needs and the advice given by the parties’ solicitors. Do not distribute the proceeds informally or release one party’s share until the solicitors have confirmed the correct treatment.
A practical checklist should therefore include confirmed authority to sell, verified mortgage and title information, an evidence-based valuation, written instructions on offers, an agreed communication method, completed conveyancing forms, a checked completion statement and clear directions for the net proceeds. Using a conveyancer experienced in transactions involving separation or divorce can help keep the sale process aligned with both the property transfer and the wider financial settlement.
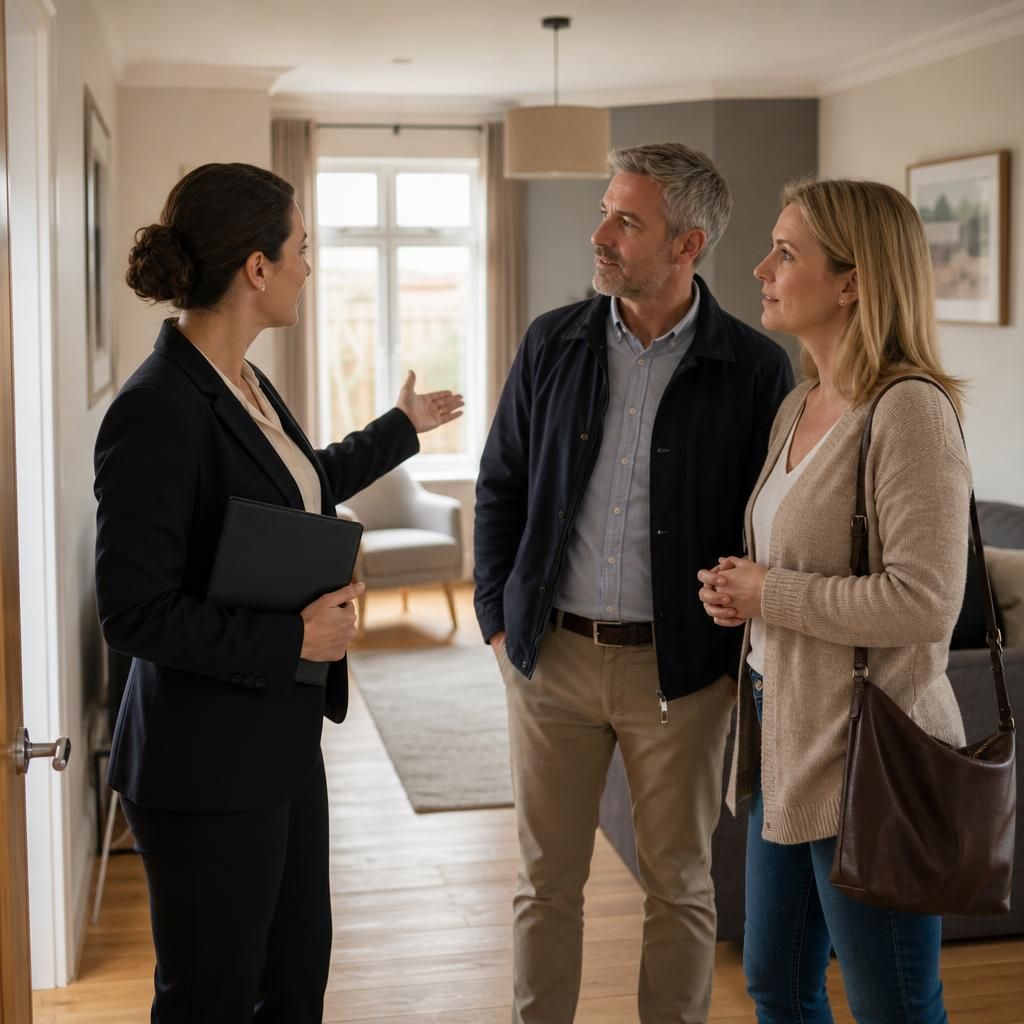
Agreeing a clear access plan for viewings, inspections and surveys can prevent avoidable disputes during a divorce-related house sale. Decide in writing when access is permitted, who will arrange appointments, how much notice is required and whether the former partners must be informed before anyone enters the property.
Keep access arrangements separate from disagreements about the divorce. Use one agreed contact for the estate agent, buyer or surveyor, and record cancellations or changes. Secure personal documents, valuables and confidential paperwork before visits, and make arrangements for children, pets or occupants where necessary. A consistent process helps the property remain available for legitimate appointments without either party feeling that access is being used to exert pressure.