

How do cash home buyers assess property value in a fast sale?
Cash home buyers typically assess a property using its location, size, condition, recent comparable sales and any legal or title issues. They then account for necessary repairs, buying costs and the risks of a quick transaction before making an offer.
A cash home buyer assesses value by combining an initial desktop review with property-specific checks, then adjusting the result to reflect the condition of the sale and the buyer’s intended resale or investment strategy. The figure offered is therefore not always the same as an estate agent’s marketing valuation or the property’s theoretical open-market value.
The process commonly begins with information supplied by the owner, such as the property address, tenure, number of rooms, occupancy arrangements and any known restrictions. A buyer may also check publicly available property records and planning information before deciding whether an inspection is needed. This helps identify issues that may affect the practical value of the property, including a short lease, tenancy obligations, access arrangements or alterations that require further evidence.
A valuation is then refined by examining the property itself. A viewing or survey allows the buyer to verify the information provided and distinguish between cosmetic work and defects that could affect the building’s usability or future saleability. The assessment may consider the roof, structure, damp, services, windows, heating, layout and signs of previous alterations. Where a specialist issue is suspected, the buyer may request reports or supporting documents rather than relying solely on a visual inspection.
Cash buyers also assess how the property could be used after completion. A standard family house, a property suitable for refurbishment, a multi-let opportunity and a development prospect may each be valued differently, even when they are in the same area. Factors such as planning potential, restrictions on use, rental demand and the likely type of future purchaser can influence the calculation.
The buyer normally works backwards from an estimated achievable resale or investment value. The calculation allows for the work and expenditure needed before the property can be used or resold, together with the buyer’s required return and allowance for matters that remain uncertain. This produces a purchase figure designed to be workable for the buyer rather than a headline asking price intended to attract viewings.
It is important to distinguish between the gross offer and the amount you will actually receive. Ask whether the written figure is subject to deductions, retention, outstanding charges or further inspection. Also check whether the offer assumes vacant possession, particular documents being available or completion on specific contractual terms. An offer based on clear assumptions is easier to compare with another proposal.
A reliable assessment should be supported by a clear explanation of:
- the information and documents used in reaching the figure;
- any assumptions about occupancy, tenure or planning status;
- work or specialist investigations included in the calculation;
- any proposed deductions from the stated offer; and
- the circumstances in which the figure could be reconsidered.
When comparing a cash offer with an estate agent’s valuation, remember that they serve different purposes. An agent’s figure may represent an advertised price subject to marketing, negotiations and a buyer securing finance. A cash buyer’s figure is usually based on a direct purchase with fewer stages, so the two figures should be compared on a net basis and alongside the certainty of the proposed terms.
You can test whether the assessment is reasonable by requesting the calculation in writing, asking specific questions about any deductions and obtaining independent advice where the property is unusual or the decision is financially significant. An independent valuation from a suitably qualified surveyor can provide a separate reference point. You should also read the sale agreement carefully and ask your solicitor to explain any clauses allowing the buyer to revisit the offer.
The most useful valuation is not necessarily the highest initial figure. It is the one that accurately states what is being purchased, identifies the conditions attached to it and shows what you are expected to receive at completion. Reviewing those details helps you judge whether the proposed cash price is realistic and genuinely comparable with other ways of selling.
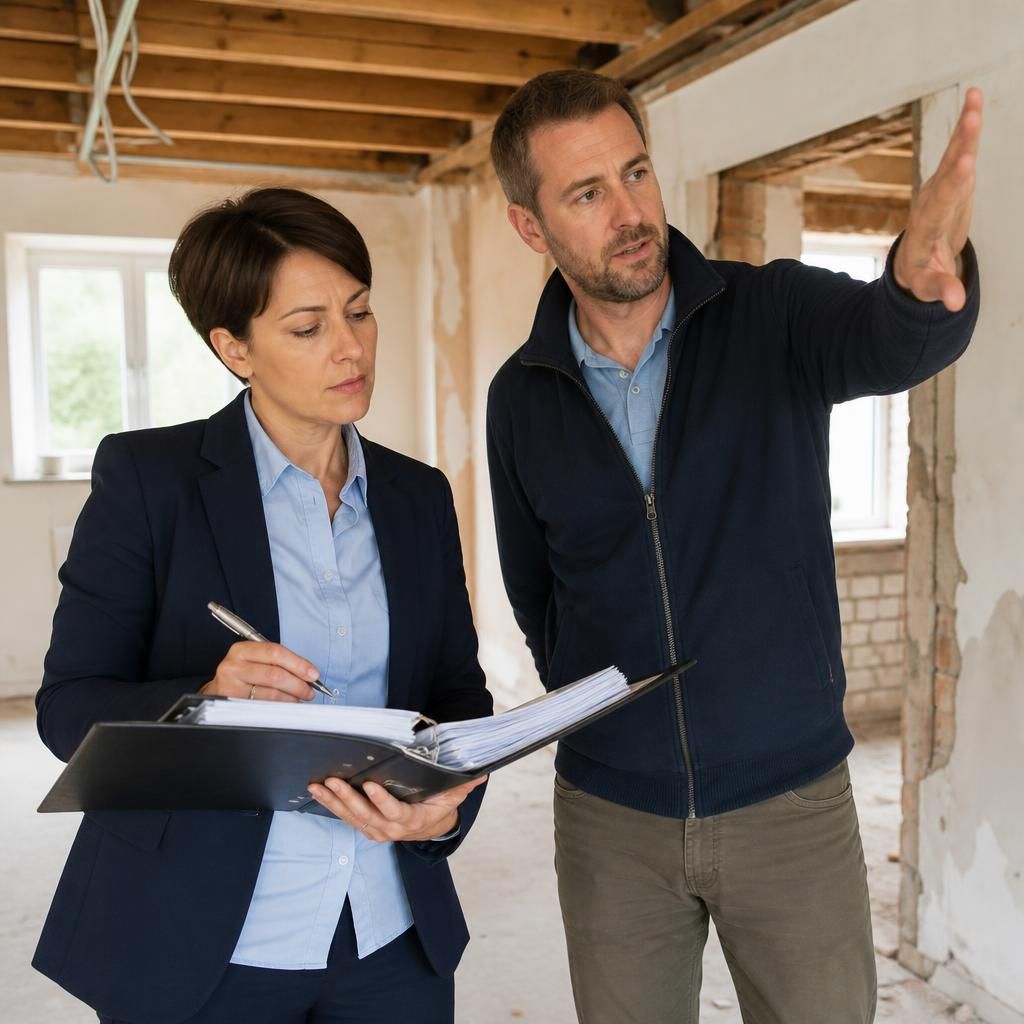
Cash buyers may assess whether a property is likely to be acceptable to a future mortgage lender, even when the buyer itself does not need finance. Features such as non-standard construction, unresolved building-control matters, a flying freehold or missing guarantees can narrow the pool of future purchasers and reduce the price that can reasonably be offered.
This part of the assessment is based on evidence rather than appearance. Building regulations certificates, warranties, planning consents and records of remedial work can help establish that alterations are properly documented. If evidence is missing, the buyer may allow for the cost and uncertainty of obtaining it, or reflect the risk that a later purchaser could face difficulty securing finance.
Request a Cash Offer Based on Your Property’s Value
If you would like your property assessed for a cash sale, provide the relevant property details and any documents that may affect its value. Review the resulting offer alongside its assumptions, deductions and contractual terms before deciding whether to proceed.