

What steps are involved in the process of selling an inherited property for cash?
Selling an inherited property for cash usually involves confirming the legal authority to sell, completing any required probate steps, gathering the property documents, obtaining a valuation, reviewing and accepting a cash offer, and completing the sale through conveyancers.
Selling an inherited property for cash is a staged legal and property transaction. The personal representative must first establish authority to deal with the estate, then prepare the property for sale, assess the offer and allow conveyancers to complete the transfer of ownership. The exact requirements can vary between England and Wales, Scotland and Northern Ireland, so the estate’s solicitor should confirm which procedure applies.
-
Identify who has authority to act. The person named as executor in the will may need a grant of probate before entering into a binding sale. Where there is no will, an administrator may need letters of administration. In Scotland, the equivalent court authority is generally confirmation. Until the appropriate authority is in place, a buyer and conveyancer may be unable to establish that the person accepting the offer can legally sell the property.
If more than one executor or administrator is appointed, all required parties may need to approve or sign documents. The position can also be more complicated where beneficiaries disagree, a beneficiary is a minor, the will is being challenged, or the estate is insolvent. Resolving those issues before accepting an offer can reduce the risk of the transaction being delayed later.
-
Secure and assess the property. An inherited home should be insured appropriately while it is unoccupied, and practical arrangements should be made for keys, post, security, heating and essential maintenance. The personal representative should check for buildings insurance conditions, outstanding utility accounts, service charges, ground rent and any urgent repairs.
It is not always necessary to carry out extensive refurbishment before approaching a cash buyer. However, known defects should be disclosed accurately. Issues such as subsidence, Japanese knotweed, structural movement, flooding, asbestos, non-standard construction or unauthorised alterations can affect the offer and the conveyancing enquiries. A clear record of known problems is preferable to leaving them for the buyer to discover during due diligence.
-
Assemble the information needed for assessment. The buyer and conveyancers will usually need the property address, title information, details of the sellers, information about the estate’s authority to sell and relevant property paperwork. Useful documents may include guarantees, planning and building regulation certificates, electrical or boiler records, lease information for a flat, details of alterations and correspondence about disputes or notices affecting the property.
Where documents are missing, this does not necessarily prevent a sale, but it may lead to additional enquiries or the need to obtain official copies, indemnity insurance or other evidence. If the property is leasehold, the lease terms, remaining term, service charge position and management information are particularly important. Any tenancy should also be identified, since vacant possession may not be available in every case.
-
Consider the property’s market position and the proposed terms. A cash buyer will normally assess the condition, title, location, occupancy and likely costs of completing the transaction. The personal representative should compare the proposed price with relevant local evidence and consider what is included, such as fixtures, fittings, furniture or remaining contents.
Price is only one part of the offer. The written terms should be checked for conditions, intended timescales, whether the buyer is purchasing as an individual or company, and whether the buyer expects vacant possession. It is sensible to ask how the buyer’s funds will be verified and whether the offer could change after a survey, valuation or legal investigation. A solicitor can help distinguish a firm offer from an initial indication that remains subject to further checks.
-
Instruct conveyancers and complete the legal checks. The seller’s conveyancer prepares the contract pack, confirms the title and checks that the estate representatives are correctly named. The buyer’s conveyancer will investigate ownership, boundaries, rights of way, restrictions, planning matters, environmental risks and other matters revealed by searches or enquiries.
The conveyancers will also check whether the property is subject to a mortgage or other charge. Any secured borrowing normally has to be redeemed from the sale proceeds, and the lender will need to provide the information required for redemption. If the property is jointly owned, subject to a trust, occupied by someone with rights to remain, or affected by a restriction on the title, specialist advice may be required before exchange.
Anti-money-laundering checks and verification of identity apply to the seller and buyer. The buyer’s conveyancer may also need evidence showing the source of funds. These checks are separate from the seller’s decision about the offer and should be completed before the parties rely on a proposed completion date.
-
Exchange contracts and complete the sale. The transaction becomes legally binding when contracts are exchanged by the conveyancers. Before exchange, the personal representative should be satisfied with the agreed price, contract terms, arrangements for clearing the property and any conditions attached to the sale. Until exchange, either party may usually withdraw, subject to the legal position and any agreement already in place.
On completion, the buyer transfers the purchase money, the seller’s conveyancer deals with repayment of any secured borrowing and the buyer receives the agreed legal right to take possession. The keys are released in accordance with the contract. The conveyancer then accounts for authorised deductions and sends the remaining proceeds to the estate or the account designated by the personal representative.
After completion, the sale should be recorded in the estate’s accounts, including the purchase price, conveyancing costs, redemption of borrowing, agreed property expenses and distributions. The personal representative may also need to update the estate’s inheritance tax and income tax records, and should obtain professional tax advice where the property increased in value after the death or the estate has other taxable liabilities. A cash sale removes the buyer’s mortgage-funding stage, but it does not remove probate, title, identity, anti-money-laundering or conveyancing requirements.
Before accepting an offer, the most useful checks are whether the seller has authority to sign, whether all relevant beneficiaries and representatives are aligned, whether the buyer’s funds have been evidenced, and whether the property’s title and condition have been disclosed accurately. Addressing those points at the outset gives the conveyancers a clearer transaction to progress and helps prevent avoidable renegotiation.
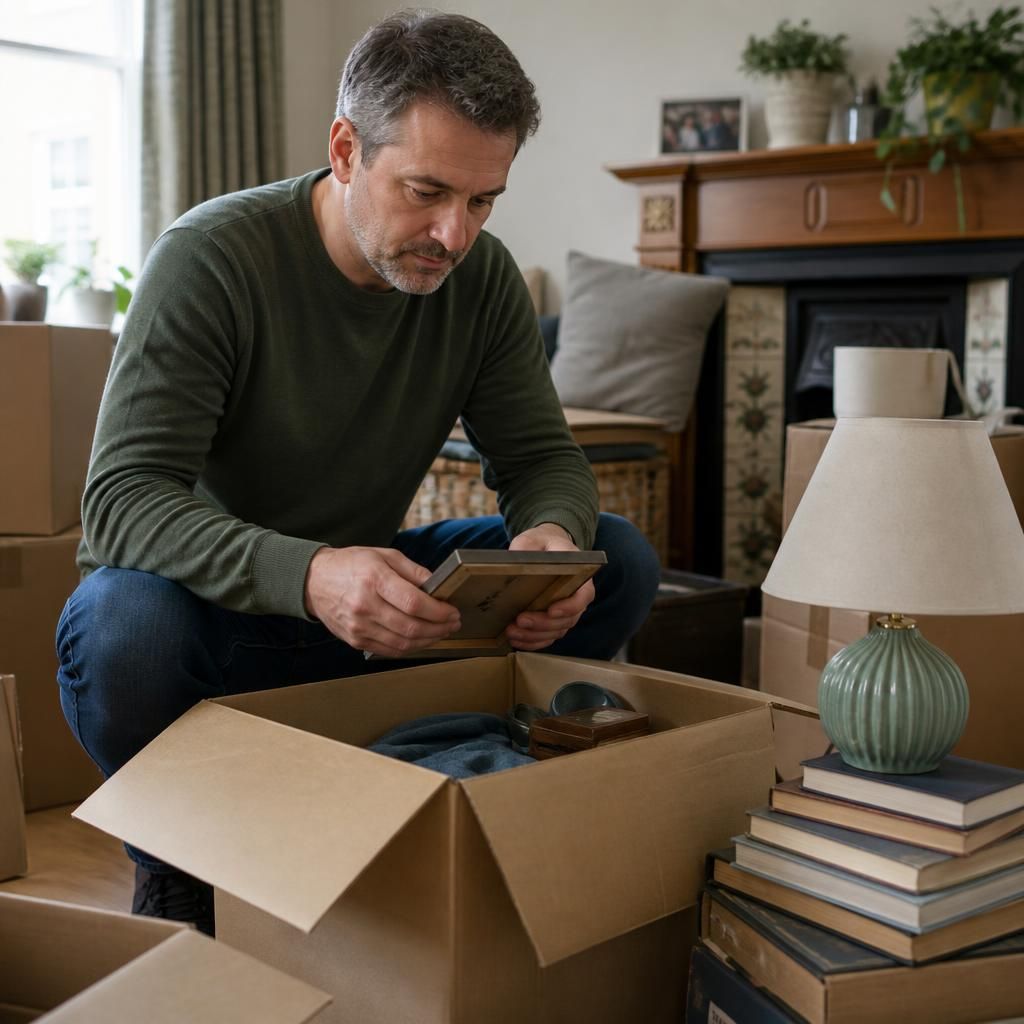
Deal with the property’s contents before completion. Furniture, vehicles, jewellery and other belongings may form part of the estate, so they should not be removed, sold or discarded without the personal representative’s authority and, where relevant, agreement between co-executors. Make an inventory of valuable items, retain receipts for clearance or storage, and check whether anything is specifically gifted under the will. The sale contract should also state clearly which fixtures, fittings and items are included, excluded or being removed.
Discuss selling your inherited property for cash
If you are considering selling an inherited property for cash, contact buyhousesfast.co.uk to discuss the property and the estate’s circumstances. Providing the address and any known legal or occupancy issues will help the initial discussion focus on your situation.