

What potential challenges could arise during the estate administration process and how do you address them?
Estate administration can be complicated by probate delays, uncertain property values, outstanding debts, disputes between beneficiaries and legal issues affecting ownership or sale. These risks are addressed by keeping accurate records, obtaining appropriate legal and tax advice, communicating clearly with beneficiaries and, where a property must be sold, considering a cash buyer alongside the traditional market.
Estate administration challenges arise when the personal representative must identify and protect the deceased’s assets, establish who is entitled to them, deal with formal legal requirements and distribute the estate correctly. The process is addressed by defining the executor’s authority, creating a complete asset and liability picture, securing property and valuables, checking ownership arrangements and obtaining specialist advice where the estate is unusual or potentially insolvent.
Establishing authority to act
A practical difficulty can arise before any assets are dealt with: the person named in the will may not be able, or willing, to act. They may have died, lost capacity, moved abroad or wish to renounce their role. Where there is no will, the appropriate administrator must be identified under the intestacy rules. The people handling the estate should also distinguish between an executor’s powers under a will and an administrator’s authority following an application for letters of administration.
This issue is addressed by checking the original will, confirming the status of every personal representative and obtaining the correct grant or other authority. Banks, registries and other organisations may not release information or transfer assets until they are satisfied that the applicant has legal authority. Acting informally or distributing items too early can create personal responsibility for the person administering the estate.
Finding assets that are not immediately visible
Some estates are difficult to value because information is spread across paper files, online accounts, pension providers, share platforms and institutions that the family does not know about. Documents may be missing, accounts may be held under a previous name, or correspondence may be sent to the deceased’s former address. Personal belongings can also have financial or sentimental importance without appearing in a formal asset register.
A structured search should cover bank and building society statements, investment records, pension and insurance paperwork, property documents, vehicle records, business interests, digital accounts and regular payments. The deceased’s accountant, financial adviser, employer or professional contacts may help identify further assets. Valuable personal items should be inventoried and kept secure while ownership and distribution are being established.
Dealing with jointly owned assets
Joint ownership does not always operate in the same way. A jointly owned property held as joint tenants will generally pass by survivorship, whereas a property held as tenants in common may form part of the estate. Bank accounts, investments and personal possessions can also be subject to specific contractual arrangements or nominations. Assuming that every joint asset automatically passes outside the estate can therefore produce an incomplete administration.
The ownership documents and terms governing each asset should be checked individually. The value passing through the estate should be separated from assets transferring by survivorship or nomination, and the relevant people should be notified. This also helps avoid distributing an asset to beneficiaries when it belongs, wholly or partly, to a surviving joint owner.
Protecting an empty or vulnerable property
A vacant property can deteriorate, attract trespassers or suffer damage before it can be transferred or sold. Insurance conditions may require regular inspections, security measures or notification that the property is unoccupied. Utility accounts, council tax, maintenance and urgent repairs also need to be dealt with, even where the property is not yet ready for a final decision.
The personal representative should arrange appropriate insurance, secure the premises, collect post, record the condition of the property and deal with essential repairs. Contents should not be removed or disposed of merely because they appear to have little value. A proper inventory and agreement between the relevant representatives can reduce later disagreement about missing or damaged items.
Managing beneficiaries who are difficult to locate
Distribution may be delayed when a beneficiary has changed address, uses a different name, lives overseas or cannot be contacted. A potential beneficiary may also have died, leaving the personal representative to establish whether their entitlement passes to someone else. Under intestacy, identifying all relatives in the correct order can require more investigation than a family initially expects.
Reasonable searches should be documented, including enquiries with relatives, examination of available records and use of a tracing service where appropriate. If uncertainty remains, legal advice can help determine whether distribution is safe or whether protective steps are needed. Payments should not be made simply to the most accessible beneficiaries while another person’s entitlement remains unresolved.
Handling an estate that may be insolvent
An estate is potentially insolvent when its liabilities exceed the value of its assets. This changes the order in which debts and expenses should be handled. Beneficiaries are not normally entitled to receive distributions until the estate’s position has been established, and personal representatives can face personal exposure if they pay the wrong parties or distribute assets prematurely.
All known creditors should be identified, including secured lenders, utility providers, care-related charges, professional fees and ongoing property costs. The assets and liabilities should then be assessed under the applicable rules, with specialist insolvency advice obtained where the position is unclear. Beneficiaries should be told when the estate cannot safely be distributed rather than being given an assumed payment date.
Preventing fraud and unauthorised transactions
Probate-related fraud can involve forged wills, false claims to be a beneficiary, misuse of the deceased’s bank accounts or attempts to redirect sale proceeds. Digital accounts and email addresses may also be vulnerable if passwords or devices were not secured. These risks are greater where several people have access to documents or where institutions rely on instructions sent electronically.
Original documents should be stored securely, identity checks should be completed before releasing information and bank details should be verified through an independent channel. The personal representative should keep a clear approval trail for payments and avoid sending confidential documents to unverified addresses. Any suspected fraud should be reported promptly to the relevant institution and addressed with legal advice.
Keeping the administration within the correct legal timetable
Different tasks can have different deadlines, including applications, notifications, claims and reporting obligations. Missing one may create additional work or affect the estate’s ability to complete a transaction. The timetable should therefore be mapped from the start, with responsibility assigned for each outstanding action.
A useful administration schedule records the task, the organisation involved, the documents required, the date submitted and any follow-up date. This is more reliable than relying on informal reminders, particularly where several personal representatives are involved. If a deadline cannot be met, the reason and proposed corrective action should be recorded and professional guidance obtained.
When professional help is appropriate
Advice is particularly important where the will is unclear, the estate includes a business or overseas asset, ownership is contested, a beneficiary lacks capacity, insolvency is possible or a personal representative has a conflict of interest. A solicitor can clarify the legal authority to act, explain the consequences of a proposed distribution and prepare the documents required by institutions and the court.
The personal representative remains responsible for providing accurate information and making decisions, but specialist support can reduce the risk of an avoidable error. Before instructing an adviser, it is sensible to confirm the scope of work, who will communicate with beneficiaries, how expenses will be approved and how progress will be reported.
Most administration problems become more manageable when authority, ownership, asset protection, beneficiary entitlement and creditor claims are dealt with in a defined order. Where a residential property forms part of the estate, its legal title, insurance, condition and ownership documents should be checked before any disposal decision is made. That approach helps the personal representative make a properly informed decision rather than treating the property as a separate issue from the wider estate.
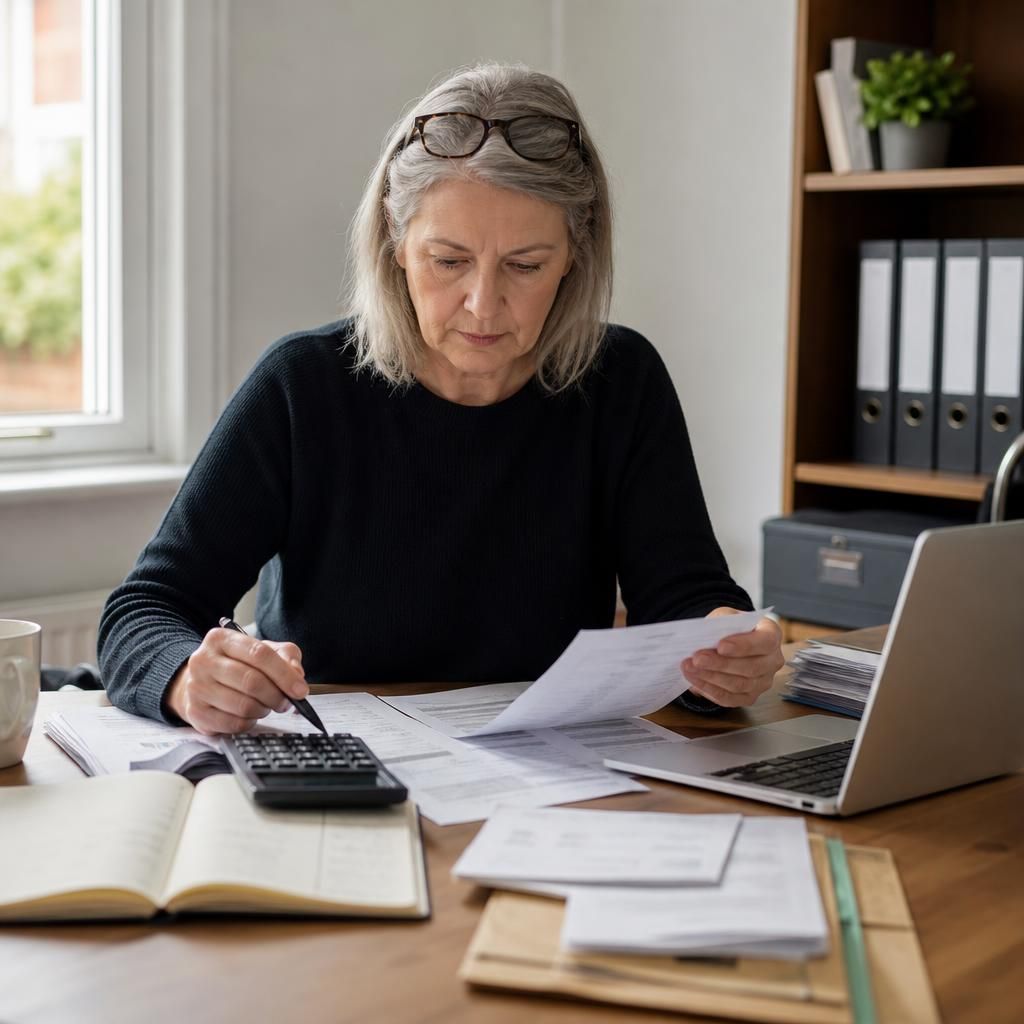
Preparing final estate accounts can be challenging when money has been received and paid out over several months. Interest, refunds, property expenses, professional fees and interim payments to beneficiaries must be reconciled before the estate can be closed.
The personal representative should keep estate funds separate from personal finances, retain invoices and statements, and maintain a running record of every transaction. Draft estate accounts should then show the assets collected, liabilities paid, administration expenses, interim distributions and balance available for final distribution. Giving beneficiaries an opportunity to raise queries before the accounts are finalised can help identify errors and provide a clear basis for completing the administration.