

What are the consequences of not insuring a probate property?
Not insuring a probate property can leave the estate responsible for repair or replacement costs after events such as fire, escape of water, storm damage or vandalism. It may also create problems where a mortgage or other legal obligation requires buildings insurance, and can reduce the property’s protection while ownership is being transferred.
The main consequences of not insuring a probate property are exposure to uninsured liabilities, difficulty administering the estate, potential disputes between beneficiaries and possible personal criticism of the executors’ decisions. Insurance is not automatically a statutory requirement for every property, but the personal representatives still have a responsibility to take reasonable care of estate assets.
Executors may face questions about how the property was protected. Personal representatives should identify foreseeable risks, record the decisions they make and act in the estate’s interests. If they knowingly leave a property without appropriate protection and a loss follows, beneficiaries may argue that the estate’s value was reduced through poor administration. This does not mean an executor automatically becomes personally liable for every loss, but a failure to take reasonable precautions can create avoidable legal and financial disputes.
Uninsured third-party claims can be particularly serious. A vacant or poorly maintained house can create risks for visitors, neighbours, contractors and passers-by. Examples include someone being injured on the premises, damage caused by a loose roof tile or a contractor claiming that unsafe conditions contributed to an accident. Buildings insurance policies often include public liability cover, but an estate without suitable insurance may have to meet the cost of defending a claim and paying compensation from estate funds.
The estate may also have to fund emergency work and professional advice directly. Where there is no valid policy, the personal representatives may need to arrange and pay for urgent securing, drying, clearance, specialist assessment or legal assistance themselves. This can reduce the funds available for debts, taxes, maintenance and distribution to beneficiaries. If the estate has limited cash, the property may need to be sold or other assets used before the administration can continue.
Lack of cover can increase the risk of disagreement among beneficiaries. One beneficiary may want the property sold quickly, while another may prefer to retain it. If an incident occurs during that period, the parties may disagree about who should have arranged insurance, whether the property was adequately inspected or whether the loss could have been avoided. Written records, an agreed maintenance plan and evidence of insurance decisions can help demonstrate that the executors acted prudently.
There may also be practical problems if the property is later transferred, sold or retained by a beneficiary. A purchaser’s solicitor may ask for information about the property’s condition and any incidents during the administration period. Missing records or an uninsured event can complicate negotiations and may require additional surveys, declarations or indemnity arrangements. If the property is leasehold, the building may be covered under a block policy arranged by the freeholder, but this should be verified rather than assumed; the policy may not cover contents, alterations, liability or periods of vacancy.
It is important to distinguish having no insurance from having unsuitable insurance. A standard home policy may restrict or exclude cover when a house is empty, furnished only partly, undergoing works or awaiting sale. A policy can also be affected by non-disclosure, failure to comply with security conditions, unreported changes in occupancy or inadequate inspections. In those circumstances, the estate may believe it is protected but still face a rejected or reduced claim.
Personal representatives should therefore take the following steps:
- Confirm who owns the property and whether a freeholder, managing agent or lender already arranges any buildings cover.
- Tell the insurer that the owner has died and explain whether the property is occupied, vacant, undergoing work or being prepared for sale.
- Check policy conditions covering inspections, heating, water systems, alarms, locks, gardens and notification of changes.
- Arrange appropriate liability and contents protection where those risks are not included in the buildings policy.
- Keep records of quotations, policy documents, inspections, maintenance, incidents and decisions made by the executors.
- Review the cover if the property’s condition, occupancy or intended use changes.
If a property is currently uninsured, the personal representatives should obtain specialist advice before assuming that a standard policy will meet its needs. The appropriate arrangement depends on factors such as whether the house is vacant, its construction, its condition, the presence of valuables and the length of the probate process. Taking action promptly helps protect the estate’s value and gives beneficiaries a clearer record of how the property was managed.
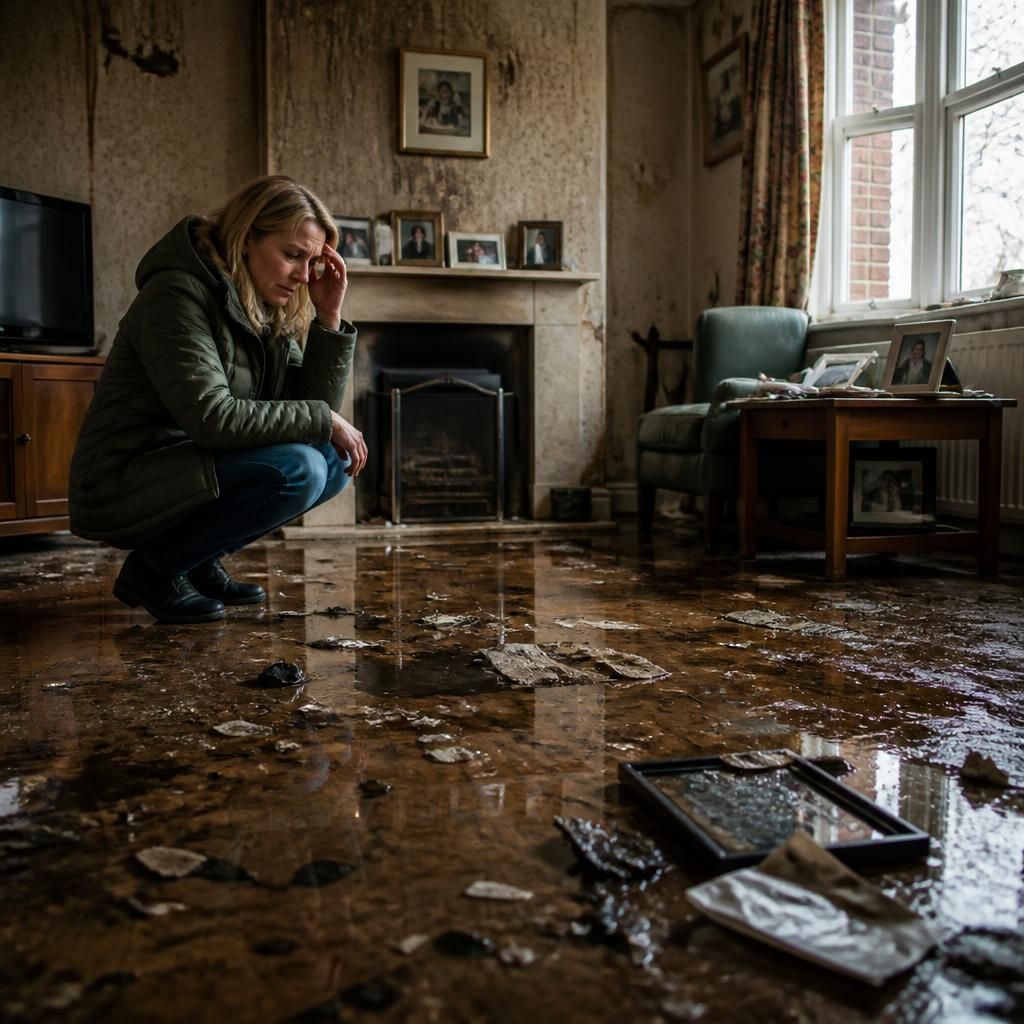
Not insuring the contents of a probate property can leave the estate exposed even where the building itself has some protection. Furniture, appliances, personal possessions and other estate assets may be lost or damaged through theft, fire, escape of water or vandalism, with no policy available to fund replacement or restoration.
Buildings insurance normally covers the structure rather than the deceased’s belongings. Personal representatives should therefore identify valuable or irreplaceable items, keep them secure, update the estate inventory and check whether contents cover applies during vacancy. Without suitable records and insurance, disagreements may arise over what was present, its condition and its value when the loss occurred.
Explore your options for an uninsured probate property
If suitable insurance cannot be arranged, explore whether selling the probate property is appropriate for the estate’s circumstances. buyhousesfast.co.uk purchases residential properties for cash across the UK, including homes with legal or physical complexities.