

What factors determine the cost of insurance for a house in probate?
The cost of house in probate insurance is mainly determined by the property’s condition, location, rebuild value, occupancy status, security and the level of cover required. Premiums may also reflect risks such as vacancy, structural defects, previous claims, unoccupied periods and the likelihood of vandalism, escape of water or other damage.
The cost of insuring a house in probate is determined by the insurer’s assessment of the policy terms, the information supplied by the executor and the risks created by the property’s legal and practical circumstances. Two probate homes with similar values can attract different premiums because they may require different levels of liability cover, endorsements, excesses or policy durations.
The amount and type of cover selected has a direct effect on the premium. A basic buildings policy may not provide the same protection as a policy that also includes contents, accidental damage, alternative accommodation, property owners’ liability, legal expenses or cover for unauthorised entry. Each additional section responds to a different risk, so it is important to distinguish cover that is genuinely required from optional extensions that do not suit the estate.
Property owners’ liability can be particularly relevant during probate. The estate may still owe duties to visitors, neighbours, contractors and anyone carrying out work at the address. If the house is being cleared, inspected or repaired, the executor should check whether the policy’s liability section applies to those activities and whether contractors need their own insurance. Adding appropriate liability cover may affect the premium but can address a separate financial exposure from damage to the building itself.
The excess also influences the price. This is the amount the policyholder agrees to contribute towards a valid claim. A higher excess can reduce the quoted premium, while a lower excess generally increases the insurer’s potential contribution. Policies may apply separate excesses to different types of claim, such as escape of water, subsidence or accidental damage. The executor should compare the total excesses, not just the headline premium, before deciding whether a quote is suitable for the estate.
The length and structure of the policy can matter where probate administration is prolonged. Some policies are arranged for a fixed period, while others continue subject to renewal. The cost may be affected if cover has to be extended, amended after a sale falls through or changed when the property becomes occupied, let, renovated or transferred. Cancelling or changing a policy may also involve terms that affect the overall cost, so the executor should establish how adjustments are handled before buying cover.
Probate and ownership information forms part of the insurer’s underwriting assessment. The proposer may be an executor, administrator, beneficiary, trust or another person with a recognised insurable interest. The insurer may need details of the deceased owner, the grant of probate or letters of administration, the intended use of the property and who has authority to arrange repairs or make a claim. Unclear ownership or incomplete documentation does not automatically determine a higher premium, but it can delay quotation or lead to unsuitable terms if the policyholder is not correctly identified.
Planned work at the property can change the risk being insured. Clearing possessions, carrying out structural work, replacing services or undertaking refurbishment may require a specialist endorsement or a different type of policy. Ordinary household cover may not respond to damage caused during building work, and some policies restrict cover when parts of a building are opened up or left incomplete. The scope, duration and contractor arrangements should therefore be disclosed accurately rather than treated as minor details.
The claims and disclosure terms affect the practical value of a policy as well as its price. Insurers base quotations on the information provided, and material omissions can result in a claim being reduced, rejected or the policy being treated as invalid. Details such as previous incidents connected with the address, known disputes, planned changes in use and any existing policy restrictions should be answered honestly. The insurer may price the risk differently once those facts are known.
Payment arrangements and policy administration may affect the total amount paid. A policy paid in instalments can have a different overall cost from one paid in a single payment, depending on the provider’s terms. Mid-term alterations, replacement documents, extensions and changes to the named policyholder may also carry charges. These costs should be considered alongside the initial quotation when comparing policies.
To assess whether a quote is reasonable, the executor should compare like-for-like information:
- the insured sections and any exclusions or endorsements;
- the excess applying to each significant type of claim;
- the policy period and renewal or extension terms;
- the responsibilities imposed on the estate, including inspections, maintenance and reporting requirements;
- the treatment of renovation, clearance, contractors and changes in use; and
- the identity of the insured party and the procedure for handling a claim during probate.
The cheapest premium is not necessarily the lowest-cost option if it carries a large excess, excludes an important risk or imposes conditions the estate cannot meet. A suitable policy should reflect the property’s actual circumstances and the executor’s authority to manage it, with all material changes reported to the insurer during the probate process.
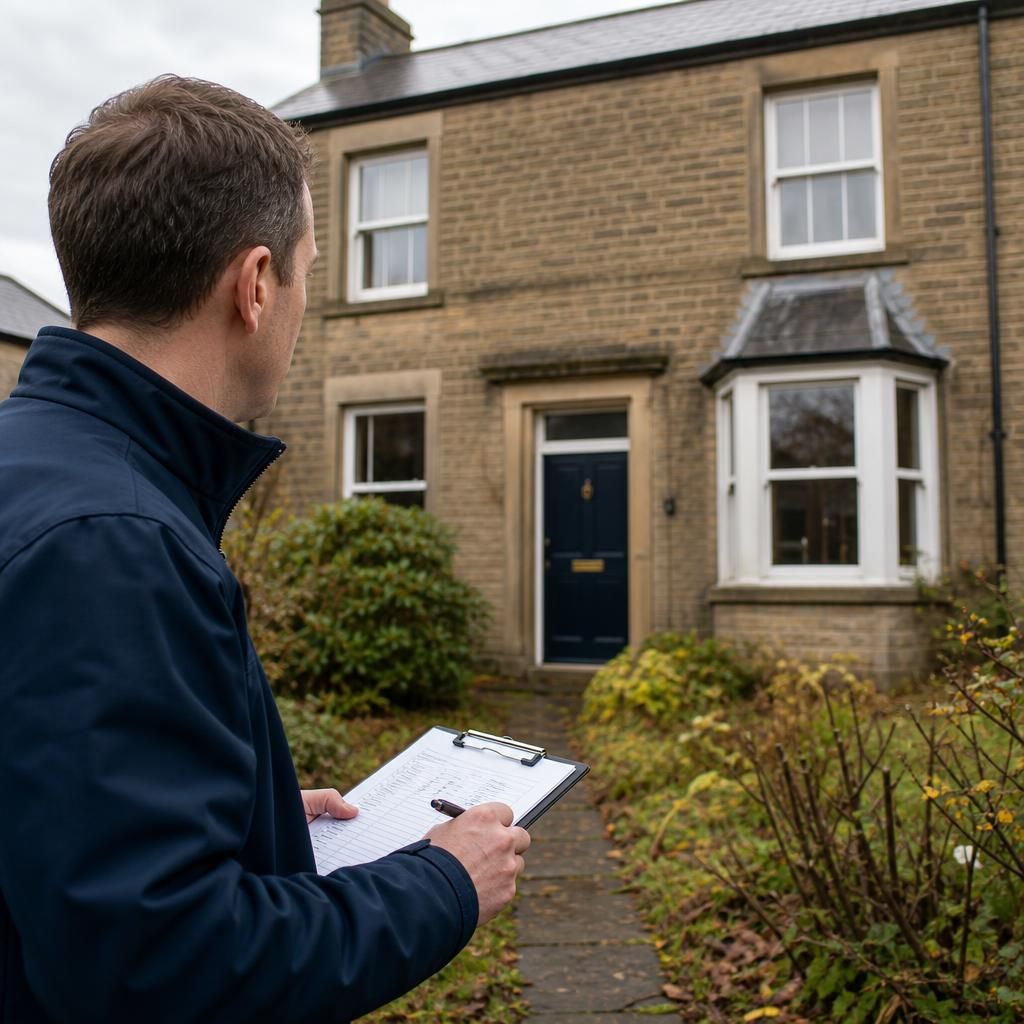
A key factor in house in probate insurance is the property’s rebuild cost, which is different from its potential sale price. The insurer assesses what it could cost to reconstruct the building after serious damage, rather than relying on the amount the property might achieve on the market.
The rebuild assessment may need to account for demolition, site clearance, professional fees and compliance with current building requirements. Older, unusual or listed properties can be more difficult to value accurately because matching materials and specialist workmanship may be required. Providing reliable details about the building’s age, construction and features helps the insurer set an appropriate sum insured and reduces the risk of inadequate cover.