

What financial considerations should be evaluated before purchasing a probate property?
Before purchasing a probate property, assess whether the agreed price reflects an independent valuation and budget for Stamp Duty Land Tax, conveyancing and probate-related legal costs, surveys, repairs, insurance and any finance charges. Also allow for ongoing costs and possible delays, and confirm that your available funds can cover the purchase and works without relying on an uncertain resale value.
The main financial question is whether the probate property still represents good value after allowing for the purchase price, transaction structure, taxes, funding arrangements and the condition of the estate. A buyer should assess the total cost of acquiring and holding the property, test the affordability of the transaction under less favourable assumptions, and establish how probate-related issues could affect the timing or certainty of completion.
Confirm what is included in the price. The agreed consideration may relate only to the property and fixtures. Clarify whether items such as appliances, garden structures, parking spaces, storage areas or additional land are included, as these can affect both value and the drafting of the contract. If the property is being sold through an auction, check the buyer’s premium, administration charges, reservation fee, search-pack cost and any other compulsory payment. These costs can make the effective purchase price materially higher than the winning bid.
Assess the estate’s position. The personal representatives may need to settle estate liabilities before distributing assets, and the sale may require agreement between several beneficiaries. These matters do not normally become the buyer’s debts, but they can affect the seller’s authority to contract, the timing of completion and the risk of a transaction being challenged. Ask the conveyancer to confirm that the correct representatives are selling, that the grant of probate or other authority is sufficient for the proposed transaction, and that any necessary consents are in place.
It is also important to distinguish between an agreed sale and a completed purchase. In England and Wales, an accepted offer is generally not binding until exchange of contracts. Spending money on searches, specialist advice or removal arrangements before exchange carries a risk if the transaction falls through. After exchange, the deposit and contractual obligations become significant, so the buyer should not commit until the funding and completion arrangements are properly confirmed.
Check the tax position for the buyer’s circumstances. Stamp Duty Land Tax depends on factors such as the consideration, the property’s use, whether the buyer already owns another property and whether the buyer is an individual or a company. Different rules apply in Scotland and Wales, where the relevant property transaction taxes are administered separately. A buyer with an existing home, an investment portfolio or a corporate purchasing structure should obtain current advice rather than rely on a standard online estimate. Tax treatment can also differ if the purchase includes non-residential elements or an unusual legal structure.
Probate does not automatically create a tax exemption for the buyer. The estate’s inheritance tax arrangements are generally a matter for the personal representatives, but unresolved tax liabilities or a need to raise funds can influence the seller’s timetable. The buyer should ask whether the representatives’ solicitor has identified any issue that could prevent a valid transfer of the property.
Model the funding carefully. A cash buyer should document the source and availability of funds, including the amount needed for the balance, transaction charges and any immediate works. Money held in investments may not be available on the required date, and transferring funds between accounts can create practical or compliance delays. Where the purchase depends on selling another asset, allow for a lower-than-expected sale value and a longer sale period.
A mortgage or bridging facility introduces additional variables. Check the lender’s policy on probate sales, the validity of the valuation, interest calculation, arrangement fees, legal charges, minimum loan periods, early repayment costs and the consequences of a delayed grant or completion. A bridging loan should have a credible exit strategy, such as refinancing or selling the property; projected resale value alone may not be sufficient if the lender applies a lower valuation or market conditions change.
Calculate the cost of ownership after completion. The property may need to be cleared, secured or brought back into use before it can be occupied or sold. If it will be rented out, allow for compliance work, management, letting costs, void periods and taxation on rental income. If it will be renovated and resold, consider finance costs, professional fees, building control requirements, materials, insurance and the possibility that the finished property will sell for less than forecast.
Future tax should also be considered. A later disposal may create a capital gains tax liability depending on ownership, use and the buyer’s personal or corporate circumstances. A property bought as an investment can have a different tax outcome from one intended as the buyer’s main residence. Professional tax advice is particularly important where the buyer is purchasing through a company, acquiring several properties or planning a substantial refurbishment.
Allow for transaction-specific risks. A title defect, missing document, restriction, rights issue or lack of evidence about alterations may require indemnity insurance, a deed, further investigation or a price negotiation. Each solution has a cost and may affect future mortgageability or resale. If the property is leasehold, review ground rent, service charges, major works, reserve-fund contributions and the remaining lease term. For a freehold, check any estate charge or maintenance obligation that will transfer with the land.
Before committing, prepare a written purchase budget showing the maximum acceptable price, all known acquisition costs, the funding source, the expected holding period and the financial effect of a delayed completion. Use conservative assumptions for resale value, rental income and refurbishment costs. Independent legal and tax advice can then test the assumptions, while the conveyancer can confirm whether the estate has the authority to sell and whether any unresolved issue could create further cost.
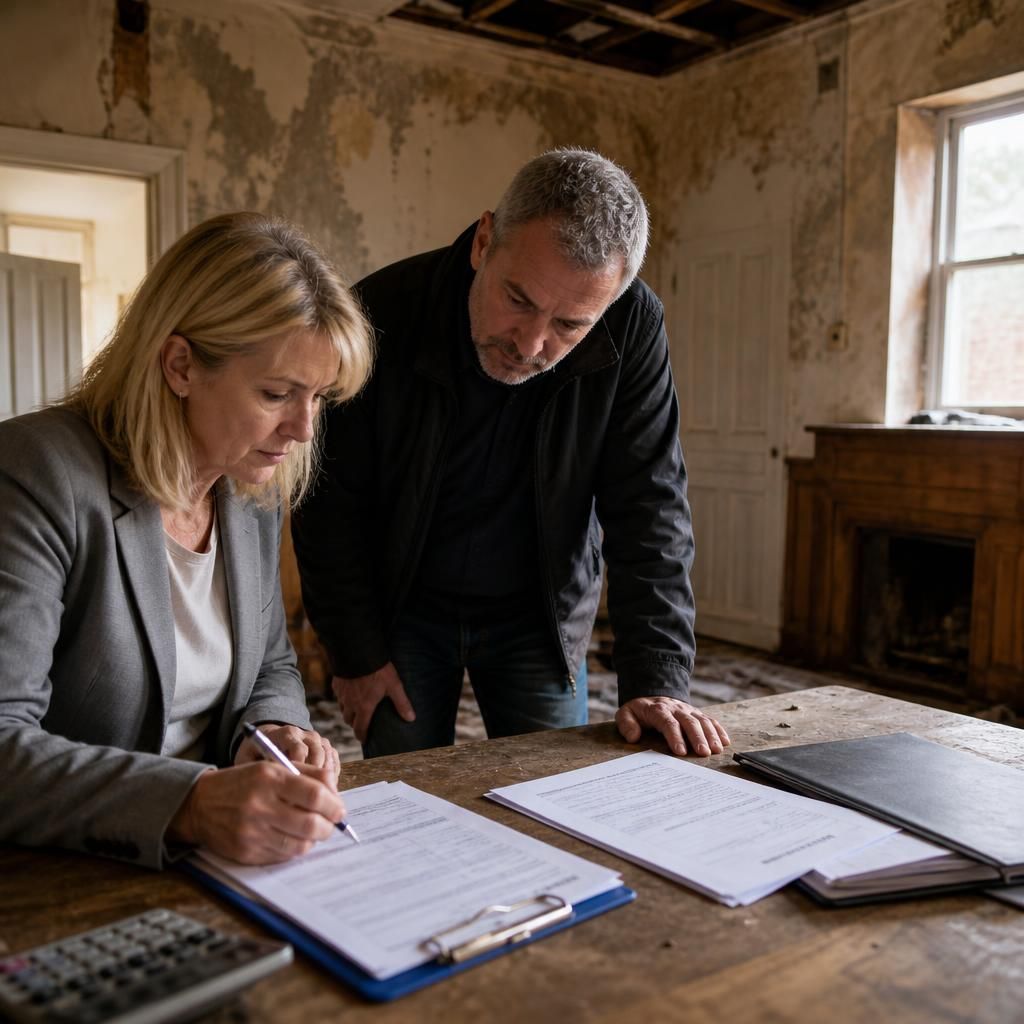
Check insurance costs and responsibilities before exchange. Probate properties are often vacant, and standard home insurance may exclude or restrict cover when a property is unoccupied. Obtain a quotation based on the property’s actual condition, occupancy status and intended use, and check whether the policy requires precautions such as regular inspections, secured doors or heating arrangements.
Also confirm in the contract when responsibility for buildings insurance passes from the estate to the buyer. The position can depend on the contract and jurisdiction, so do not assume that cover begins automatically on completion. Include any specialist premium, excess, security measure or temporary cover in the financial assessment, particularly if completion is delayed or the property will remain empty after purchase.