

How does the cash buying process differ for probate properties compared to traditional real estate sales?
A cash sale of a probate property usually involves a direct offer, legal checks and completion without estate-agent marketing, viewings or a buyer’s mortgage approval. Traditional sales generally require marketing the property, accepting an offer and managing a longer chain, while a probate sale must also account for the executor’s authority and the estate’s legal requirements.
The cash buying process for a probate property is usually more document-led and estate-focused than a traditional sale. Although the buyer’s funding does not depend on a mortgage, the transaction still depends on confirming who can sell, establishing the estate’s authority to transfer the property and satisfying the conveyancer’s checks.
1. The estate’s position is established first. The seller will normally need to identify the personal representative responsible for the property. This may be an executor named in the will or an administrator appointed where there is no valid will. The buyer’s solicitor will usually request evidence of that authority, together with the death certificate, the will where relevant and the Grant of Probate or Letters of Administration when required.
This is a key difference from an ordinary sale by an individual homeowner. In a standard transaction, the seller’s authority is generally shown through their ownership records. With probate, the legal representative may need to complete the sale on behalf of the estate, and the buyer’s conveyancer must ensure that the correct person signs the contract and transfer.
2. The property is assessed for a direct cash offer. A cash buyer will consider the home’s location, size, condition, title information and likely market value. Probate properties may have been unoccupied, contain stored belongings or require maintenance, so the assessment can include visible defects and practical issues that would affect a conventional marketed sale.
An offer may therefore be based on the property being accepted in its current condition. This can reduce the need for the estate to arrange repairs, clearance or presentation work before proceeding. It does not remove the buyer’s right to investigate significant defects, restrictions or other matters affecting the title.
3. The parties agree terms with the estate’s responsibilities in mind. The personal representative should consider whether the proposed price reflects the property’s condition and the estate’s obligations. Where there is more than one beneficiary, the representative may also need to keep records showing how the decision was reached. If the property is subject to a mortgage, charges, a tenancy or outstanding bills, these matters should be disclosed and dealt with during the conveyancing process.
In a traditional sale, the agreed price can remain exposed to later events such as a purchaser’s mortgage valuation, a lender’s conditions or a linked transaction failing. A cash purchase removes the mortgage-lending stage, but it does not eliminate contractual or legal risks. The buyer can still withdraw before exchange, and the transaction is not legally binding until contracts are exchanged.
4. Conveyancing focuses on title, probate and property checks. The solicitors investigate ownership, boundaries, rights of way, restrictions, planning matters, local authority information and any charges registered against the property. Probate-related questions are considered alongside the usual conveyancing enquiries. If the Grant of Probate is pending, the parties may need to decide whether to wait, agree suitable contractual arrangements or postpone exchange until the representative has the necessary authority.
The buyer’s available funds may be evidenced as part of the process. This is different from a mortgage-funded sale, where the purchaser must also satisfy a lender’s underwriting and valuation requirements. Nevertheless, the cash buyer should still provide appropriate evidence of funds and identity, and the estate should use an independent conveyancer to review the proposed transaction.
5. Completion transfers the property and releases the sale proceeds. Once the legal work is satisfactory and contracts have been exchanged, completion takes place under the agreed contract. The purchase money is sent to the seller’s conveyancer, who deals with any mortgage redemption, secured charges and authorised deductions before accounting to the estate. The personal representative is then responsible for distributing the net proceeds in accordance with the will or intestacy rules, after settling the estate’s liabilities and obtaining appropriate advice.
Overall, a cash purchase can make the funding and transaction structure more straightforward than a conventional estate-agent sale, but probate remains the controlling feature. The absence of mortgage finance does not bypass the Grant of Probate, title investigation, beneficiary considerations or the formal conveyancing process. The safest approach is to agree the sale only after the representative’s authority, the property information and the buyer’s funds have been independently checked.
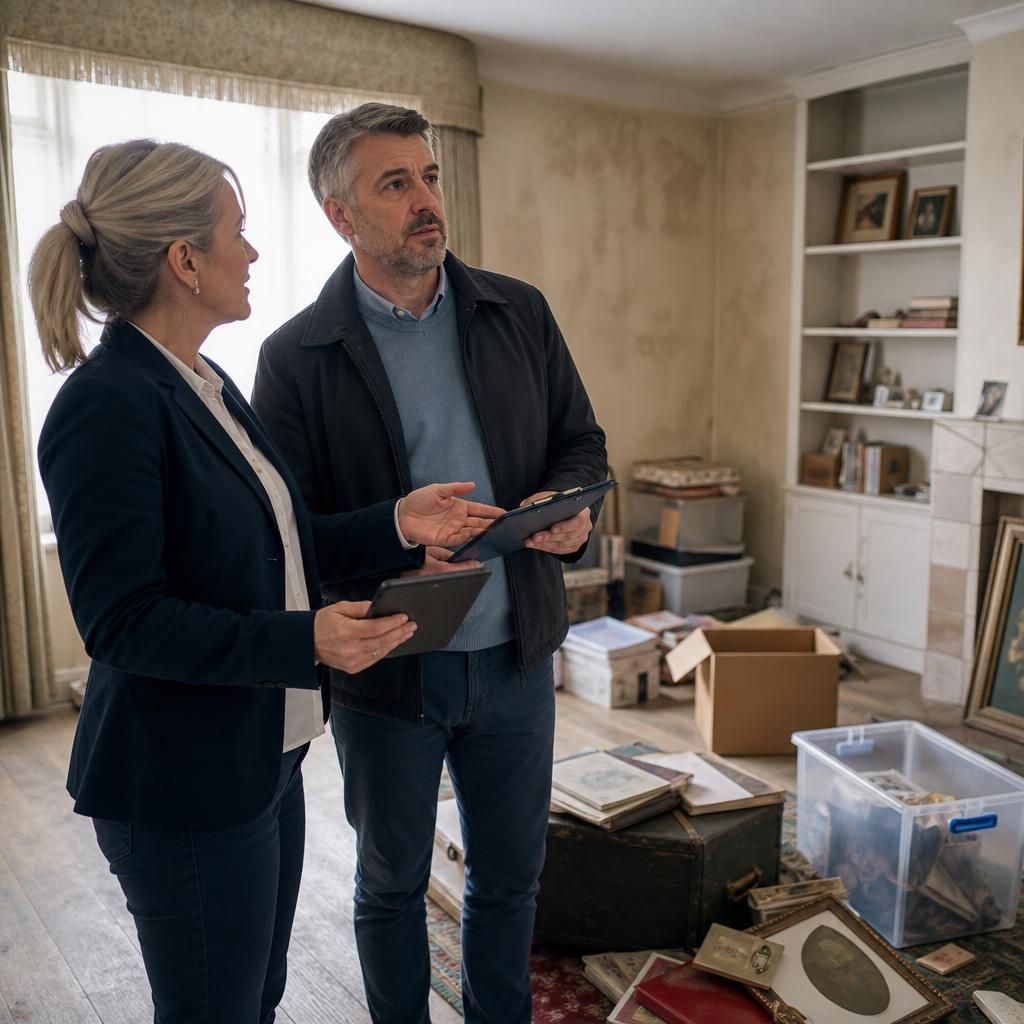
A key practical difference is that a probate cash sale often requires the estate to manage the property while the legal authority is being completed. A vacant or inherited home may need to be secured, insured on suitable terms and protected from deterioration before completion. The personal representative should also establish who can provide keys, arrange access for inspections and decide how the deceased’s belongings will be dealt with under the estate’s instructions.
These practical arrangements are separate from the buyer’s funding. Paying in cash does not transfer responsibility for the property before completion, nor does it settle questions about contents, utilities, insurance or vacant possession. They should be recorded clearly in the sale agreement and discussed with the conveyancers so that the buyer and estate have the same understanding of what will remain at the property on completion.
Discuss your probate property cash sale options
If you are considering a cash sale for a probate property, discuss the available options with Buy Houses Fast before deciding how to proceed. Independent legal and estate advice can help you assess the proposed terms alongside the estate’s requirements.