

What factors should be considered when determining the asking price for an inherited house post-probate?
An inherited house asking price after probate should reflect recent comparable sales, its location, size, condition, tenure and any legal or physical issues affecting buyer demand. Also consider current local market conditions, likely selling costs and whether the priority is achieving the highest possible price or securing a more straightforward sale.
The appropriate asking price for an inherited house after probate is the current price at which the property is likely to attract serious, proceedable buyers, rather than automatically the figure used for probate purposes. A probate valuation generally relates to the property’s value at the relevant date for the estate, whereas an asking price should reflect present market evidence, the property’s saleability and the outcome the beneficiaries need to achieve.
Start with the distinction between value and asking price. A valuation is an informed opinion of what the property may be worth. The asking price is a marketing decision. It may be set close to the estimated market value, slightly above it to allow for negotiation, or at a more competitive level to encourage early interest. The chosen approach should be agreed by the personal representatives and, where relevant, the beneficiaries.
Use completed sales as the strongest evidence. Recent sold prices for genuinely comparable properties are generally more useful than online asking prices, which show what sellers hope to achieve rather than what buyers have paid. Comparisons should take account of:
- the property’s type, accommodation and overall layout;
- its plot, parking, garden and useful outbuildings;
- the standard of fixtures, fittings and any recent improvements;
- the date of each comparable transaction and changes in the market since completion; and
- differences that could affect a buyer’s willingness to proceed, such as unusual construction or restricted use.
Several comparable transactions should be considered rather than relying on one apparently similar sale. A local estate agent’s appraisal can provide current buyer feedback, while an independent surveyor’s valuation may be appropriate where the property is unusual, contentious between beneficiaries or difficult to compare.
Check whether the property can be sold on the terms assumed by the valuation. The price may need to reflect matters such as a short lease, service-charge exposure, restrictive covenants, rights of way, absent title information, tenant occupation or uncertainty over vacant possession. These issues do not necessarily prevent a sale, but they can reduce the number of interested buyers, lengthen conveyancing or lead to renegotiation after an offer. The asking price should therefore be based on information that can be supported during the legal process, not on an assumption that every buyer will accept the same risks.
Allow for findings that may emerge during marketing. A buyer’s survey could identify roof, damp, structural, drainage, electrical or other defects that were not apparent during an initial inspection. It is sensible to distinguish between essential work, improvements that may increase appeal and cosmetic work that is unlikely to recover its cost. Quotations can help quantify known defects, but the full cost of a project is not always reflected pound for pound in the sale price. A realistic price can reduce the scope for substantial renegotiation later.
Consider the likely buyer pool. Some properties appeal mainly to owner-occupiers, while others may attract landlords, developers or buyers seeking a renovation project. A price aimed at one group may exclude another. Features such as mortgageability, planning history, access, building condition and the practicality of obtaining insurance can be particularly important when assessing how widely the property can be marketed.
Calculate the estate’s expected net proceeds. The headline price is not the amount eventually available for distribution. Before settling on a figure, the personal representatives should estimate sale-related deductions, which may include estate agency fees, conveyancing, clearance, essential works, mortgage redemption and other property-related costs. This helps beneficiaries compare offers properly and prevents a slightly higher offer from appearing more attractive when it carries materially greater deductions or a higher risk of failing to complete.
The asking price should also reflect the estate’s practical priorities. If the beneficiaries can accommodate a longer marketing process, testing a higher figure may be reasonable. If the property has ongoing costs, deterioration risk, difficult legal features or disagreement between beneficiaries, a more straightforward route may justify accepting a different price from the theoretical maximum. Any decision should compare the likely net result and certainty of completion, not just the initial offer.
Choose the pricing format carefully. An advertised asking price, a guide price or an “offers over” figure can each create different expectations. The wording should not suggest that a particular offer will be accepted if the personal representatives still need to consider the estate’s position or obtain beneficiary agreement. It is also important to decide in advance how offers will be assessed, including the buyer’s funding, chain position, proposed timescale and willingness to proceed after receiving the relevant property information.
Where a cash buyer is considered, compare the proposed price with realistic open-market net proceeds rather than comparing it with an optimistic advertised figure. A direct sale may reduce some marketing steps and provide a clearer transaction structure, but the estate should still check the buyer’s proof of funds, the proposed contract terms and any deductions. The relevant question is whether the overall outcome suits the estate’s objectives, not simply whether the offer is labelled “cash”.
Finally, retain a written record explaining how the asking price was reached. This can include valuation reports, comparable sales, property particulars, known defects, estimated costs and the reasons for accepting or rejecting offers. A documented and evidence-based approach helps personal representatives demonstrate that they acted reasonably, particularly where several beneficiaries have different expectations or where the eventual sale price differs from the original valuation.
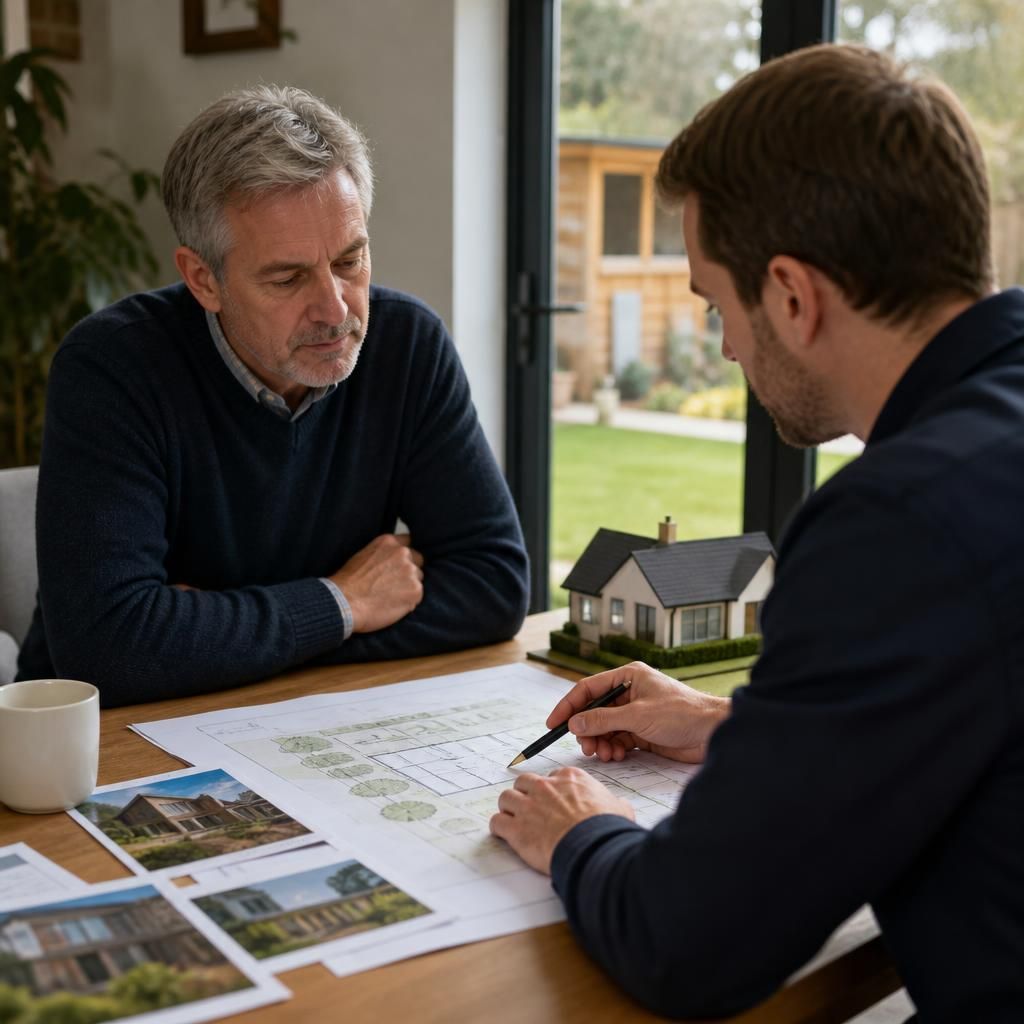
Development potential should only be reflected in an inherited house’s asking price when it is supported by reliable evidence, such as an existing planning permission, a lawful development certificate or a well-founded professional assessment. An agent’s assumption that an extension, conversion or separate dwelling might be possible is not the same as confirmed value, particularly where local policies, access, drainage or neighbouring constraints may apply.
If the property includes a large garden, outbuilding, adjoining land or adaptable space, ask the valuer to assess both its current residential use and any evidenced alternative potential. Separating the value of the existing home from speculative uplift helps prevent an inflated asking price, reduces the risk of disappointing buyers during due diligence and gives the personal representatives a clearer basis for comparing offers.