

How can property condition affect the speed and outcome of a probate property sale?
A probate property’s condition can affect both how quickly it sells and the price achieved: significant repairs, safety issues, or clearance requirements may reduce buyer interest and lead to renegotiation or delays. A clear, accurate assessment helps the executor decide whether to sell as-is or complete targeted work before marketing, while a cash buyer may be able to consider properties requiring substantial attention.
Property condition affects a probate sale by influencing the buyer pool, the evidence needed to support the asking price, the likelihood of mortgage approval and the amount of work required before completion. It can therefore affect not only the sale price, but also the certainty of the transaction and the executor’s ability to administer the estate efficiently.
Condition is more than appearance. Buyers, valuers and lenders may consider the property’s structural integrity, state of repair, services, safety and compliance. A dated kitchen or worn decoration may have limited importance, whereas subsidence, defective roofing, damp, unsafe electrics, plumbing failures or Japanese knotweed can create more material concerns. Missing documentation for alterations, uncertain lease terms or unverified repair work may also affect how the property is assessed, even where the physical condition appears acceptable.
Probate properties can present additional uncertainty because the executor may not have lived in the home or know its maintenance history. Before deciding how to market it, the executor should establish what is known about the building and identify matters that could affect value or a buyer’s ability to proceed.
Condition can affect the likely buyer pool. A property requiring only cosmetic updating may appeal to ordinary owner-occupiers as well as investors. A home needing extensive renovation is more likely to attract buyers with the funds, experience and appetite to manage building work. If the property is unmortgageable because of serious defects or lacks essential facilities, the pool may narrow further. Fewer suitable buyers can mean fewer offers and greater reliance on the accuracy of the initial description.
It can also influence the type of transaction available. Many mortgage-funded buyers require a valuation and may depend on the lender accepting the property as suitable security. Significant defects can lead to a lower valuation, conditions being attached to lending, requests for specialist reports or a refusal to lend. A cash buyer is not dependent on a mortgage valuation in the same way, although the condition will still be relevant to the price offered and the buyer’s due diligence.
Deciding whether to repair or sell as-is requires a cost-and-risk comparison. The executor should consider:
- the estimated cost of each repair, including professional fees and any necessary permissions;
- whether the work is essential for safety or legal compliance, or merely intended to improve presentation;
- whether the work can be supervised properly while the estate is being administered;
- the effect of leaving the property vacant during repairs, including security, utilities and insurance requirements;
- whether the likely increase in sale proceeds justifies the expenditure and additional administration; and
- whether repair work could expose the estate to further defects, disputes or delay.
Renovation does not automatically produce a better outcome. Work can improve presentation and broaden appeal, but poor workmanship, incomplete projects or unexplained alterations may make a property harder to assess. Where the executor is considering substantial expenditure, a written valuation and independent estimates can help demonstrate that the decision is reasonable and in the estate’s interests.
Accurate disclosure is essential. Known defects should not be concealed or described ambiguously. The seller may need to provide information about past movement, flooding, insurance claims, building work, disputes, notices and problems with services. If a buyer discovers a material issue after accepting an offer, they may renegotiate, commission further investigations or withdraw where the contract has not exchanged. A clear description at the outset can reduce avoidable disagreement, although it cannot replace appropriate surveys and legal enquiries.
Specialist reports may be appropriate where there is evidence of structural movement, damp, timber decay, roof failure, asbestos-containing materials or contaminated land. Reports should be commissioned from suitably qualified professionals and retained with the estate records. They may clarify the seriousness of a defect, distinguish urgent repairs from longer-term maintenance and give prospective buyers a more reliable basis for making an offer.
Condition also affects marketing and valuation strategy. A valuation should reflect the property’s actual state, not the value of a fully refurbished equivalent. Comparable properties need to be genuinely comparable in terms of location, size, tenure, access and condition. Presenting a realistic price from the beginning may generate more relevant interest than setting an optimistic figure and making repeated reductions after buyers identify the same problems.
Practical preparation can improve the presentation without committing the estate to major refurbishment. This may include removing rubbish, securing the building, cutting back overgrown gardens, dealing with obvious leaks, cleaning the property and ensuring that rooms and outbuildings can be inspected safely. The executor should keep records and receipts for expenditure, particularly where costs will be paid from estate funds.
Vacant properties require particular care. Unoccupied homes can deteriorate through leaks, frozen pipes, damp, pest activity or unauthorised access. Regular inspections, appropriate insurance arrangements and prompt attention to new damage can help preserve the property’s condition while the sale is progressing. The executor should check the terms of the estate’s insurance, because vacancy, renovation and known defects may affect cover or impose conditions.
The condition of the property may become especially important between accepting an offer and completion. A leak, theft, storm damage or failed heating system can change the buyer’s assessment and lead to further negotiations. The property should remain reasonably secure and accessible for agreed inspections, and material changes should be reported to the conveyancer rather than left for the buyer to discover.
Where speed is important, selling in its existing condition may avoid the time and uncertainty associated with a major renovation. A cash buyer may consider a property that needs substantial work, but the offer will normally reflect the anticipated repairs, professional costs, risk and resale prospects. The executor should compare any such proposal with the likely net proceeds from marketing more widely, taking account of repair costs, holding costs and the risk that a sale may not proceed.
A sensible process is to establish the facts, obtain independent advice where necessary, document known issues, value the property on its actual condition and choose between targeted preparation, a conventional sale or a cash sale based on the estate’s priorities. The best route is not determined by appearance alone: it depends on the seriousness of the defects, available funds, legal information, the executor’s capacity to manage works and the level of certainty required.
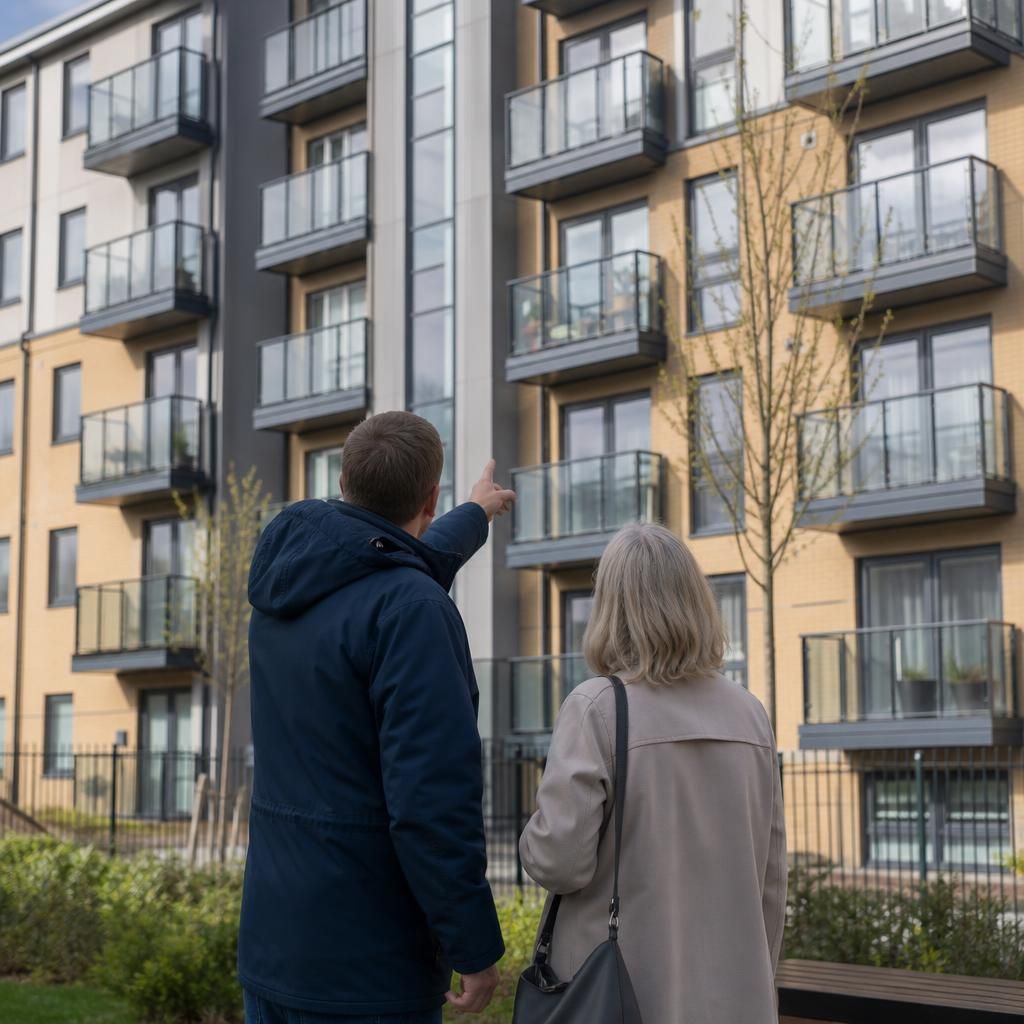
For a leasehold probate property, the condition of the wider building can affect the sale as much as the condition of the individual flat. Problems with communal roofs, external walls, lifts, windows or shared services may lead to major works, higher service charges or additional buyer enquiries. Planned works and notices should be identified early, because uncertainty about future costs can reduce offers or cause a buyer to reconsider.
The executor should obtain relevant information from the managing agent or freeholder and pass it to the conveyancer. This can help buyers assess the property accurately and reduce delays caused by unanswered questions about communal repairs, insurance claims or outstanding contributions. A flat that appears well maintained internally may still achieve a different outcome if the building requires substantial work.