

How is a probate property valuation conducted?
A probate property valuation is conducted by assessing the property’s condition, location, features and comparable local sales to establish its open-market value at the date of the deceased’s death. A valuer normally inspects the property, reviews relevant documents and evidence, then produces a written valuation report for the executor and inheritance tax reporting.
A probate property valuation is a formal, evidence-based assessment of the property’s value for the deceased’s estate, using the required valuation date and an appropriate basis of value. It is normally carried out retrospectively, so the valuer considers the property and market conditions as they were at the date of death rather than relying solely on its present-day price.
The process usually begins with the executor’s instructions. The valuer confirms the property address, the deceased’s ownership interest, the purpose of the valuation and the valuation date. They may also ask for information about the tenure, occupancy, mortgages, leases, planning matters, alterations and any known restrictions. Clear instructions are important because a valuation for inheritance tax may require a different approach from an informal estimate prepared for a potential sale.
The valuer then gathers background evidence. This can include title information, property particulars, floor plans, planning records, lease details and market data for comparable properties. Where the valuation is retrospective, the valuer researches transactions and market conditions relevant to the date of death. Later sales may sometimes provide useful evidence, but they need to be considered carefully because prices and local conditions can change.
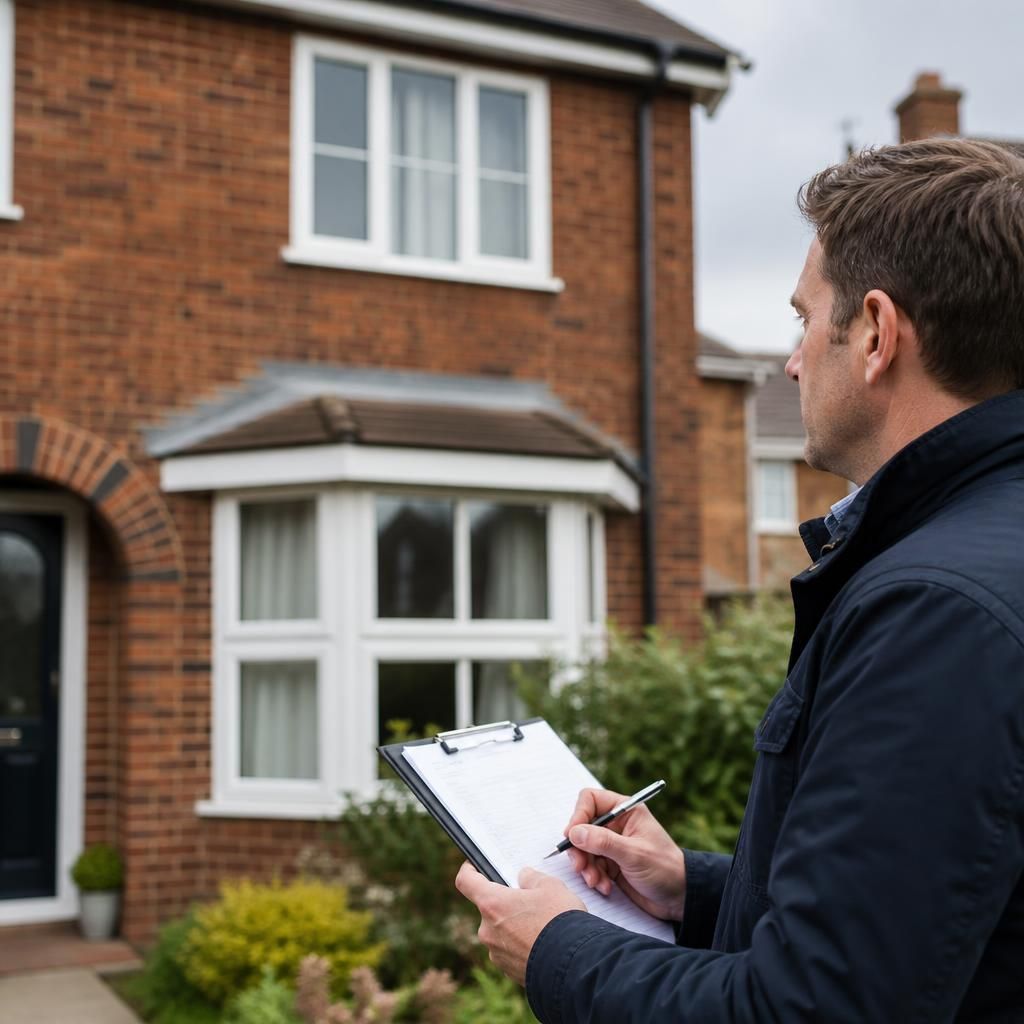
An inspection is usually the next stage. The valuer records the accommodation, layout, construction, state of repair, quality of fixtures and any apparent defects. They may note issues such as subsidence indicators, damp, structural movement, Japanese knotweed, asbestos risk or unauthorised alterations, although a standard valuation inspection is not the same as a full building survey. If parts of the property cannot be inspected, the report should identify the resulting assumptions and limitations.
The valuer analyses comparable evidence rather than simply selecting the highest or lowest nearby sale. Adjustments may be needed for differences in size, plot, condition, accommodation, parking, outlook, tenure and sale date. A property that appears similar in an online listing may not be a reliable comparison if it differs materially in condition or legal status. The valuer’s professional judgement is used to reconcile the evidence into a reasonable figure for the relevant date.
Legal and ownership details can affect the conclusion. The valuer considers whether the property is freehold or leasehold, whether a lease has a short remaining term, and whether rights of way, covenants or other restrictions could influence marketability. If the deceased owned the property jointly, the executor should explain the ownership arrangement. The report may need to distinguish between the value of the whole property and the deceased’s interest, with the appropriate treatment confirmed for the estate’s tax position.
The final report normally sets out:
- the property inspected and the interest being valued;
- the valuation date and purpose;
- the basis of value and relevant assumptions;
- the inspection findings and any significant limitations;
- the comparable evidence and reasoning used;
- the concluded value; and
- the valuer’s details, professional status and declaration of responsibility.
The executor should check the report against the estate records before using it. Errors in the address, ownership, valuation date or property description can affect the result. The valuer should be told about material information discovered later, such as a previously unknown lease issue, planning breach or structural problem, because the opinion may need to be reviewed.
For inheritance tax reporting, the valuation is submitted as part of the estate information required by the relevant authority. HMRC may ask how the figure was reached or request supporting evidence, particularly where the property has unusual characteristics or the reported value is disputed. Keeping the report, comparable evidence and related documents with the estate records gives the executor a clear audit trail.
A probate valuation is therefore more than an online estimate or an agent’s marketing opinion. It combines a defined valuation date, inspection findings, ownership information, market evidence and written reasoning. Where the property has complex legal, structural or ownership circumstances, the executor should obtain appropriate legal, tax or surveying advice alongside the valuation rather than asking one professional to address matters outside their expertise.
A probate property valuation records the property’s market value, not the amount the estate will ultimately receive. Mortgage balances, estate administration costs, legal fees, taxes and other liabilities are dealt with separately when calculating the estate’s net position. The valuation should therefore not be reduced simply because money is owed against the property.
This distinction also matters if the executor later considers a direct or cash sale. An offer may differ from the probate valuation because it reflects the proposed transaction’s terms, the property’s condition, any work required and the buyer’s costs and risks. The valuation remains evidence of the property’s value for the relevant estate purpose; it is not automatically a guaranteed sale price or a statement of the estate’s net proceeds.