

What role does an executor play in the probate property valuation process?
An executor organises the probate property valuation, provides the valuer with relevant information and uses the resulting market value when reporting the estate’s assets. They must also keep appropriate records and ensure the valuation supports accurate estate administration.
The executor is responsible for ensuring that a probate property valuation is suitable for the estate’s legal, tax and administrative requirements. They do not normally determine the figure themselves: their role is to establish the correct basis and valuation date, appoint an appropriately experienced valuer, assess the report critically and use the outcome consistently when administering the estate.
Establishing the correct valuation basis
For probate purposes, the relevant figure is generally the property’s open-market value at the date of death, rather than its original purchase price, an estate agent’s asking price or the amount eventually achieved on sale. The executor should make sure the valuer understands that the report is required for estate administration and, where relevant, inheritance tax reporting. A later sale price can be useful evidence, but it does not automatically replace the valuation at the date of death.
The executor should also clarify whether the valuation concerns the whole property, a share in jointly owned property, or an interest affected by a lease, tenancy or other restriction. These distinctions can materially affect the figure reported for the estate.
Giving the valuer a complete factual picture
A reliable assessment depends on relevant information being identified and considered. This may include:
- the property address, type, accommodation and approximate size;
- the title position and ownership share held by the deceased;
- planning permissions, building regulations approvals and known development potential;
- tenancies, occupational arrangements, rights of way, covenants or restrictions;
- structural defects, contamination, subsidence, disrepair or other physical issues;
- fixtures, furnishings or land that may or may not form part of the property interest; and
- any previous valuation, marketing history or transaction involving the property.
It is important not to conceal an inconvenient defect or assume that an issue is too minor to mention. If information is discovered after the report is issued, the executor should ask whether the valuer needs to reconsider the opinion.
Choosing and instructing the valuer
The executor should select someone with appropriate experience in residential property valuation and probate work, particularly where the property is unusual, tenanted, jointly owned or affected by legal complications. The written instruction should identify the property interest being valued, the valuation date, the intended use of the report and any known matters requiring investigation.
Independence is also relevant. An executor should consider whether the proposed valuer has a personal, financial or commercial connection that could undermine confidence in the assessment. Where the property may later be sold to a connected person or where beneficiaries disagree about its treatment, an independent report is especially important.
Checking the report rather than accepting it uncritically
Receiving a valuation does not end the executor’s responsibility. They should check that the report:
- relates to the correct property and ownership interest;
- uses the correct date and valuation basis;
- describes the property accurately;
- explains the comparable evidence or reasoning supporting the figure; and
- identifies assumptions, limitations and matters requiring further investigation.
The executor is not expected to reproduce the valuer’s technical analysis, but an obviously inconsistent description, unexplained adjustment or omission should be queried. If the estate includes several properties, each should be considered separately before the figures are combined.
Using the valuation in estate administration
The valuation may inform the estate accounts, inheritance tax calculations where applicable, the probate application and decisions about whether a property should be retained, transferred or sold. The executor must distinguish the property’s probate value from other figures, such as the outstanding mortgage, selling costs, later improvements or the eventual sale proceeds. Those items may affect the estate’s net position, but they do not change what the property was worth at the relevant valuation date.
Where a property is sold later for more or less than the probate valuation, the executor should retain the sale particulars, offers, completion statement and any professional explanation for the difference. A changed market, unexpected defects, a restricted sale process or improvements made after death may explain the outcome. Professional tax or legal advice may be appropriate if the difference creates a reporting issue.
Managing disagreements and shared responsibility
Co-executors generally need to participate in significant decisions and should keep a clear record of how the valuation was commissioned and accepted. Beneficiaries can ask questions, but they do not normally replace the executor’s decision-making role. If beneficiaries, co-executors or creditors dispute the figure, the executor should avoid selecting a value simply because it is convenient and may need an independent review or specialist advice.
An executor who has a personal interest in acquiring the property, or who has another conflict, should disclose it and obtain appropriate advice before taking further action. Their central duty is to deal with the estate properly and impartially, using evidence that can be explained to beneficiaries, HMRC or another relevant authority if the valuation is later examined.
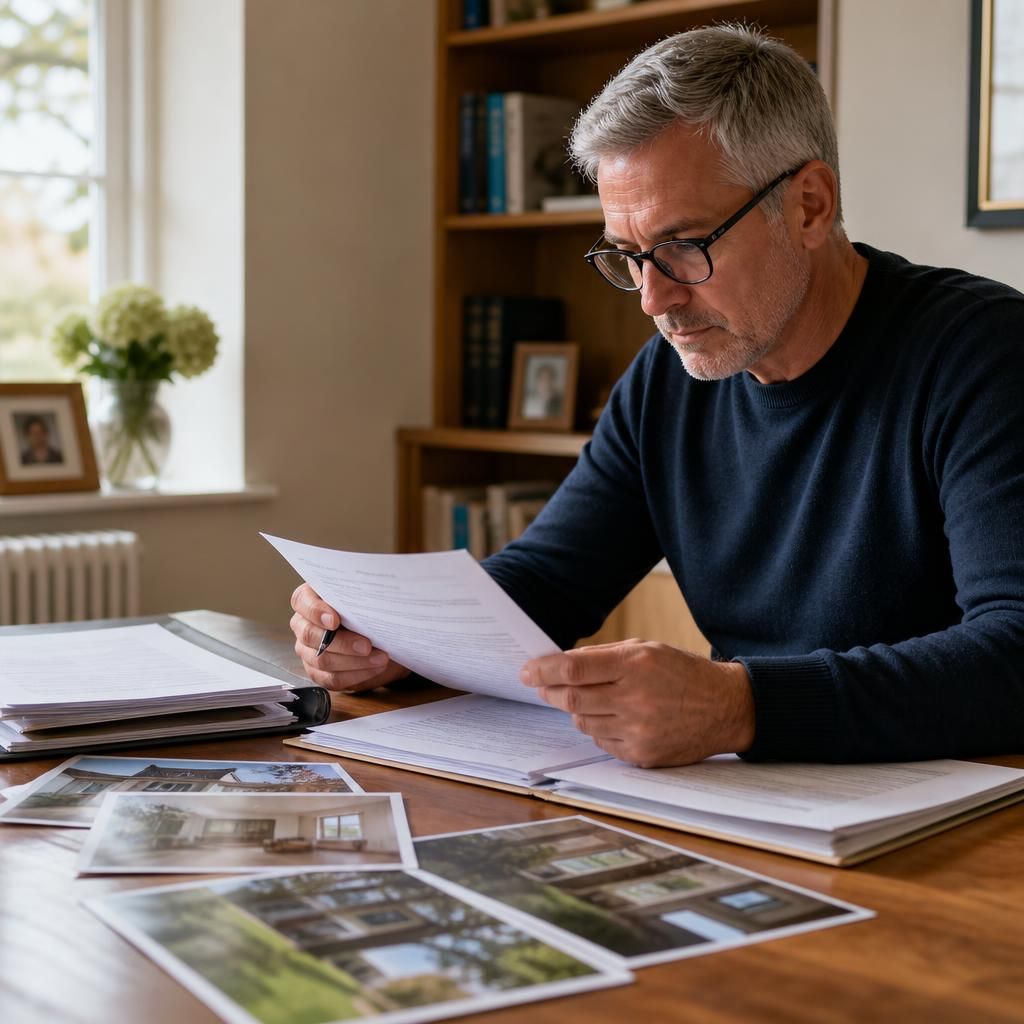
One important part of the executor’s role is ensuring that the valuation reflects the property market at the date of death, particularly when the report is prepared months or years later. The valuer may need to use historical comparable sales, market evidence and the property’s condition at that earlier date rather than relying solely on current prices.
The executor should therefore provide records showing the property’s condition and circumstances at the relevant time, such as photographs, inspection notes, tenancy details or correspondence about defects. This helps distinguish changes that existed at the valuation date from improvements, deterioration or market movements that occurred afterwards. If the available evidence is incomplete, the executor should ask the valuer to explain any assumptions made in the report and retain that explanation with the estate records.