

What factors influence the offer price made by cash buyers?
A cash buyer’s offer is typically influenced by the property’s location, condition, size, legal status and local market demand. The buyer will also assess comparable sales, required repairs, transaction costs, resale prospects and any risks that could affect the purchase.
A cash buyer’s offer price is based on the amount the buyer expects the property to be worth to their business after allowing for purchase costs, finance, risk and the return required for the proposed transaction. It is therefore not always the same as an estate agent’s suggested asking price or an open-market valuation.
The buyer’s intended use of the property
A buyer will consider what they plan to do after completion. The property might be retained as a rental, refurbished and resold, occupied by the buyer, or used as part of a wider investment portfolio. Each option produces a different valuation because the expected income, resale value and expenditure are different.
For example, a property with strong rental potential may be assessed partly by its likely rental income, while a buyer intending to resell it will focus more heavily on the expected resale proceeds and the costs of preparing it for that sale. The buyer’s strategy can therefore affect the offer even where two buyers inspect the same home.
How quickly the buyer needs to deploy capital
Cash does not mean that every buyer values every property in the same way. A company may have funds allocated to a particular type of purchase, or may be looking for opportunities that fit an existing portfolio. If a property does not fit that strategy, the buyer may make a more cautious offer or decline to proceed, regardless of its general market appeal.
This is a commercial consideration rather than a direct reflection of the home’s full market value. It explains why offers from different cash buyers can vary considerably.
Tenure and ongoing obligations
Whether a property is freehold or leasehold can affect the price, but the important details go beyond the basic tenure label. For a leasehold home, the buyer may review the unexpired lease term, service charges, ground rent provisions, planned major works and restrictions on alterations or subletting. A short lease or uncertain future expenditure can reduce the amount a buyer is prepared to offer.
For a freehold property, shared access arrangements, maintenance obligations and private roads may also affect the assessment. These matters can increase the buyer’s future costs or make the property harder to sell on.
Occupancy and possession arrangements
The buyer will want to know who occupies the property and whether it can be handed over with vacant possession. Tenants, lodgers, family members or former owners may create practical and legal requirements that have to be resolved before the buyer can use or resell the home.
An existing tenancy can sometimes add value where a buyer wants rental income, but it can reduce the appeal to a buyer who needs the property vacant. The tenancy agreement, rent position and compliance records may therefore influence both the offer and the proposed terms of the sale.
Planning history and permitted use
Planning permissions, building regulation approvals and certificates for past alterations can influence the buyer’s view of the property. An extension, loft conversion or change of use may add value if it is properly documented and usable for its intended purpose. Missing approvals or unresolved planning conditions may lead to extra investigation, a lower offer or a requirement for indemnity insurance.
Potential development value is also treated cautiously. A possible extension or future conversion is not the same as an approved project. Buyers generally distinguish between established rights and an idea that would still depend on planning consent, funding and technical work.
Title information and saleability
The buyer’s solicitor will examine the title to establish exactly what is being purchased. Covenants, easements, boundary discrepancies, ransom strips, flying freeholds and rights affecting access or services can all influence the assessment. The issue is not simply whether a problem exists, but whether it can be understood, insured against or resolved without delaying a future sale.
A property with clear documentation is usually easier to value than one where ownership records, boundaries or rights are uncertain. Supplying accurate information at the outset can reduce the allowance a buyer makes for uncertainty.
Energy performance and running costs
Energy performance can affect both the buyer’s expected costs and the property’s appeal to future occupants. The energy performance certificate, heating system, insulation and likely improvement requirements may be considered alongside other running costs. For an investment buyer, these details can affect rental demand and compliance planning; for a resale buyer, they may influence how easily the property can be marketed.
Other recurring costs, such as insurance, communal charges and maintenance obligations, may also be included in the buyer’s financial model.
Sale terms and transaction certainty
The proposed terms can affect the amount offered. A buyer may value a straightforward transaction with clearly agreed inclusions, reliable access for inspections and a defined completion arrangement. Conversely, uncertainty about documents, possession, included fixtures or the seller’s authority to sell may be reflected in the offer.
It is important to distinguish between the headline price and the terms attached to it. An offer that appears higher may involve fees, deductions, conditions or a longer period of uncertainty. A lower headline figure may produce more favourable net proceeds if it has fewer deductions and clearer contractual terms.
How to assess whether an offer is fair
- Ask for the offer in writing, including any conditions and the proposed deductions.
- Request a clear breakdown of the amount you would receive after agreed costs, mortgage redemption and other liabilities.
- Obtain an independent valuation or opinions from relevant local property professionals so that you have a reference point.
- Provide accurate details about tenure, occupancy, planning documents and any known title matters before the offer is finalised.
- Compare the complete terms of more than one proposal rather than comparing headline prices alone.
- Have your own conveyancer review the contract, fees and any clauses allowing the buyer to change or withdraw the offer.
A cash offer should be judged by its net value, the certainty of its terms and the practical requirements attached to completion. Understanding the buyer’s intended use, the property’s documentation, ongoing obligations and the conditions of the transaction makes it easier to identify how the figure was calculated and whether it fairly reflects the circumstances of the sale.
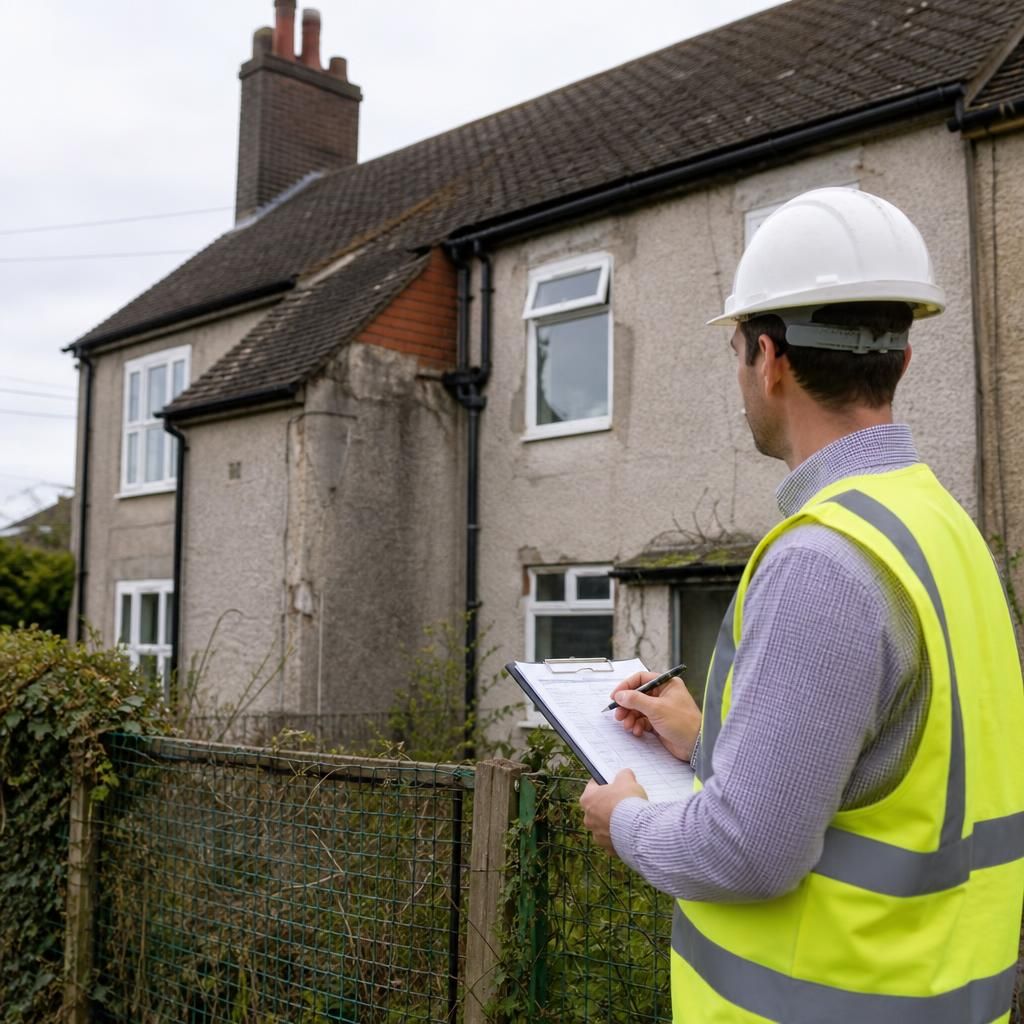
Future mortgageability can affect a cash offer. Although the buyer is not relying on a mortgage to complete the purchase, they may consider whether a future purchaser or lender is likely to accept the property. Non-standard construction, serious structural concerns, unusual lease provisions or unresolved defects can reduce the number of potential buyers when the property is later sold.
This can lower the offer because the buyer may face a narrower resale market, additional specialist advice or a longer marketing period. A cash purchase therefore does not automatically remove the financial effect of issues that could make the property difficult to mortgage or resell.