

What factors determine if my property qualifies for a fast cash offer?
A property’s eligibility for a fast cash offer usually depends on its type, condition, location, title status and any legal or financial complications. The seller’s circumstances and the buyer’s ability to assess the property and complete the transaction also influence whether an offer can be made.
A property usually qualifies for a fast cash offer when the buyer can understand the asset, verify the seller’s authority to sell and calculate a purchase price that reflects the work, risk and time involved. There is no universal pass-or-fail checklist: eligibility is assessed on the individual property and the circumstances surrounding the sale.
One important distinction is the difference between being eligible for an offer and receiving the price expected by the owner. A buyer may be willing to consider a property with complications, but those complications can affect the valuation or the conditions attached to the offer. A cash purchase removes the need for mortgage approval, but it does not remove the need for due diligence.
- Clear ownership and authority: The person accepting the offer must be able to demonstrate that they have the right to sell. If there are joint owners, executors, trustees or attorneys involved, the buyer’s solicitor will need to confirm that the necessary parties can authorise the transaction.
- Occupancy arrangements: The buyer will need to know whether the property is empty, occupied by the owner, or let to tenants. Tenancy agreements, deposits, notices and any agreed vacant-possession arrangements can affect the transaction and the practical handover of the property.
- Leasehold terms: For a leasehold property, the remaining lease term, ground rent, service charges, planned major works and management information may all affect its suitability. Delays in obtaining a management pack or uncertainty over lease obligations can also influence the proposed terms.
- Planning and building records: Extensions, conversions, alterations and changes of use may need supporting permissions or certificates. Missing paperwork does not automatically make a property ineligible, but it gives the buyer a matter to investigate and may lead to further legal enquiries, a revised offer or a requirement for suitable indemnity arrangements.
- Access for inspection: A buyer generally needs enough information to assess the property and arrange appropriate inspections. Restricted access, incomplete details or an inability to examine important areas can make it harder to form a reliable valuation.
- Outstanding borrowing and completion figures: The seller should establish what remains payable on any mortgage or other secured lending, together with any relevant redemption charges. The sale proceeds must be sufficient to deal with these sums, or the seller must have another agreed way to cover any shortfall.
- Chain position: A cash buyer may not require the seller to purchase another property, but the seller’s wider circumstances can still affect the proposed completion arrangements. A sale involving probate, separation, multiple owners or another linked transaction may require additional coordination and evidence.
- Price expectations: The requested price is compared with the property’s likely resale value, costs of purchase, required work and the risks identified during assessment. A property can qualify for consideration even when the buyer cannot support the owner’s preferred figure.
Information supplied at the outset can make the eligibility assessment more precise. Useful documents may include title information, planning and building-control records, tenancy paperwork, service-charge statements, guarantees for relevant works, mortgage details and probate or court documents where applicable. The exact documents depend on the property and the seller’s circumstances.
The buyer’s solicitor will normally investigate the title, raise enquiries and check whether the proposed contract accurately reflects the transaction. Searches and inspections can identify matters that were not apparent from an initial discussion, such as restrictions affecting use, access rights, disputed boundaries or notices relating to the property. These findings may change the offer rather than end the sale.
For that reason, a preliminary cash offer should not automatically be treated as the final amount or as proof that completion is certain. The final position depends on the information verified during conveyancing and on both sides agreeing the contract. Before proceeding, a seller should ask what assumptions the offer relies on, which costs are deducted, whether any conditions apply and what evidence of funding is available.
In practice, the strongest applications are those where ownership, occupancy, property records and financial obligations can be explained clearly. However, unusual circumstances do not necessarily prevent a fast cash sale; they mainly determine the level of investigation required and whether the buyer can price the associated risk responsibly.
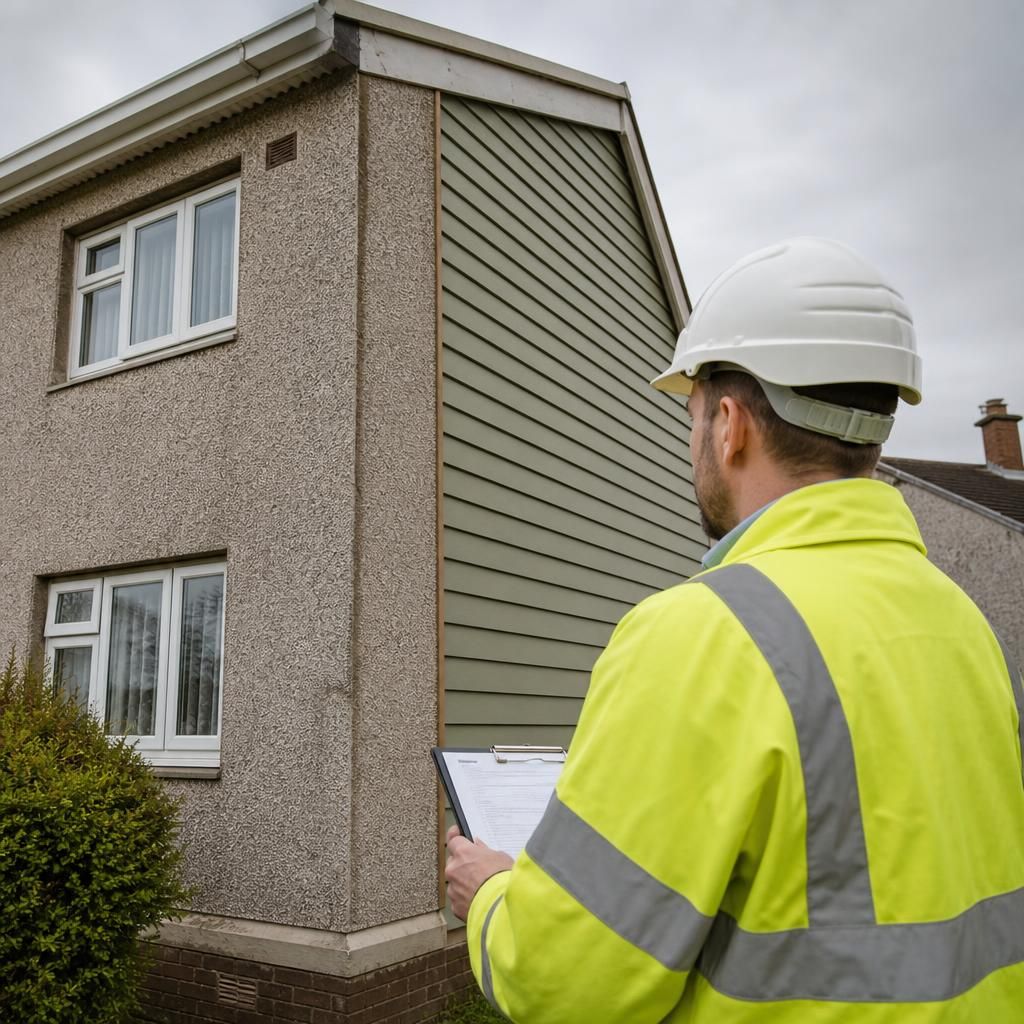
Construction type can affect eligibility even when the property is otherwise straightforward to sell. Houses and flats built using less common methods, such as certain system-built, timber-framed or prefabricated designs, may require additional survey evidence before a buyer can assess the risks involved. The key questions include whether the structure is sound, insurable and likely to appeal to future buyers.
Non-standard construction does not automatically prevent a fast cash offer. However, the buyer may need specialist reports, details of previous remedial work or confirmation that suitable insurance is available. These findings can influence the price and the conditions of the offer because they affect future resale and ownership costs.