

What are the key advantages of selling my house for cash?
The key advantages of selling your house for cash are a potentially faster transaction, greater certainty than waiting for a buyer’s mortgage approval, and a simpler process with fewer chain-related delays. It can also suit properties requiring repairs or involving probate, divorce, mortgage arrears or other complications, although the cash offer should be assessed carefully against the property’s market value.
The key advantages of selling a house for cash are greater control over the sale, less preparation and fewer dependencies on third parties. A cash buyer does not need mortgage approval to fund the purchase, which can make the transaction more straightforward. However, the exact benefits depend on the buyer’s terms, the property’s condition and the legal work required.
More control over the sale process
A cash sale may give you more influence over practical arrangements than a conventional sale. The parties can discuss a completion date that fits the seller’s circumstances, subject to the buyer’s agreement and the progress of conveyancing. This can be useful if you need to coordinate a move, settle an estate or plan around another financial commitment.
There may also be less dependence on a chain. In a conventional transaction, another buyer’s sale or purchase can affect the timetable. A cash buyer who is not relying on a related property transaction can remove one source of uncertainty, although legal enquiries, searches and other checks can still affect completion.
Less work preparing the property
Cash buyers often consider properties in their existing condition. This may reduce the need for cosmetic improvements, extensive cleaning, removal of unwanted items or repairs before putting the property on the market. It can be particularly relevant where the owner does not want to organise works, cannot fund them or is dealing with a property that has been empty, neglected or altered.
This does not mean defects can be concealed. You should disclose known problems accurately and allow the buyer to carry out appropriate inspections and enquiries. The condition of the property will usually be reflected in the offer.
Fewer viewings and less disruption
A direct cash sale can avoid some of the activity associated with open-market marketing, such as repeated viewings, photography, advertising and keeping the property ready for prospective purchasers. This can provide practical and personal privacy, particularly where the home is occupied, contains valuable belongings or is connected with a sensitive family or financial situation.
It may also reduce the need to make decisions based on feedback from several potential buyers. Instead, the discussion is generally focused on one proposed transaction and its terms. The buyer may still need access for valuation, inspection and legal requirements.
A clearer basis for comparing the financial outcome
A cash offer can make it easier to focus on the net amount you would receive and the conditions attached to it. When comparing an offer, consider:
- the proposed purchase price;
- any deductions or fees;
- whether the buyer expects you to pay for particular legal or administrative items;
- whether the offer is subject to a survey, valuation or other conditions; and
- the likely costs and effort of taking an open-market route.
A higher advertised price is not necessarily a higher net outcome if it involves substantial preparation, marketing costs, agent fees or a longer period before completion. Conversely, accepting a lower cash offer may not be sensible if the reduction is greater than the costs and practical value of the alternative. Independent valuation advice can help you make a properly informed comparison.
Reduced reliance on mortgage lending
With a cash-funded purchase, the transaction does not depend on a mortgage lender approving the buyer’s application or accepting the property as suitable security. This removes a particular source of delay or failure. It does not remove every risk: the buyer must still have genuinely available funds, and the conveyancers must resolve title issues, identity checks, property information and any other legal matters.
For that reason, ask how the buyer’s funds will be verified and whether the offer is genuinely cash-funded. A written offer should explain its conditions, and you should not treat an assertion that a buyer is a cash purchaser as proof on its own.
Potentially greater privacy and administrative simplicity
Dealing directly with a buyer can mean fewer parties involved in marketing and negotiation. This may be helpful when the reasons for selling are private or when several owners, executors or representatives need to agree on the transaction. The process still requires a conveyancer or solicitor, especially where there is a mortgage to redeem, probate, a trust, a leasehold title or another legal complication.
Before accepting an offer, obtain independent legal advice and ask the conveyancer to explain the contract, completion arrangements and any restrictions. Check the buyer’s identity, funding and company details where relevant, and establish whether the offer can be changed after inspection. The advantages of a cash sale are strongest when the price is fair, the terms are clear and the legal process is handled properly.
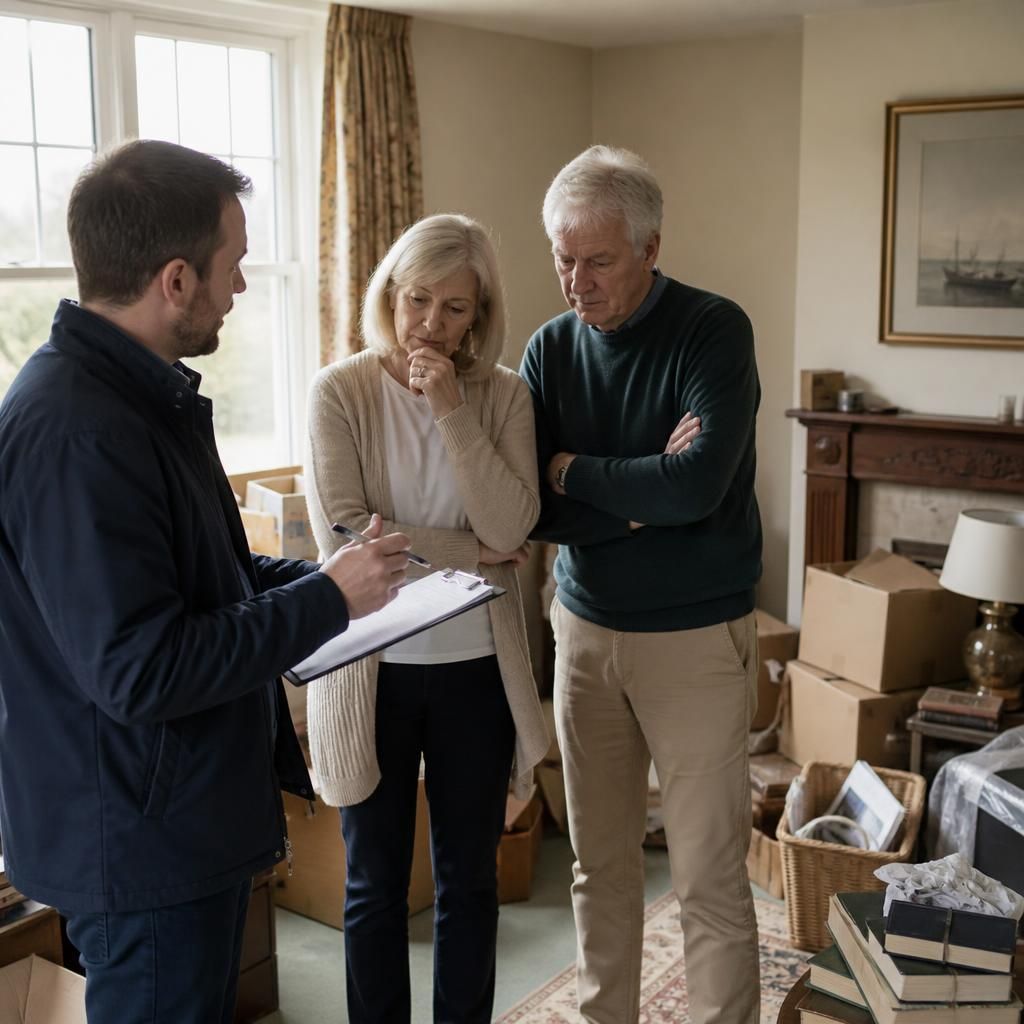
A cash sale can be particularly useful where the property is difficult to present for conventional marketing, such as an inherited home containing furniture and personal belongings. A buyer assessing the property in its current state may allow the executor or owner to deal with clearance and practical arrangements without first preparing the house for public viewings. This can reduce the amount of coordination required before the sale is put forward, although the property’s condition and contents should be described accurately and any agreed arrangements recorded in writing.