

How does the quick property sale process work?
The quick property sale process usually involves sharing your property details, receiving a cash offer, completing legal checks and conveyancing, and agreeing a completion date. Because the sale is handled directly with a cash buyer rather than marketed through an estate agent, there are fewer traditional selling stages to manage.
The quick property sale process is a shortened version of a conventional residential transaction: the buyer assesses the property, both parties agree the commercial terms, solicitors verify the legal position, and the sale completes once the contract is ready. The main difference is that the property is not usually exposed to an open-ended marketing and viewing period, although the legal transfer still needs to be handled properly.
1. Provide the relevant property information. The buyer will normally need the address, property type, tenure, approximate condition and details of any issue affecting the sale. This may include an existing mortgage, arrears, tenants, probate, divorce proceedings, leasehold restrictions, planning matters or known defects. Accurate information at this stage helps identify issues that could affect the offer or the transaction.
Useful documents can include title information, planning and building regulation records, guarantees, tenancy agreements, service charge statements and lease details where applicable. Missing paperwork does not necessarily prevent a sale, but it can lead to additional enquiries or delay while the position is established.
2. Review the proposed terms carefully. A cash offer should be assessed as more than a headline price. Check whether it is conditional on a survey, whether any deductions may be made after further investigations, who is responsible for particular costs, and whether the proposed completion arrangements suit your circumstances. If the property is leasehold, the remaining lease term and any service charges or major works may also be relevant.
Before accepting, ask for the offer and its conditions in writing. You should understand whether the buyer intends to purchase in its own name or through another company, and whether the transaction depends on selling another property or obtaining finance. A genuinely cash-funded purchase does not remove the need for legal checks, but it may reduce dependence on a mortgage lender.
3. Instruct conveyancers. You and the buyer each need legal representation to transfer ownership. Your conveyancer checks the title, prepares or reviews the contract pack, answers enquiries and deals with any mortgage redemption figure. If the property is leasehold, the management information and lease obligations require particular attention.
The conveyancing stage can include searches, title checks, identity checks and questions about boundaries, alterations, rights of way and planning history. The exact requirements depend on the property and its circumstances. Probate sales, properties with absent paperwork and homes affected by legal disputes may require further evidence before contracts can be exchanged.
4. Agree the contract and completion arrangements. The contract sets out the property, price, parties and terms of the transaction. It may also record matters such as fixtures and fittings, vacant possession, restrictions or agreed deductions. The completion date should be confirmed only when the legal and practical arrangements are sufficiently clear.
Exchange of contracts makes the agreement legally binding in the usual way. Before exchange, either party may generally still be able to withdraw, subject to any separate agreement and costs incurred. After exchange, the conveyancers prepare for completion, including confirming funds, paying off any secured borrowing from the sale proceeds and arranging the handover of keys.
5. Complete and transfer ownership. On completion, the buyer’s funds are sent through the conveyancing process. Your solicitor then authorises release of the keys, repays any mortgage or other agreed charges, settles the solicitor’s fees and sends the remaining balance to you. The buyer’s solicitor registers the change of ownership with HM Land Registry after completion.
A quick sale does not mean that every transaction follows the same timetable or that legal safeguards can be skipped. The length and complexity of the process can be affected by the title, property condition, leasehold administration, outstanding borrowing, probate, tenants, planning issues and the responsiveness of the parties involved. Independent legal advice is important, particularly where the sale is connected with arrears, repossession, divorce or an estate.
For a homeowner comparing this route with an estate-agent sale, the key points are the certainty of the terms, the evidence supporting the buyer’s funding, the deductions proposed and the legal work required before commitment. A cash buyer may provide a more direct route, but the offer should still be checked against your financial needs and the property’s circumstances before you proceed.
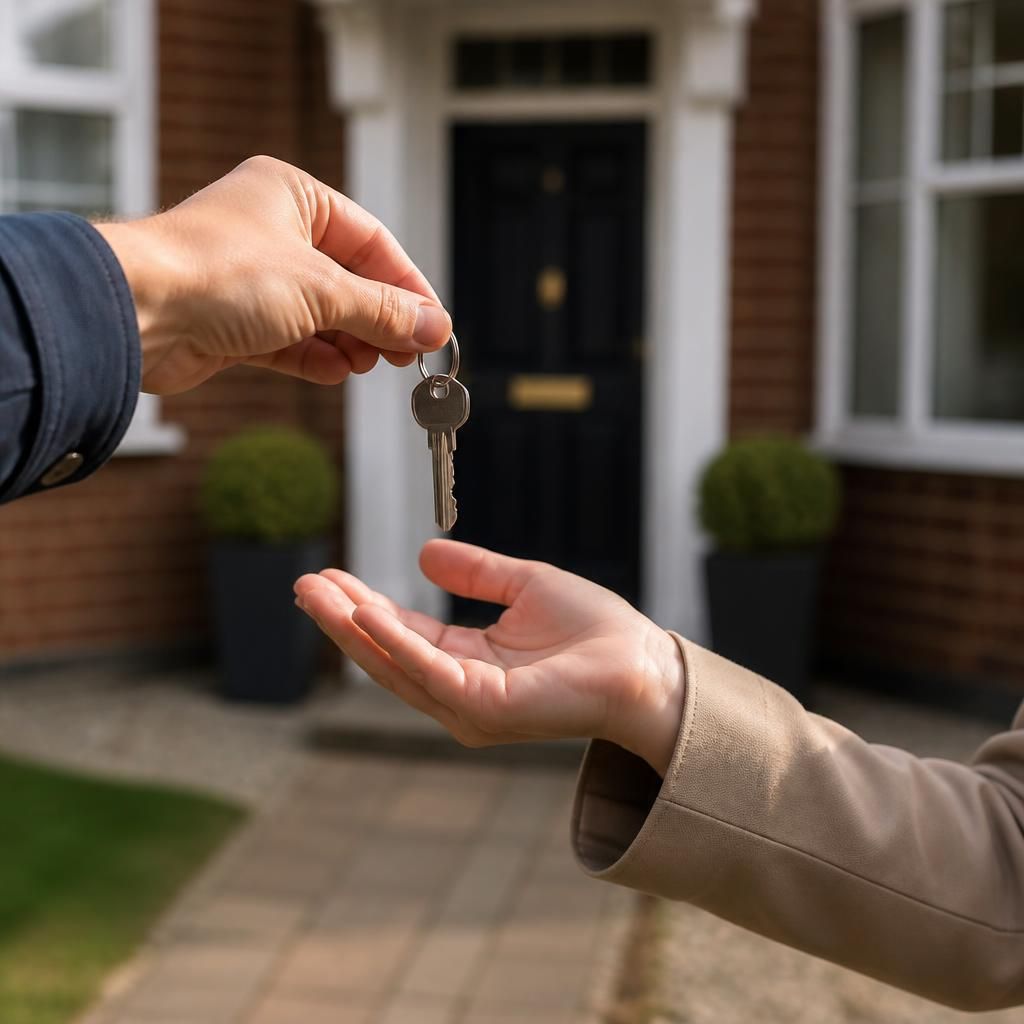
Completion day is the point at which the purchase money is transferred and responsibility for the property passes to the buyer. The seller should follow the arrangements agreed in the contract and with the conveyancer so that the handover does not create practical problems.
- Remove personal belongings and leave any fixtures, fittings or appliances included in the agreement.
- Provide vacant possession if this is a contractual requirement, unless the buyer has agreed to take the property with tenants or other occupants in place.
- Gather all keys, fobs, remotes and relevant access codes for handover.
- Take final meter readings and keep records of them, then notify the relevant utility providers and local authority of the change of ownership.
- Keep buildings insurance in place until completion has taken place, as responsibility can depend on the contract.
If the property is not ready in the condition or manner agreed, the conveyancers may need to resolve the issue before the handover is completed. Confirming these practical details in advance helps ensure that the legal transfer and physical handover take place consistently.