

What factors should I consider when determining the sale price for a quick house sale?
To determine a fair price for a quick house sale, consider the property’s location, size, condition, comparable local sale prices, current market demand and the costs or risks a cash buyer may factor into their offer. Also account for any legal issues, lease restrictions, tenancy arrangements, outstanding mortgage or property charges, as these can affect the net amount you receive.
A realistic price for a quick house sale is based on the property’s likely open-market value, adjusted for the greater certainty and different terms of a direct cash transaction. The figure should be assessed against recent completed sales, the condition of the title and the buyer’s expected costs, rather than relying only on online estimates or asking prices.
Separate market value from the amount you receive. An estate-agent valuation usually considers what the property might achieve after marketing, viewings and negotiation. A cash offer reflects a different route: the buyer may be taking on the work of purchasing, managing and reselling the property without the usual marketing period. Compare the headline offer with the proposed completion terms and any deductions so that you understand the net proceeds.
Use completed sales as the main benchmark. Advertised prices show what sellers hope to achieve, not necessarily what buyers have paid. Look for recently completed transactions involving genuinely comparable homes. The most useful comparisons usually match the property’s type, approximate floor area, tenure, number of bedrooms, parking provision and level of modernisation. A small number of carefully selected comparisons is more useful than a broad list of superficially similar listings.
Consider how easily the property can be resold. Two homes with similar valuations can attract different offers if one is more straightforward to market. Buyers may consider the layout, natural light, access, parking, outdoor space, local amenities and the likely pool of future purchasers. Unusual construction, limited access, restrictive use, a short lease or an unusual ownership structure can reduce the price a cash buyer is prepared to offer because they may make resale or lending more difficult.
Check the tenure and lease position carefully. For leasehold property, the remaining term, ground rent provisions, service charges, restrictions and any planned major works can influence value. A buyer will normally want these details verified rather than relying on an informal description. For freehold property, rights of way, shared access, boundary arrangements and maintenance obligations may also affect the assessment. These points should be reflected in the price before accepting an offer.
Account for the quality of the information available. A buyer can price more confidently when the ownership documents, property details, planning records and relevant certificates are complete and consistent. Missing paperwork does not automatically make a sale impossible, but it can create uncertainty and lead to a lower offer or a request for further investigation. Gathering the information early can help distinguish a genuine adjustment from an avoidable reduction.
Assess the proposed deal, not just the number. Price is only one part of the transaction. Review whether the offer is subject to valuation, survey, legal checks, funding or another sale. Consider the proposed completion date, whether vacant possession is required, what fixtures and fittings are included, and whether the buyer can change the offer later. An apparently higher figure may be less attractive if it carries conditions that could delay or jeopardise completion.
Understand why a direct cash offer may differ from an open-market valuation. A buyer may allow for finance, professional fees, refurbishment, insurance, ownership costs and the risk that the eventual resale price is lower than expected. The offer may also reflect the capital tied up until resale. These deductions are not necessarily evidence that the valuation is wrong; they are part of the buyer’s calculation for taking on the transaction through a different route.
Compare more than one independent view. You can request valuations from local estate agents, consult a qualified surveyor where appropriate and obtain written offers from relevant cash buyers. Ask each source to explain the assumptions behind its figure. If valuations vary significantly, check whether they are based on different assumptions about tenure, repairs, occupancy, marketing time or completion conditions.
Test the effect of your priorities. If the main objective is to maximise the price, a conventional sale with marketing and buyer negotiations may produce a different result from a direct sale. If certainty, a chosen completion date or avoiding a chain is more important, accepting a lower gross figure may be rational. Make the comparison using the amount you are likely to retain, the time involved and the conditions attached, rather than comparing headline figures alone.
Before agreeing a price, request the offer in writing and check whether it is fixed or subject to later revision. Ask for a clear explanation of any deductions, confirm which costs each party will pay, and have the legal documents reviewed by an independent conveyancer. This gives you a more reliable basis for deciding whether the proposed price fairly reflects the property and the terms of the quick sale.
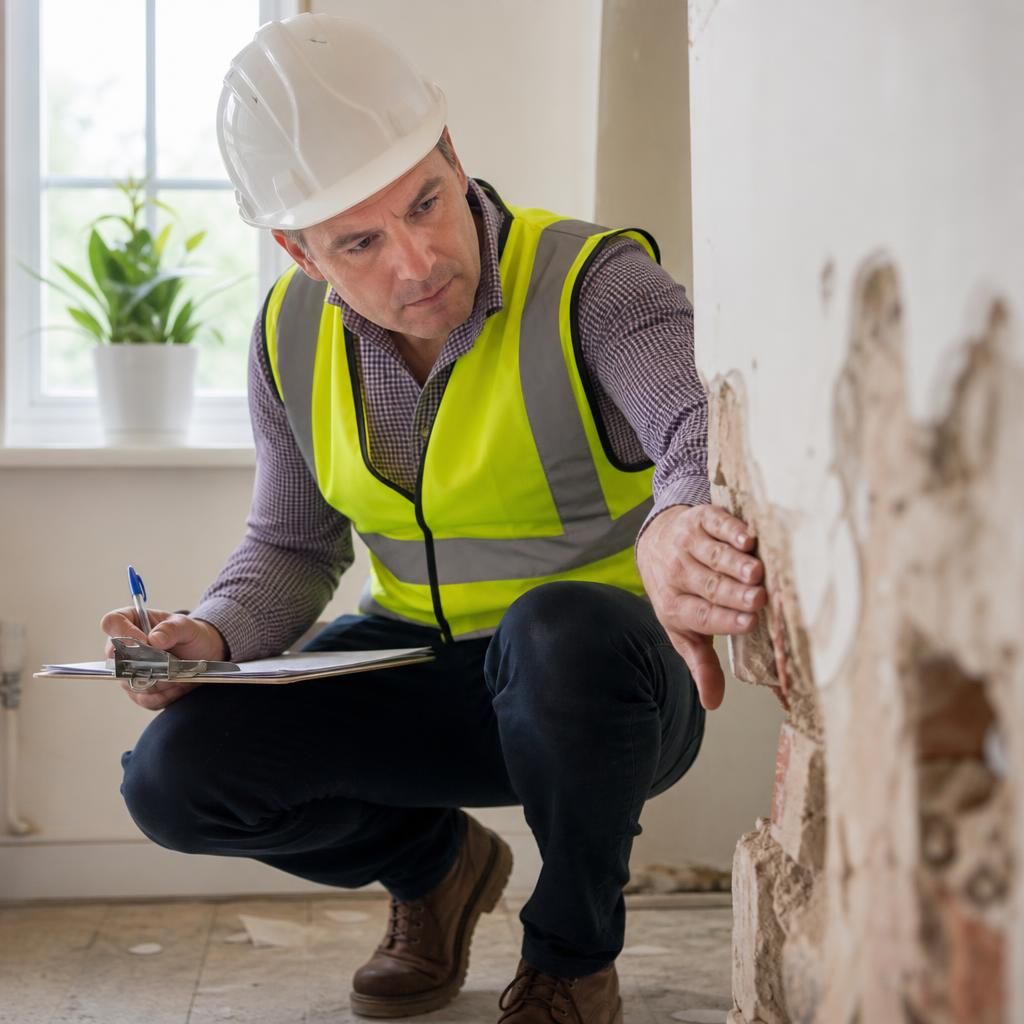
A property valuation and a building survey answer different questions when you are setting a price for a quick house sale. A valuation estimates what the property may be worth in the current market, while a survey examines its condition and highlights defects that could affect the offer. This distinction is particularly important for older, altered or unusual properties where visible presentation may not reveal significant issues.
If a survey identifies problems, do not automatically subtract the full cost of every recommended repair from the price. Separate essential works, safety issues and matters likely to affect resale from improvements that are mainly cosmetic. Obtain estimates where necessary and use the findings to assess whether a proposed cash offer reflects a genuine issue or an excessive allowance for uncertainty.
Discuss Your Quick House Sale Price
Discuss your quick house sale price by providing accurate property details and asking for a written offer that sets out the proposed terms, deductions and completion arrangements. Review it alongside independent advice before deciding whether it reflects your priorities.