

Is my property suitable for a quick sale if it has legal or physical issues?
Yes, a property may still be suitable for a quick sale if it has legal or physical issues, including title complications, disputes, structural defects or significant repair needs. The issue will need to be assessed during the sale process, as its nature and the evidence available can affect the legal checks and transaction terms.
A property with legal or physical issues can still be considered for a quick sale, but suitability depends on whether the issue can be identified, assessed and dealt with during the conveyancing process. Some problems affect the title or the seller’s authority to sell, while others mainly influence the property’s condition, value or the work a buyer may need to undertake.
Legal issues that may need investigation include:
- Unregistered or incomplete title records
- Outstanding mortgages, charges or restrictions
- Boundary disputes or uncertainty about access rights
- Missing planning permissions, building regulation certificates or other compliance documents
- Probate matters where the personal representative has not yet established authority to sell
- Leasehold complications, such as an absent freeholder, a short lease or unresolved service-charge issues
- Occupiers, tenants or family members whose rights must be considered before completion
Not every defect prevents a sale. The key question is whether the legal position can be evidenced and transferred to the buyer. A solicitor or conveyancer will normally review the title, identify restrictions and check whether additional documents, indemnity insurance or third-party consent may be needed. If ownership is disputed, a charge cannot be redeemed, or the seller lacks authority to sell, the transaction may need to be resolved before it can complete.
Physical issues can also be compatible with a quick sale. Examples include structural movement, subsidence concerns, damp, water damage, defective roofs, outdated services, fire damage, asbestos, Japanese knotweed, contamination or a property requiring substantial renovation. A buyer may assess these risks through the available reports, photographs, inspection findings and repair information. The condition can affect the price and the transaction terms, but it does not automatically make the property unsuitable.
It is important to disclose known defects rather than relying on a buyer to discover them later. Relevant information may include previous survey reports, insurance claims, contractor quotations, guarantees, planning correspondence, notices from the local authority and details of past repairs. Accurate disclosure helps the buyer assess the property properly and reduces the risk of renegotiation or a dispute after an offer has been made.
A cash purchase may be more appropriate than a mortgage-funded sale where extensive repairs make the property difficult to finance. However, cash does not remove the need for legal checks, proof of ownership or suitable information about the property. A buyer still needs to understand what is being purchased and whether any risk can be accepted, insured against or resolved.
Before seeking a valuation or formal offer, gather the documents available to you, including the title information, identification, planning and building-regulation records, lease or tenancy documents, probate paperwork and details of secured borrowing. If documents are missing, state this at the outset. Early clarification allows the issue to be assessed as part of the sale instead of emerging unexpectedly during conveyancing.
The most suitable route depends on the nature of the problem. A cosmetic defect may simply be reflected in the valuation, whereas a title restriction, unresolved ownership dispute or serious safety concern may require specialist legal or technical advice. A direct cash buyer can review the circumstances and explain whether the property can be considered, what information is required and which matters must be resolved before completion.
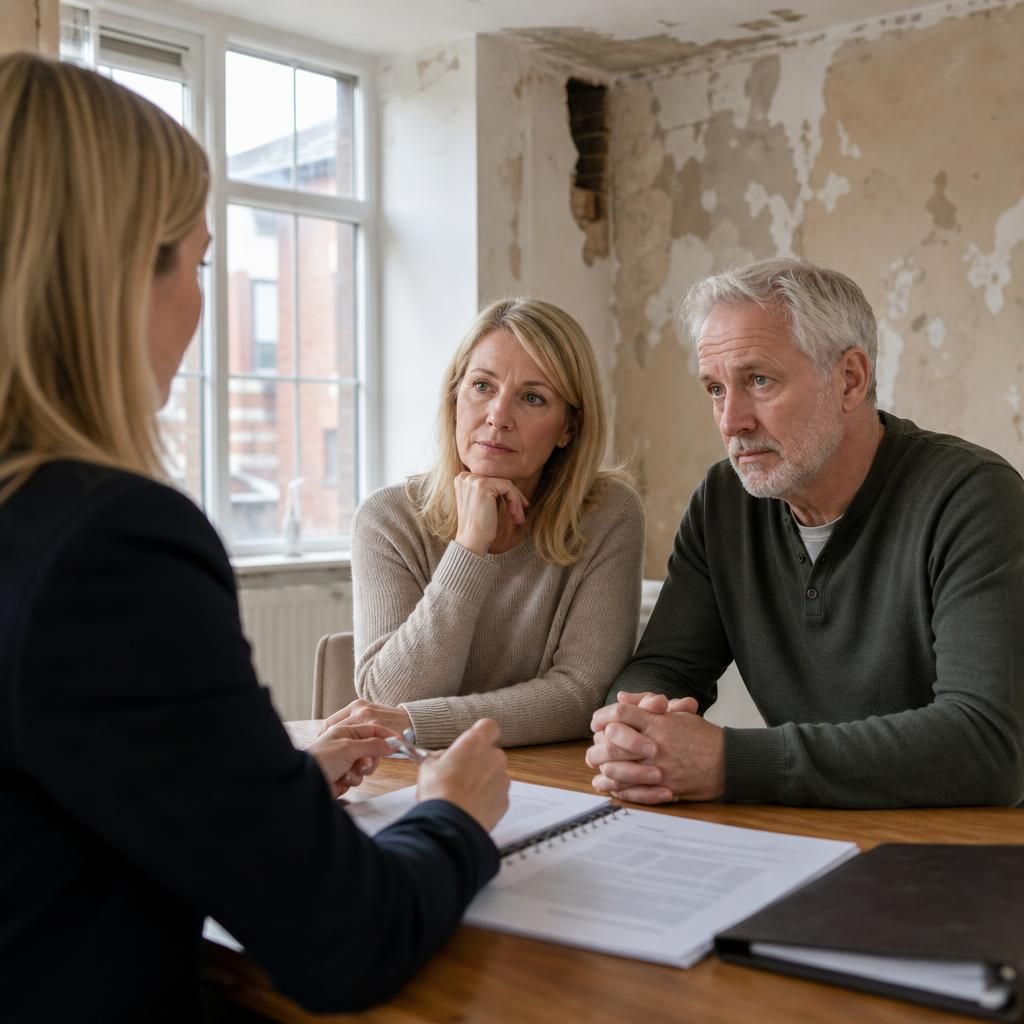
A quick-sale assessment should distinguish between a property that needs a solution and one where the sale cannot currently proceed. An issue is more likely to be manageable when its cause, effect and proposed remedy can be explained clearly. By contrast, uncertainty about ownership, unresolved rights or an immediate safety risk can prevent the transaction from moving forward until the underlying question is answered.
Ask the buyer to confirm how each identified issue will be handled before relying on an offer. This may involve obtaining specialist advice, agreeing a contractual condition, arranging further investigation or setting out which party will take responsibility for outstanding work. Having that position recorded helps prevent misunderstandings and makes it easier to compare a direct cash sale with other selling options.