

What factors can affect the timeline in a fast house sale process?
The timeline for a fast house sale can be affected by the property’s legal status, title documents, mortgage or debt arrangements, survey findings, buyer and seller readiness, and how quickly required information is provided. Issues such as probate, absent owners, leasehold requirements, planning discrepancies or complex property conditions may require additional checks before completion.
A fast house sale timeline is mainly determined by the order in which legal, administrative and practical tasks are completed. Even where the buyer has funds available, completion can take longer if conveyancers are waiting for third-party information, documents require correction, or the seller is not ready to sign and vacate the property.
Conveyancer workload and communication can have a significant effect. Each party normally needs a conveyancer to review the contract, raise enquiries, confirm ownership and arrange completion. Delays may arise when a legal representative has a high volume of cases, takes time to pass on questions, or is waiting for instructions from the buyer or seller. Clear contact details, prompt replies and an agreed method for sending documents can reduce avoidable pauses.
Property searches and third-party responses may also influence the timetable. Local authority, drainage, environmental and other searches depend partly on the relevant authority or search provider. A response may raise a question that needs further investigation, particularly where it reveals a restriction, proposed development or issue affecting the property. The time needed will depend on the nature of the query rather than simply the number of searches requested.
The condition of the title information matters beyond proving who owns the property. Missing deeds, inconsistent names, unclear boundaries, restrictions and unregistered land can require additional evidence or legal work. A conveyancer may need statutory declarations, indemnity arrangements, historic documents or confirmation from another party before the buyer can proceed. Correcting an error at this stage may involve the Land Registry or another organisation, so it should not be treated as an instant administrative change.
Tenure and property-specific administration can create separate dependencies. For example, a freehold property may involve information from a management company, while a leasehold property can require documents or figures from a landlord or managing agent. Flats and managed estates may also involve service charge, insurance or transfer information. These matters are not always controlled by the buyer or seller, making early requests for the relevant information useful.
Outstanding financial arrangements can affect completion where money has to be allocated between the sale proceeds and other parties. The conveyancer may need an up-to-date redemption statement, details of secured lending or confirmation of another financial claim. If the amount changes before completion, revised figures may be required so that the transaction can be completed and the title dealt with correctly.
Buyer funding and final approval remain relevant even when a sale is described as a cash transaction. The buyer may still need to complete source-of-funds checks, obtain internal approval or arrange money transfers. A buyer using a lender will have additional requirements, such as valuation and mortgage conditions. The practical completion date should therefore be based on cleared funds and completed legal work, not solely on an initial offer.
Identity, anti-money-laundering and source-of-funds checks can delay matters if information is incomplete or difficult to verify. Sellers and buyers may be asked for identification, address evidence, company details or an explanation of where funds originated. Changes in the parties involved, such as a transfer into or out of a trust, can lead to further checks. Providing accurate information at the start avoids repeated requests.
Contract negotiation and enquiries can change the expected date. The buyer may ask for clarification about alterations, boundaries, fixtures, guarantees, utilities or rights affecting the property. The seller’s answers may lead to further questions or a request for supporting evidence. Agreement also needs to be reached on what is included in the sale, the completion date and any arrangements for occupation. A transaction cannot normally move to completion until the contract terms are settled.
Vacant possession and moving arrangements are practical factors that should be considered separately from the legal work. If the property is occupied by the seller, tenants or other residents, the required arrangements may affect the completion date. Personal belongings, rubbish, keys and any agreed fixtures should be dealt with before handover. Where a property is sold with occupants or subject to an existing tenancy, the legal and practical position needs to be made clear to the conveyancers.
The existence of a connected sale or purchase can introduce another dependency. A seller who needs the proceeds to complete a purchase may not be able to choose a date independently. Other transactions in a chain can move the proposed completion date, even when the cash buyer’s part of the transaction is ready. A sale without a linked purchase generally involves fewer scheduling dependencies, but the parties still need to agree the contractual date.
Banking and completion-day administration can affect the final stage. The conveyancers must calculate the completion statement, confirm the amount required, receive cleared funds and authorise the transfer. Errors in bank details, late changes to the figures or a transfer that has not cleared can prevent completion on the intended date. Bank details should be verified through a trusted process rather than relying solely on an emailed change of instruction.
To help keep the process on track, a seller can:
- instruct a conveyancer familiar with the proposed transaction and provide full contact details for all relevant parties;
- complete identity and source-of-funds checks promptly;
- locate documents relating to ownership, alterations, guarantees, insurance and property management;
- answer legal enquiries accurately and distinguish confirmed facts from information that still needs checking;
- agree what fixtures, fittings and contents will remain;
- confirm the intended completion date only after checking moving, occupancy and financial arrangements; and
- review the completion statement and payment instructions carefully before funds are transferred.
The most reliable way to assess the likely timeline is to ask the conveyancer which tasks remain outstanding, who is responsible for each one and whether any response is awaited from a third party. This identifies the actual cause of delay instead of relying on a general estimate based only on the property being sold for cash.
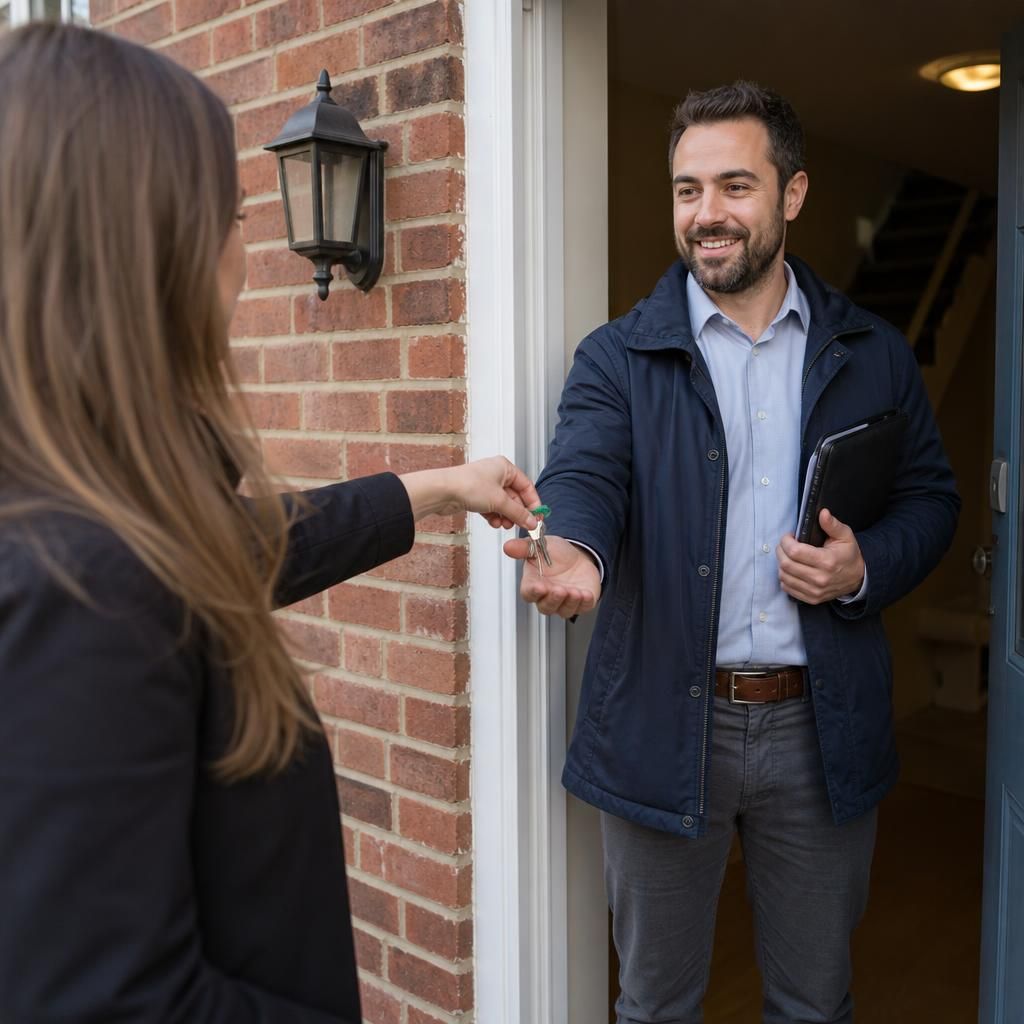
Access to the property can affect the timeline independently of the legal work. If an inspection, survey or other visit is required, progress may pause when keys are unavailable, access arrangements are unclear or occupants need appropriate notice. Agreeing who can provide access, which areas can be entered and when visits are permitted can prevent repeated appointments and avoidable gaps between stages.