

How do cash home buying companies ensure a quick sale process?
Cash home buying companies support a quick sale by assessing the property directly, making a cash offer and reducing reliance on estate agents, marketing and property chains. The process still involves necessary legal checks, searches and conveyancing, but fewer transaction stages can reduce avoidable delays between accepting the offer and completion.
Cash home buying companies support a quicker sale by removing several dependencies found in a conventional transaction, particularly the buyer’s need for mortgage approval and the uncertainty of a long marketing period. A well-managed process combines an early review of the property, clear offer terms, organised legal work and an agreed route to completion. Cash funding can reduce delays, but it does not remove the need for accurate information, a suitable solicitor or proper checks.
The process commonly moves through the following stages:
- Initial property information is gathered. The company will usually ask for details such as the address, tenure, occupancy, condition, alterations and any known restrictions. Providing relevant documents at the outset helps identify matters that could otherwise interrupt the transaction later.
- The offer and its conditions are set out clearly. A written offer should explain the proposed purchase price, any deductions, what is included in the transaction and whether the figure is subject to further information. Clear terms reduce the risk of renegotiation caused by misunderstandings.
- The legal representatives are instructed promptly. Once an offer is accepted, the seller and buyer each need appropriate conveyancers. The seller’s solicitor deals with the contract pack, title information and replies to enquiries, while the buyer’s legal representative reviews the documentation and raises any necessary points.
- Potential title problems are addressed early. Lease restrictions, missing documents, boundary questions, unpaid charges, planning concerns or probate requirements can affect the timetable. Identifying these issues near the start gives the parties an opportunity to obtain evidence or specialist advice before a completion date is selected.
- The buyer’s funding position is simpler. A genuine cash purchase does not normally depend on a mortgage lender’s underwriting decision, mortgage valuation or formal loan offer. This removes a common source of uncertainty, although the buyer may still carry out its own financial, legal and property checks.
- A completion date is coordinated between the parties. The solicitors confirm that the contract is ready, outstanding enquiries have been dealt with and the required funds are available. Agreeing a realistic date, rather than relying on an open-ended timetable, gives everyone a defined target and makes it easier to organise removals, vacant possession or arrangements with occupiers.
Companies that regularly buy property for cash may also use standard internal procedures, dedicated case management and direct communication between the decision-maker and the legal team. These arrangements can reduce handovers and make it easier to identify what is holding up a transaction. They should not be confused with skipping safeguards: identity checks, proof of ownership, anti-money-laundering checks and legally required documentation still apply.
The seller can help maintain momentum by returning forms accurately, supplying identification and title documents quickly, disclosing known defects or disputes, and keeping their solicitor informed of changes in circumstances. Delays often arise when information is incomplete or when a property has tenants, multiple owners, a mortgage to redeem or an unresolved probate issue. A cash buyer may be able to work with these circumstances, but the additional legal requirements still need to be completed.
Before accepting an offer, the seller should check whether it is genuinely unconditional or subject to a survey, legal review, internal approval or a later price discussion. They should also confirm the proposed completion arrangements, the identity of the purchasing entity and the responsibilities of each party. A quick process is valuable only if the terms are understood and the transaction reaches legally binding completion without avoidable surprises.
For a UK sale, the practical advantage of a cash buyer is therefore not that every step disappears. It is that the process can contain fewer finance-related dependencies and can be managed around a clearly defined legal and completion plan. The actual timescale will depend on the property’s title, the seller’s circumstances, the responsiveness of the parties and whether any complications need specialist attention.
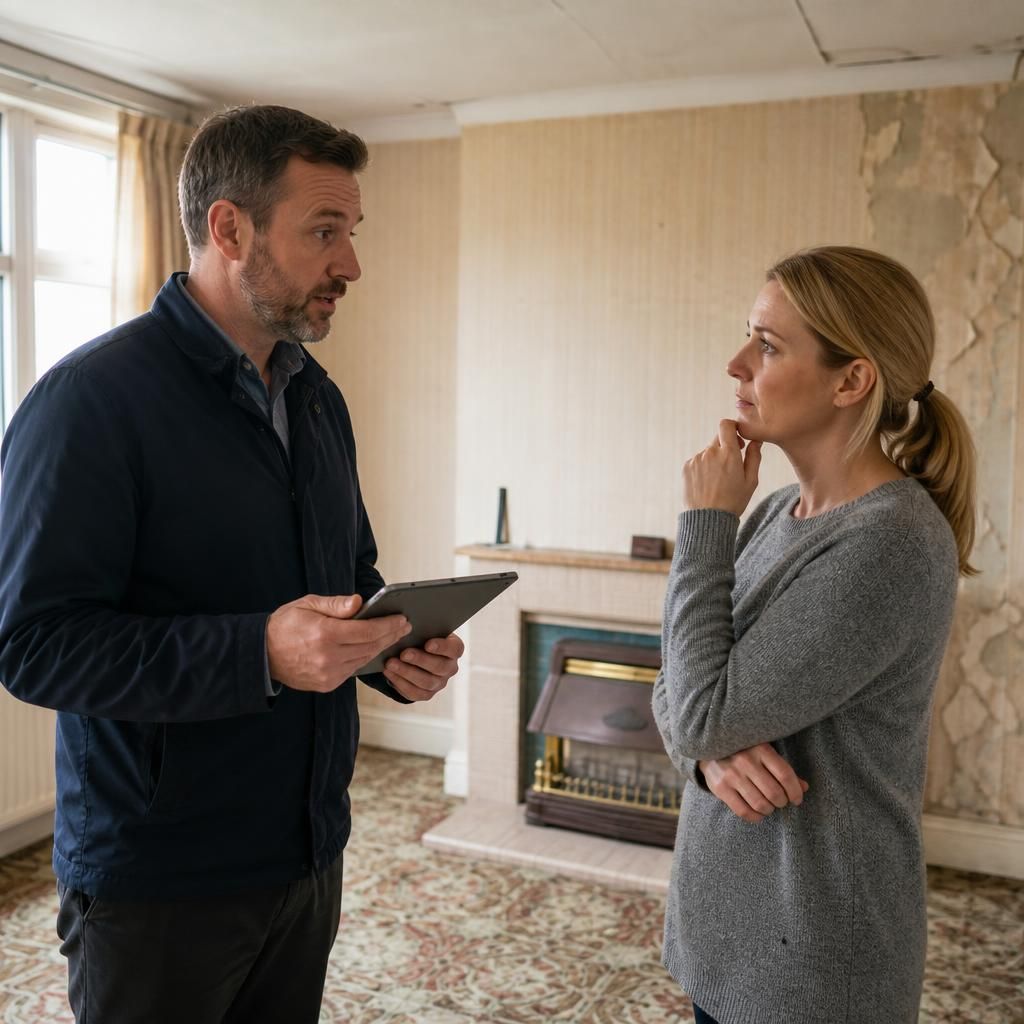
One way cash home buying companies can shorten the process is by assessing the property in its existing condition rather than requiring the seller to prepare it for the open market. This may avoid decorating, repairs, photography, viewings and negotiations with multiple prospective buyers before an offer is made.
That does not mean defects or alterations can be withheld. The buyer still needs accurate information about the property, and serious structural, planning or title issues may require further investigation. However, where the agreed terms reflect the condition and no remedial work is required before purchase, removing those preparation stages can reduce the number of steps between the initial assessment and legal completion.