

What are the potential legal challenges in a quick cash property sale?
Potential legal challenges in a quick cash property sale include unclear title ownership, outstanding mortgages or restrictions, probate and divorce-related claims, missing documents, and disputes over the contract or completion terms. An independent conveyancer should verify the title, explain the legal documents, identify unresolved issues and ensure the sale agreement protects your interests before you commit.
A quick cash property sale can create legal challenges even when the buyer does not need a mortgage. The main risks arise from the sale contract, the seller’s authority to sell, property disclosures, leasehold or tenancy obligations, identity checks, tax considerations and the transfer of money at completion. A cash purchase removes lender approval from the transaction, but it does not remove the need for proper conveyancing.
Contract terms that favour the buyer
A buyer may propose a contract containing conditions, access rights, exclusivity provisions or deadlines that are not immediately obvious from the headline offer. For example, the agreement might allow the buyer to withdraw after inspections, require the seller to pay particular costs, or prevent the seller from considering another offer for a stated period. The legal effect depends on the wording, not on verbal assurances.
Before signing, check whether the offer is conditional, whether the buyer can reduce it later, what happens if either party fails to complete, and whether any deposit or compensation is payable. Do not rely on an informal promise that the agreed figure is fixed. Any amendment should be recorded in writing and reviewed by the seller’s own conveyancer.
Misrepresentation and disclosure of the property’s condition
Sellers must take care when answering enquiries about the property. A statement that is knowingly false, or a failure to disclose a matter where there is a relevant legal duty to do so, can lead to a claim after completion. This may concern previous disputes, notices affecting the property, alterations, guarantees, boundary arrangements, flooding history or problems with access.
There is a difference between selling a property in its present condition and concealing a material issue. A cash buyer may agree to accept repairs or defects, but the agreement should make clear what has been inspected, what is excluded from the sale and whether any warranties or certificates are being provided. Answer conveyancing enquiries accurately and ask for advice if the facts are uncertain.
Planning, building regulations and alterations
Unauthorised extensions, loft conversions, replacement windows, electrical work or changes of use can cause difficulty during conveyancing. The buyer may request planning permissions, building regulation completion certificates, guarantees or suitable indemnity insurance. If documents are unavailable, the parties may need to agree a lawful solution rather than treating the omission as irrelevant.
Do not apply retrospectively for consent or contact an authority simply to resolve a paperwork problem without first taking legal advice. In some circumstances, an application or disclosure can affect the availability of an indemnity policy. The appropriate response depends on the work carried out and the property’s location.
Leasehold and managed-property obligations
Leasehold sales can involve requirements that do not usually apply to freehold homes. The lease may require notice to the landlord, a licence to assign, a deed of covenant or payment of an administration charge. There may also be outstanding service charges, planned major works, reserve-fund contributions or disputes with the managing agent.
These matters can delay completion or leave the seller liable after the sale if they are not dealt with correctly. Obtain the relevant information early, check the lease for transfer requirements and establish who is responsible for charges up to the completion date. A fast transaction does not override the terms of the lease.
Occupiers, tenants and vacant possession
If anyone other than the owner lives at the property, the seller must establish what right they have to remain. A formal tenancy, licence, lodger arrangement or informal family occupation can have different legal consequences. A buyer requesting vacant possession may not be able to obtain it simply because the seller has asked the occupier to leave.
Ending a tenancy incorrectly can result in a claim, and removing belongings or changing locks without proper authority can create further problems. Identify all occupiers at the outset and obtain specialist advice before agreeing a completion date based on vacant possession.
Identity, fraud and authority to act
Conveyancers must verify identity and comply with anti-money-laundering requirements. Delays or refusal to proceed can result if identification documents do not match the legal ownership details, if the source of funds is unclear, or if someone is attempting to act without the necessary authority.
Extra care is needed where a power of attorney, company, trust or representative is involved. The document must give the relevant authority and may need to be registered or independently checked. Protect completion funds by confirming bank details through a trusted, separate channel. Do not act on an unexpected change to payment instructions sent by email alone, as property transactions are a target for payment diversion fraud.
Bankruptcy, insolvency and financial pressure
A seller who is bankrupt, subject to an individual voluntary arrangement, or dealing with serious creditor action may not have unrestricted authority to sell or distribute the proceeds. A transaction at below-market value can also attract scrutiny in some insolvency circumstances. Mortgage arrears or financial pressure do not automatically prevent a sale, but the conveyancer must establish which parties need to consent and how completion funds will be applied.
Be open about relevant financial proceedings at the beginning of the transaction. Concealing them can create delay and may put the validity of the sale or the distribution of the proceeds at risk.
Tax and reporting consequences
A sale can have tax implications depending on the seller’s circumstances, how the property has been used, whether it is an investment or business asset, and whether ownership is shared. The legal conveyancing process is not a substitute for tailored tax advice. Before accepting an offer, consider whether an accountant or tax adviser should review the proposed transaction, particularly where the property is not the seller’s only home or is held through a trust or company.
Completion and release of keys
Completion is the point at which the purchase money is received and the legal transfer takes effect under the contract. Releasing keys or leaving the property before the agreed arrangements are confirmed can create avoidable risk. The contract should state the completion date, what is included in the sale, the condition in which the property must be left and the consequences of late completion.
Keep records of the agreed price, included fixtures and fittings, correspondence, certificates and any negotiated changes. Use a regulated conveyancer acting for you, read the contract before signing and ask for an explanation of any clause that is unclear. These steps cannot eliminate every legal issue, but they make it more likely that problems are identified before the transaction becomes binding.
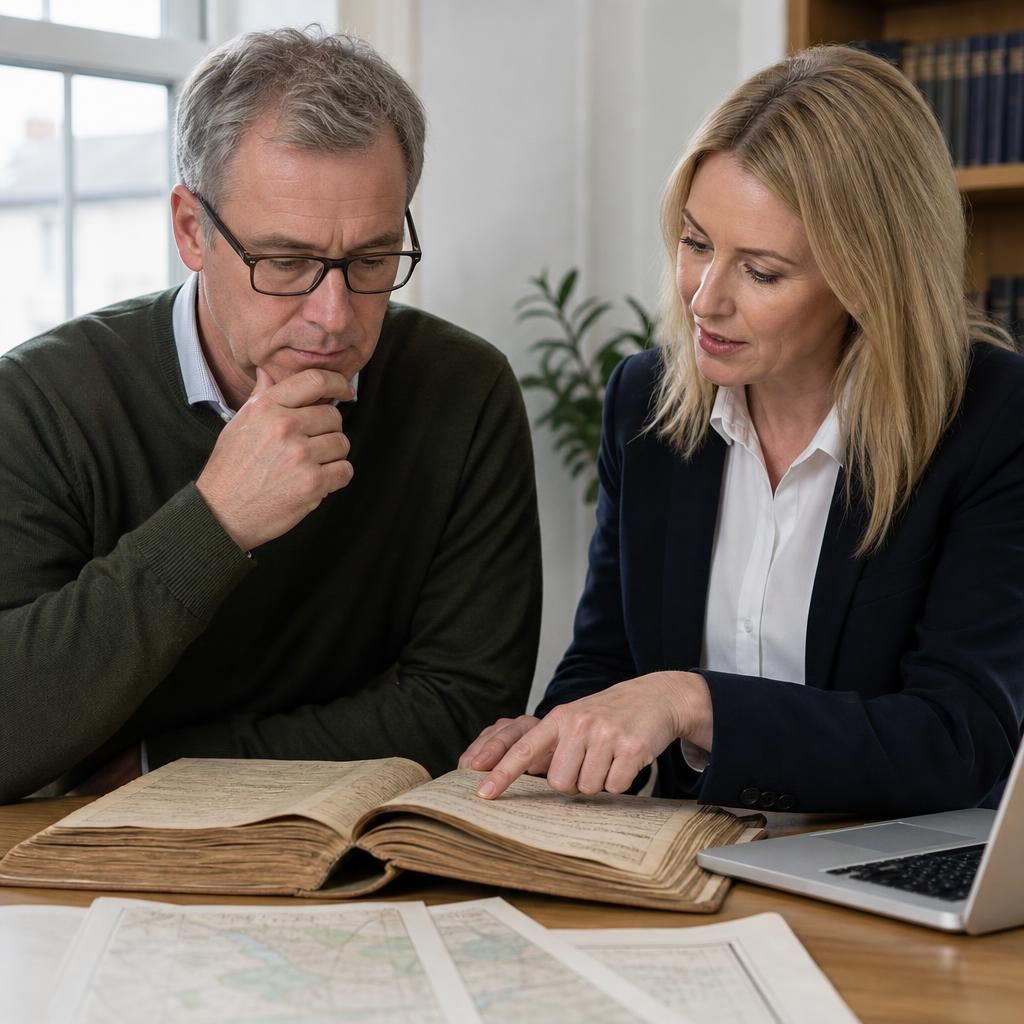
Unregistered land can be a significant legal obstacle in a quick cash property sale because ownership may need to be proved through historic deeds rather than a straightforward registered title. If deeds are missing, inconsistent or difficult to interpret, the buyer’s conveyancer may require further evidence before accepting that the seller can transfer good title.
This issue may arise with older properties, divided plots, extensions of registered land or parcels that have changed hands without registration. The conveyancer may need to reconstruct the chain of ownership, investigate rights benefiting or burdening the land, and consider whether an application for first registration or title insurance is appropriate. These steps should be assessed on the facts of the property rather than assumed to be resolved by the buyer paying cash.
Ask your conveyancer to check the title position at the start of the sale and locate any original deeds, plans or historical transfer documents. If the property is in Scotland or Northern Ireland, the conveyancing process and land-registration rules differ, so obtain advice applicable to that jurisdiction before agreeing contractual terms.
Ask About the Legal Steps in Your Quick Cash Property Sale
Before accepting a quick cash offer, ask an independent conveyancer to review the proposed terms and identify any unresolved legal issues. Once you understand your obligations, you can contact buyhousesfast.co.uk to discuss your property and the information needed to consider a cash sale.