

How can property condition affect the speed of selling in a fast property sale?
Property condition can affect the speed of a fast sale because serious defects, outstanding repairs or legal complications may require further checks and negotiations. Selling to a cash buyer may avoid the need to complete repairs before sale, although the condition will usually be considered when assessing the property and making an offer.
Property condition affects the speed of a fast sale mainly by influencing who can buy the property, what checks are needed and whether the agreed price remains acceptable after inspection. Cosmetic wear may have little effect, whereas structural defects, safety concerns, unclear alterations or serious damage can narrow the buyer pool and create additional stages before exchange and completion.
Not all defects have the same effect. A property that needs redecoration, replacement flooring or general clearance can often be assessed without extensive investigation. These issues may affect the offer but do not necessarily prevent a sale. By contrast, problems such as subsidence, significant damp, roof failure, unsafe electrics, defective plumbing or extensive fire or flood damage may require specialist reports. The time needed to obtain those reports can influence whether a buyer proceeds and whether the transaction needs further negotiation.
- Cosmetic condition: untidy rooms, dated decoration and worn fittings are usually visible and relatively straightforward to factor into an offer.
- Functional defects: problems with heating, plumbing, windows or electrics may require testing to establish their extent and likely cost.
- Structural condition: movement, subsidence, roof problems or major cracking can lead to surveys, insurance questions and more detailed legal enquiries.
- Severe damage: fire, flooding, infestation or contamination may require evidence that the property is safe and suitable for occupation or redevelopment.
Condition can also affect mortgageability. Some lenders will not release funds where a property is considered unsuitable security, for example because it has serious structural damage, lacks essential facilities or requires substantial work before occupation. This can make a conventional buyer harder to find and may introduce a lender’s valuation, conditions or further documentation. A cash buyer is not dependent on mortgage approval, but will still assess the physical and legal risks before confirming the purchase terms.
The property’s use and presentation may create separate issues. An empty property can be easier to inspect, while an occupied property may require access arrangements and clarification about possession. If tenants, licences, planning restrictions or restrictions on use are involved, the buyer may need additional information before deciding how the condition affects value. Properties undergoing renovation can also raise questions about building regulations, planning consent and whether completed work is adequately documented.
An “as-is” sale does not remove the need for accurate information. Sellers should disclose known defects rather than relying on a buyer to discover them later. Concealing a material problem can result in renegotiation, a failed transaction or legal disputes. Providing reports, guarantees, planning documents, building-regulation certificates, insurance claims and details of previous repairs can help the buyer understand the property without repeating investigations unnecessarily.
Before deciding whether to carry out work, compare the likely benefit with its effect on the sale process. Minor improvements may make inspections easier, but substantial work can involve contractors, approvals and uncertainty over the final cost. In a fast sale, a buyer may instead price the required work into the offer and take responsibility for arranging it. This avoids the seller having to complete a project, although the offer will reflect the perceived risk, labour and materials involved.
A practical way to prepare is to:
- List known defects and distinguish confirmed problems from suspected ones.
- Gather guarantees, invoices, survey reports and certificates for previous work.
- Explain any insurance claims, flooding, subsidence, infestations or enforcement notices.
- Ensure the buyer can inspect relevant areas, including lofts, cellars, outbuildings and services where safe.
- Ask how the condition will be assessed and which findings could change the proposed price.
- Check that the sale contract accurately reflects the property and any agreed fixtures or exclusions.
For a property in relatively good condition, the main speed advantage usually comes from having clear information and an uncomplicated inspection. For a property requiring significant work, the fastest suitable route may depend less on appearance and more on whether the buyer is comfortable taking on the associated risk. A cash purchase can be an option where the seller prefers not to undertake major work first, but the condition remains an important part of valuation, due diligence and the final terms.
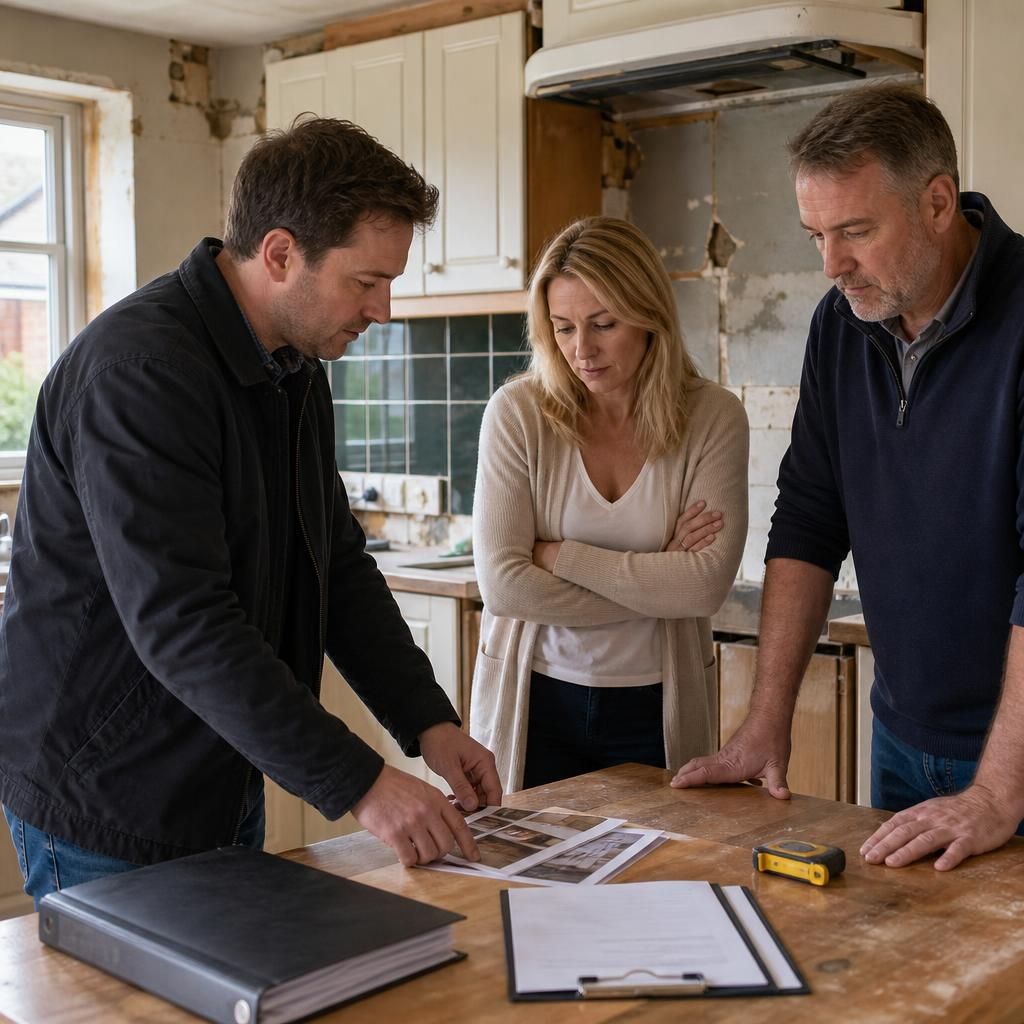
The cost of putting a property into saleable condition is not always reflected pound for pound in its value. A buyer may consider materials, labour, project management, compliance requirements and the risk of unexpected work, rather than relying only on the seller’s estimate. This means completing improvements before a fast sale can add expense without producing an equivalent increase in the offer.
For that reason, sellers should distinguish between work needed for safety or legal compliance and improvements that are mainly cosmetic. Essential defects may need attention or clear supporting evidence, while decorating, upgrading fittings or replacing usable items may be better left for the buyer to assess. Making this distinction can prevent unnecessary work from becoming another source of delay.