

How long does the fast cash sale process typically take from start to finish?
A fast cash sale typically runs from the initial property assessment and offer through legal checks, contract exchange and completion, with the overall timescale depending on the property and circumstances. Straightforward sales may complete sooner, while probate, title issues, mortgage arrangements or other legal complexities can extend the process.
The duration of a fast cash sale is governed mainly by legal readiness, the property title and the circumstances of the seller, rather than by the cash offer alone. A straightforward property with an available owner, clear title and no dependent purchase can move through the process in a relatively short period; missing information, unresolved ownership or lender requirements can make it take considerably longer.
1. Property information and initial assessment
The process begins with basic information about the property, including its address, tenure, occupancy, condition and any known legal issues. The buyer may review this information, arrange an inspection or valuation, and consider whether the property is suitable for a cash purchase. The speed of this stage depends on how complete the information is and whether the property requires further investigation.
An early assessment is not the same as a legally binding sale. The proposed price, intended timescale and any conditions should be recorded clearly so that both parties understand what has been discussed before legal work progresses.
2. Offer and initial checks
Once an offer is made, the seller should check the basis on which it has been calculated and confirm whether it is subject to inspection, title checks or other conditions. A cash buyer will normally need to demonstrate that funds are available, while the seller should provide accurate information about mortgages, leases, planning matters and occupiers.
At this point, the seller can appoint a conveyancer and begin gathering documents. Preparing the title information, property forms, identification and details of any secured borrowing can prevent avoidable pauses later.
3. Conveyancing and searches
Conveyancing is usually the stage that determines the practical timescale. The solicitors review the registered title, confirm who has authority to sell, check boundaries and restrictions, and raise enquiries about the property. Searches may cover matters such as local authority information, drainage and water, environmental risks or other issues relevant to the location and type of property.
A cash purchase avoids the buyer waiting for a mortgage offer, but it does not remove the need for legal due diligence. The buyer may still require satisfactory answers to enquiries and evidence that the property can be transferred without unexpected rights, charges or restrictions.
4. Resolving issues before exchange
Any issue identified during conveyancing must be addressed before contracts are exchanged. Examples include:
- a mortgage or other charge that needs to be redeemed;
- an absent or unclear title document;
- leasehold information, service-charge accounts or a short lease;
- planning, building-regulation or alteration records;
- an unregistered property or a discrepancy in the owner’s name;
- an occupier who must vacate or give consent; and
- probate, trust or power-of-attorney requirements.
Some matters can be resolved by supplying documents or answering questions. Others may require a specialist solicitor, an application to the Land Registry, consent from a third party or additional legal protection. This is why two sales with similar properties can have very different completion dates.
5. Exchange of contracts
Exchange is the point at which the agreed contract becomes legally binding, subject to the terms in that contract. Before exchange, either party may generally withdraw or renegotiate, although the consequences of doing so can depend on the circumstances and any agreement already made.
The contract should state the completion date and identify what is included in the sale. The seller should not assume that an informal target date is fixed until the solicitors confirm exchange and the contractual arrangements.
6. Completion and transfer of funds
On completion, the buyer’s funds are transferred through the solicitors, ownership passes in accordance with the contract and the seller hands over vacant possession if required. Existing mortgage or secured-loan balances are normally paid from the sale proceeds, with the remaining funds sent to the seller once the solicitor has accounted for the transaction.
Completion may follow exchange relatively soon, or the parties may agree a later date to allow time for moving, arranging vacant possession or coordinating another transaction. The agreed date should take account of any mortgage redemption statement, removal arrangements and the practical handover of keys.
What commonly makes a fast sale take longer?
- Probate has not been granted or the correct personal representatives have not been identified.
- There are several owners and one has not provided consent or identification.
- The property is leasehold and management information is incomplete.
- The title contains restrictions, charges, missing documents or inconsistencies.
- Planning or building-control evidence is unavailable for alterations.
- The seller is in arrears or facing repossession and the lender’s redemption figure is not yet confirmed.
- There are tenants, occupiers or belongings that must be dealt with before completion.
- Either party’s solicitor needs further evidence to satisfy identity, source-of-funds or anti-money-laundering checks.
How to keep the timescale under control
Use a conveyancer familiar with transactions involving cash buyers and provide identification and property documents promptly. Tell the solicitor about every known issue at the outset rather than waiting for it to appear in an enquiry. Keep mortgage details, lease information, planning paperwork and probate documents together, and respond to legal questions with complete answers.
It is also sensible to agree in writing what happens if a legal issue is discovered, which items are included, whether the property must be empty on completion and how the completion date will be selected. A realistic timescale can only be confirmed after the legal review has identified what needs to be resolved.
For that reason, the most useful question is not simply how fast the buyer can make an offer, but which outstanding steps remain before exchange and completion. The conveyancers’ assessment of those steps provides the clearest indication of the likely sale duration.
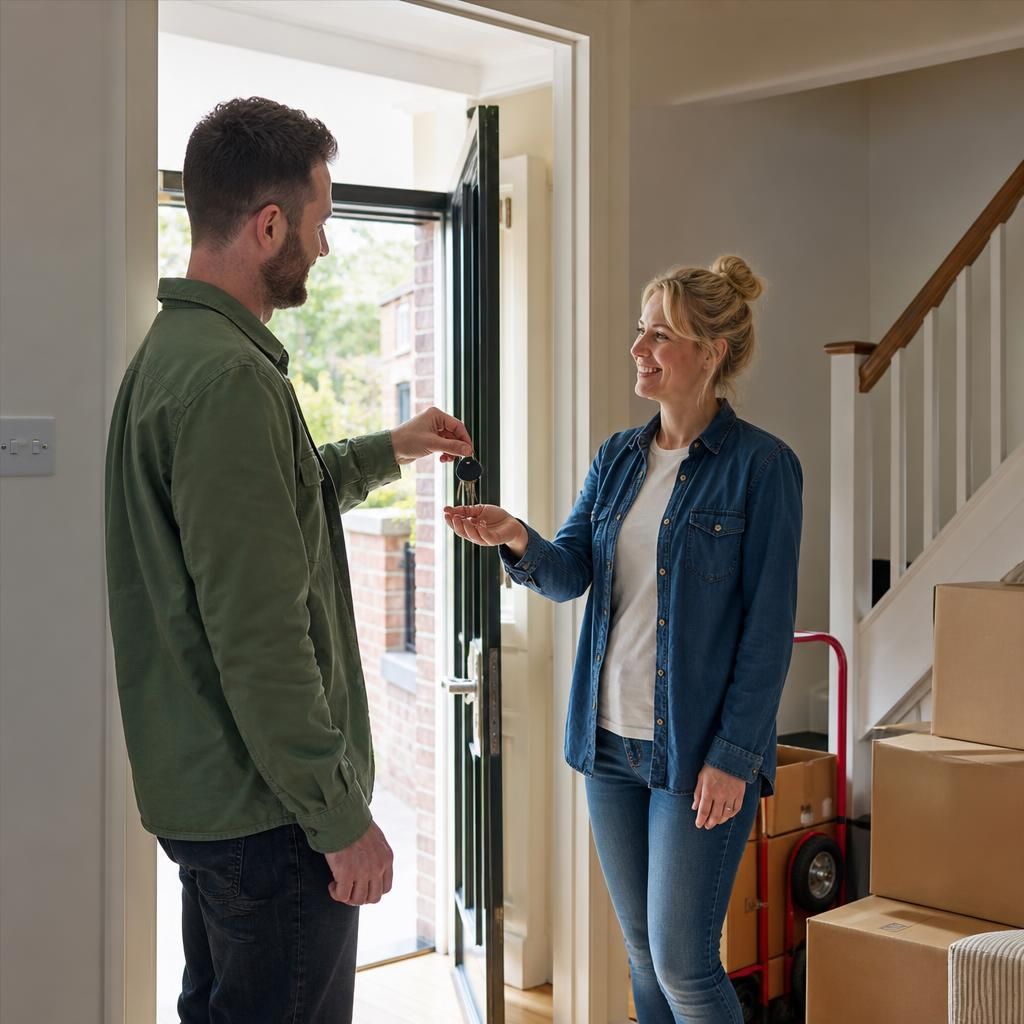
The handover stage is the practical final step in a fast cash sale. Before completion, the seller should confirm what must be removed, which fixtures and fittings are included, and whether the contract requires vacant possession. Resolving these details in advance helps prevent a disagreement from affecting the agreed completion arrangements.
- Arrange removal of personal belongings and unwanted items.
- Keep agreed fixtures, fittings and appliances at the property.
- Gather all keys, fobs, alarm details and relevant access information.
- Take meter readings and record the condition of the property on handover.
- Confirm where completion funds and any mortgage balance will be dealt with by the conveyancer.
These practical tasks do not replace the legal work, but they can prevent avoidable complications once contracts have been exchanged and the completion date is fixed.