

What factors determine the cash offer price for my property?
Your property’s cash offer price is typically based on its location, size, condition, legal status and estimated market value, along with comparable local sales and current buyer demand. The buyer may also account for necessary repairs, transaction costs and the risk involved in completing the purchase.
The cash offer price is determined by what the buyer considers the property to be worth, the likely cost and complexity of completing the purchase, and the return required to make the transaction commercially viable. It is therefore not simply the property’s advertised price or an estate agent’s valuation. A cash buyer usually assesses the property, the title and occupancy arrangements, the likely resale or rental prospects, and the certainty of completing the transaction before making an offer.
Tenure and lease terms can have a significant effect on the figure. A freehold property is assessed differently from a leasehold property, particularly where the lease has a limited remaining term. Ground rent, service charges, planned major works and restrictions on alterations may also affect the buyer’s calculations. For a flat, the buyer may need to review the management arrangements and any information supplied by the freeholder or managing agent.
Planning and development potential may increase or reduce the offer. Existing planning permission, permitted development rights, an extension that could reasonably be added, or the possibility of dividing or converting the property can create additional value. Conversely, planning restrictions, listed-building controls, conservation-area requirements or a lack of the necessary approvals may limit what the buyer can do with it. Potential value is normally treated cautiously unless the relevant permissions and documents are available.
Occupancy and possession are also important. A vacant property that can be handed over without complications is assessed differently from one occupied by tenants, relatives or other residents. The buyer may need to consider tenancy agreements, notice requirements, deposits, rent arrears and whether vacant possession can legally be provided. An existing tenancy is not automatically a disadvantage, but it changes the assumptions used when calculating the offer.
The quality of the available information affects how confidently a buyer can price the purchase. Clear title documents, planning records, guarantees, certificates and details of alterations allow the buyer to verify the facts. Missing paperwork or unexplained discrepancies can lead to a cautious offer, a request for further evidence or a condition that the price is reviewed after legal checks.
Saleability and likely exit strategy influence the buyer’s calculation. A buyer may consider whether the property is likely to appeal to an owner-occupier, landlord or another purchaser, as well as how much work would be needed to prepare it for resale or letting. Features that restrict the potential pool of future buyers, such as unusual construction, access arrangements or restrictive covenants, may reduce the price even where the property is otherwise suitable.
Funding and transaction certainty can affect the final figure. A cash purchase may avoid some mortgage-related uncertainty, but the buyer still has acquisition costs, legal work, surveys and other expenses to account for. If the transaction involves unusual title arrangements, several owners, probate administration or a chain of related sales, the buyer may allow for additional work and a greater possibility of delay. This does not mean every complicated sale receives a lower offer, but complexity is commonly reflected in the buyer’s risk assessment.
The seller’s outstanding mortgage or other secured borrowing normally does not change the property’s underlying value, but it does affect the amount left after completion. Before comparing offers, ask whether the quoted figure is the gross purchase price or the estimated amount payable to you. Possible deductions can include mortgage redemption, secured debts, agreed legal costs or other charges connected with the sale. The exact position should be confirmed in writing rather than inferred from an initial conversation.
A sensible way to assess an offer is to compare the assumptions behind it, not just the headline number. Check:
- what information the buyer has used to prepare the offer;
- whether the figure is subject to a survey, legal review or other condition;
- which costs, if any, would be deducted from the stated price;
- whether the offer depends on vacant possession, planning documents or particular title evidence; and
- how long the offer remains valid and what could cause it to be changed.
An independent valuation or opinions from local property professionals can provide a useful comparison, although these may be based on an open-market sale rather than a direct cash transaction. The most meaningful comparison is the estimated net amount you would receive, adjusted for the costs, uncertainty and obligations associated with each available selling route.
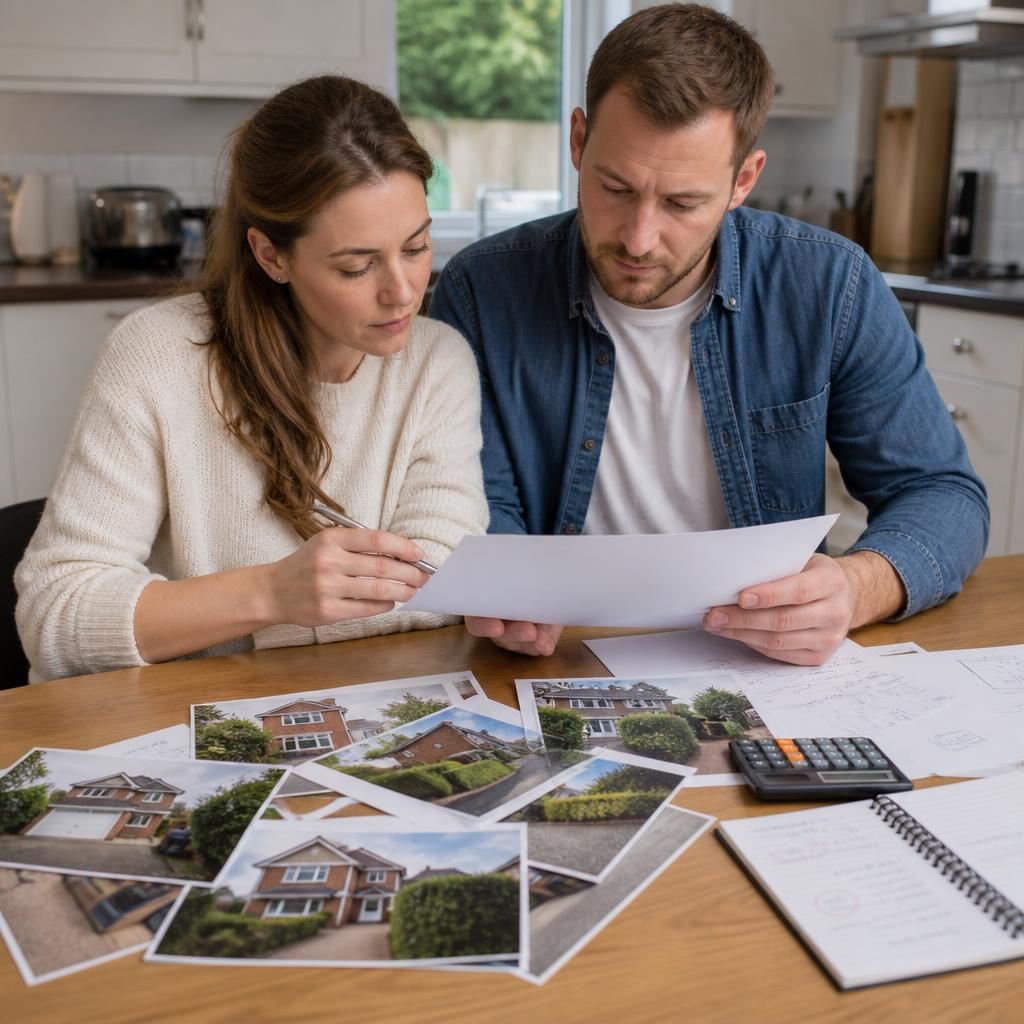
Recent comparable sales are one of the main reference points used to estimate a property’s cash offer price. Buyers generally look for completed sales of similar properties nearby, then adjust the comparison for differences in size, layout, condition, parking, outdoor space and tenure.
Completed sale prices are usually more useful than asking prices because they show what a buyer actually paid. However, the comparison must also reflect market conditions at the time of assessment. A sale several months old, or one involving a substantially renovated property, may provide less reliable guidance than a recent sale of a similar home in a similar condition.
- Compare properties with a similar type, size and tenure.
- Separate renovated homes from properties requiring substantial work.
- Check whether the sale included features such as parking, an extension or development potential.
- Consider whether unusual circumstances may have influenced the recorded sale price.
This evidence helps establish a realistic value range, but a cash offer may sit below an anticipated open-market selling price because the buyer is also allowing for purchase costs, required work and resale risk.