

What are the potential downsides of selling my property as-is?
Selling a property as-is can lead to lower offers, a smaller pool of potential buyers and less scope to negotiate, because the buyer accepts responsibility for arranging repairs and managing unknown defects. You may also need to provide relevant information about the property’s condition, and unresolved issues can affect valuation, mortgage availability and the sale progressing smoothly.
Selling a property as-is can reduce the work required before completion, but it transfers more responsibility and risk to the seller. The main disadvantages are that the condition of the property must be managed carefully, unresolved legal or practical issues can remain the seller’s responsibility, and the transaction may involve costs that are not removed simply because no repairs are carried out.
As-is does not remove the seller’s legal obligations. In England and Wales, a seller must still provide accurate information about matters such as alterations, boundaries, disputes, guarantees, planning permissions and building regulations where relevant. Deliberately hiding a known defect or giving an inaccurate answer can create a risk of a claim for misrepresentation. The phrase “sold as seen” is not a complete protection against misleading statements or failure to disclose information that the seller is required to provide.
There may also be uncertainty about exactly what is included in the sale. Fixtures, fittings, appliances, garden structures and items left in outbuildings should be identified clearly in the contract or property information forms. If the property contains rubbish, unsafe materials or abandoned belongings, the seller should establish whether these must be removed before completion. A vague understanding between the parties can lead to disputes, additional clearance costs or requests for amendments to the contract.
The property may be harder to present and assess accurately. A serious defect can obscure other issues, particularly where there has been water ingress, subsidence, fire damage, infestation or long-term neglect. Buyers and their advisers may commission surveys, specialist inspections or searches to establish the extent of the problem. Those investigations can raise further questions about access, repair methods, insurance and future use, even if the buyer has already accepted the general condition.
Some properties also have practical limitations that affect the sale independently of their physical state. Examples include:
- unclear ownership or missing title documents;
- unrecorded extensions, loft conversions or other alterations;
- boundary disagreements or access rights that have not been documented;
- short, defective or absent leases for leasehold property;
- service charge, ground rent or maintenance issues;
- planning restrictions, enforcement notices or environmental concerns; and
- problems obtaining suitable buildings insurance.
These matters can require a solicitor to obtain documents, arrange indemnity insurance or negotiate additional contractual terms. The seller may have to pay for searches, certificates, document retrieval, clearance, security or specialist advice even when no physical improvement work is undertaken.
An as-is sale can also create financial uncertainty after an offer is accepted. The agreed price may be subject to contract, searches, survey findings and the buyer’s legal review. If a previously unknown issue emerges, the parties may need to decide whether to investigate it, amend the contract or reconsider the transaction. This is not necessarily a problem unique to as-is sales, but the risk can be more significant where the property has limited records or obvious defects.
Tax and ownership circumstances should be considered separately from the property’s condition. A sale may have implications for capital gains tax, inheritance administration, trust arrangements or mortgage redemption, depending on the seller’s circumstances. A property involved in probate, divorce or insolvency may require authority from other people or organisations before it can be sold. Specialist legal or tax advice is appropriate where ownership is complex; the conveyancer handling the sale may not provide personal tax advice.
There can be ongoing costs while the property remains unsold or vacant. These may include mortgage payments, council tax, utilities, insurance, security, storage, garden maintenance and urgent measures to prevent further damage. Not carrying out repairs does not remove the duty to take reasonable steps to prevent a known issue from worsening, particularly where leaking water, exposed wiring or structural instability creates a safety risk.
Before choosing an as-is sale, prepare a realistic record of the property’s condition and gather available paperwork. Ask a conveyancer which disclosures are required, check whether any alterations have the necessary approvals, and identify outstanding finance or ownership restrictions. Compare the net result of an as-is sale with the likely result after essential work, taking account of professional fees, holding costs, risk and the time involved. A specialist cash purchaser may be suitable for some circumstances, but the proposed price and contract should still be reviewed carefully rather than treating “as-is” as a waiver of normal legal checks.
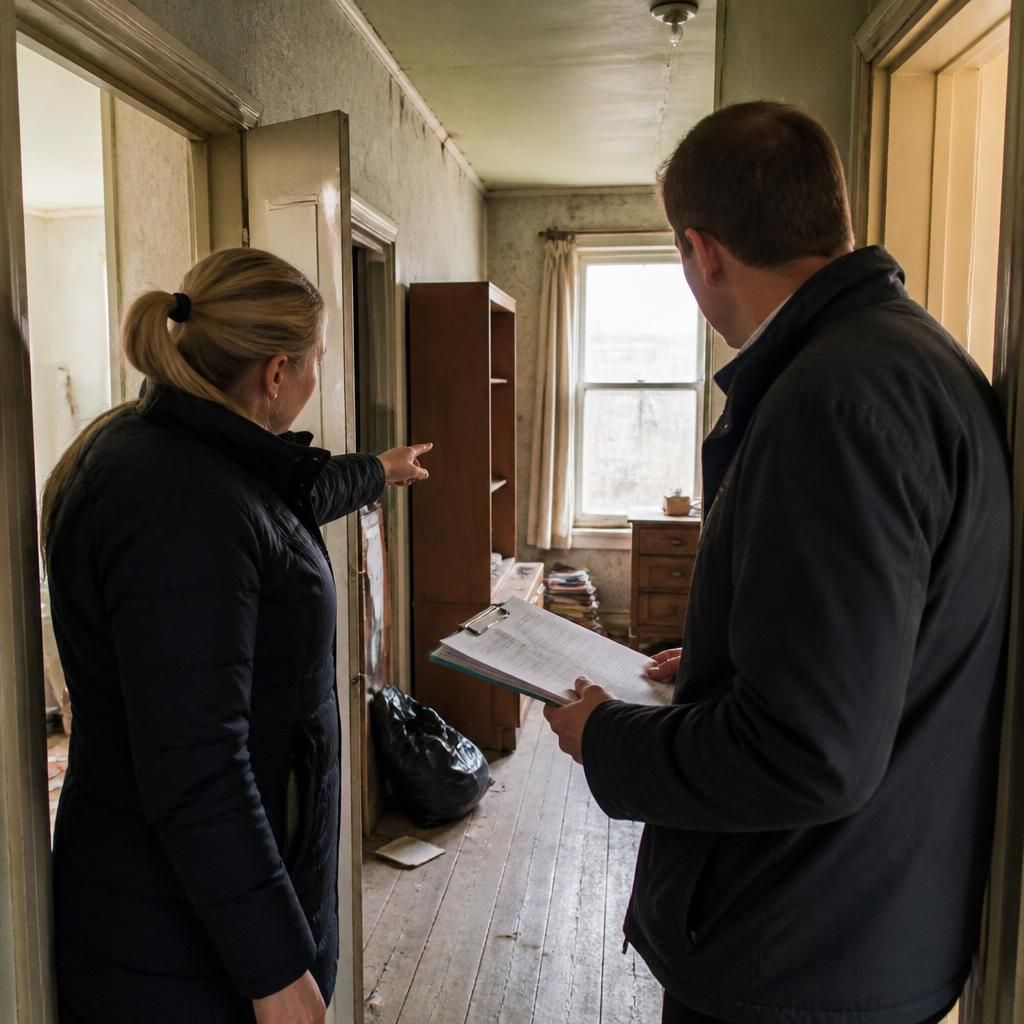
An as-is listing does not remove the need to make the property reasonably accessible for viewings, inspections and valuation. If rooms, loft spaces, outbuildings or access routes cannot be safely reached, buyers may be unable to assess the property properly and may withdraw or make their offer conditional on further investigation. Before marketing, identify any restricted areas, explain access limitations accurately and agree safe arrangements for inspections. This helps prevent misunderstandings about what the buyer has actually had an opportunity to examine.