

How does selling my house 'as-is' affect the valuation and offers I receive?
Selling your house ‘as-is’ usually reduces its valuation because buyers account for the repairs, defects and legal or practical risks they may inherit. Offers are therefore based on the property’s condition and the buyer’s estimated costs and risk, rather than the price a comparable property in good condition might achieve.
Selling a property ‘as-is’ means presenting it in its current condition and making clear that you are not undertaking agreed improvements before completion. Its valuation is then based on the property’s existing features, condition, evidence of defects, location and likely demand, rather than on the price that might be achieved after renovation.
It is important to distinguish between a formal valuation and an offer. A surveyor may provide an opinion of market value for a particular purpose, while a buyer makes an offer based on what the property is worth to them after considering purchase costs, finance, works, resale prospects and risk. Two buyers can therefore assess the same house differently and submit noticeably different offers.
How the as-is condition affects the assessment
A buyer will usually look beyond cosmetic presentation and assess whether the property is immediately usable, legally acceptable and financially practical to acquire. The following issues can influence the figure:
- Structural condition: subsidence, movement, roof failure, serious damp, defective foundations or unsafe alterations can result in a substantial adjustment where specialist investigation or major works may be needed.
- Services and systems: outdated or defective electrics, plumbing, heating, drainage, windows and insulation may reduce an offer because their condition can affect safety, compliance and future running costs.
- Repairability: a buyer may treat a dated kitchen or worn decoration differently from a leaking roof or unresolved structural problem. The likely cost, duration and uncertainty of the work all matter.
- Legal and title matters: missing approvals, unclear rights of way, restrictive covenants, lease issues, boundary disputes or planning concerns can affect both value and whether a buyer can obtain funding.
- Occupancy and possession: tenants, unauthorised occupiers or an unclear possession position may affect the buyer’s costs and the time needed to take control of the property.
- Presentation and access: clutter, hoarding, overgrown grounds or restricted access may not permanently reduce the underlying land value, but they can make inspection, clearance and works more difficult.
Why offers may differ from comparable sales
Comparable properties are useful only when their condition, tenure, size, location and legal position are genuinely similar. A renovated house nearby may establish an indication of the area’s ceiling price, but it is not necessarily an appropriate direct comparison for a property requiring extensive work. A buyer may estimate the post-renovation value and deduct the anticipated works, professional fees, finance, transaction costs and a margin for unforeseen problems.
This calculation is not always a simple pound-for-pound deduction. Renovation work can uncover additional defects, planning permission may be required, materials and labour may cost more than expected, and the project may take longer than planned. Buyers commonly allow for these uncertainties when deciding what they can justify offering. A cash buyer may also assess the property differently from a mortgage-funded buyer because the transaction does not depend on a lender’s valuation, although the property and title will still need appropriate checks.
Condition does not determine the whole value
The property’s location, plot, accommodation, potential for alteration, tenure, local demand and comparable evidence remain relevant. A house in poor condition may still attract interest if it has development potential, a desirable layout, a large garden or a location where suitable properties are limited. Conversely, a property in reasonable decorative condition may receive reduced offers if it has a short lease, access problems or unresolved legal matters.
Valuation also depends on the intended buyer. An owner-occupier may value usable space and a straightforward move, whereas a developer or investor may focus on resale value, rental income or the feasibility of a project. A company that buys residential property for cash may consider properties with physical or legal complications, but its offer will still reflect its assessment of the risks and costs involved.
How to make offers easier to compare
Ask each prospective buyer to explain the basis of the offer and identify whether it is subject to inspection, title review, finance or other conditions. Establish whether the quoted amount is the proposed purchase price or whether deductions may later be made for repairs, clearance, legal issues or other matters. Also check whether the buyer expects you to carry out specific works before completion.
Provide accurate information about known defects rather than relying on a buyer to discover them later. Relevant documents may include guarantees, planning permissions, building regulations certificates, warranties, tenancy information and correspondence about disputes or remedial works. A clear description of the property allows buyers to price the risks more consistently and reduces the chance of renegotiation when further information emerges.
Before accepting an offer, compare the net amount you are likely to receive with the practical obligations attached to it. Consider any required repairs, clearance, professional fees, legal costs, outstanding mortgage or other secured debt, and the conditions of the proposed purchase. The highest headline offer is not automatically the strongest if it depends on extensive work or includes conditions that could alter the final amount.
An as-is sale can therefore produce a lower offer than a fully repaired and well-presented sale, but the difference should be assessed against the work, uncertainty and transaction requirements you would otherwise take on. Independent legal advice and, where appropriate, an independent valuation can help you understand whether an offer reflects the property’s evidence-based value and the terms of the proposed sale.
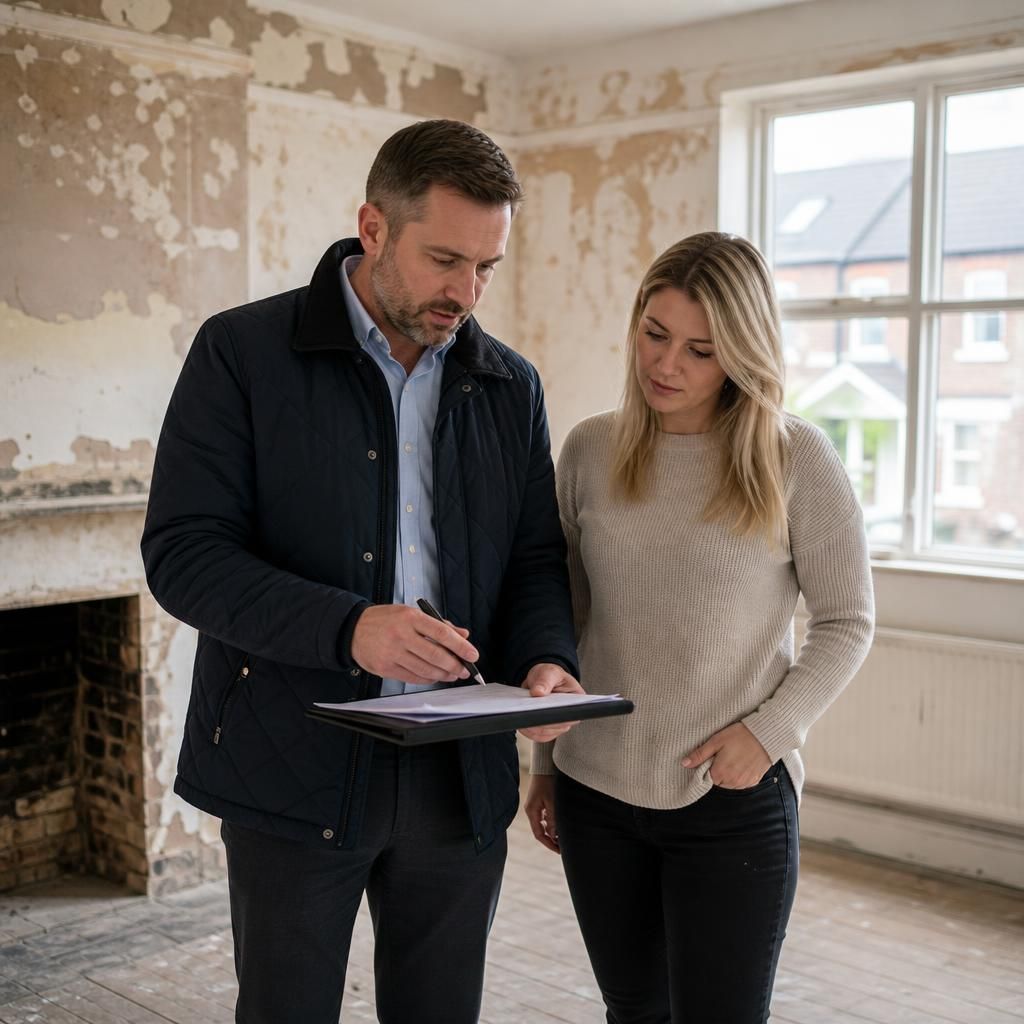
“As-is” describes the agreed condition of the property; it does not mean that known defects can be concealed or that the buyer must proceed without making enquiries. Information that could materially affect the property’s value or the buyer’s decision should be disclosed accurately, including known damage, disputes, notices, previous repairs and restrictions on use.
Clear disclosure can influence the offer in two ways. It may reduce the figure where the issue creates a genuine cost or risk, but it also gives the buyer better information to price the property confidently. By contrast, an undisclosed problem discovered during inspection or conveyancing may lead to further questions, revised terms or withdrawal from the proposed purchase.
Discuss Your As-Is Property Sale
If you are considering an as-is sale, discuss your property and circumstances with a member of the buyhousesfast.co.uk team to understand whether a cash purchase may be suitable. Share accurate details so any proposed offer can be considered alongside the property’s condition and legal position.