

What factors should I consider before choosing to sell my house as-is for quick cash?
Before selling your house as-is for quick cash, consider its condition, likely market value, the offer received, any fees or deductions, your legal and mortgage position, and whether the speed and convenience justify accepting less than a traditional sale might achieve. Compare the buyer’s terms carefully, confirm what is included in the agreement, and obtain independent legal or property advice if the transaction involves probate, debt, leasehold issues or other complications.
Before choosing an as-is cash sale, assess whether the arrangement fits your wider circumstances, not just the condition of the property. The key questions are whether you need certainty of completion, whether anyone else has an interest in the home, what obligations will remain after completion, and whether the proposed transaction gives you enough protection and flexibility.
Consider your reason for selling. A fast sale may be suitable where you are managing an empty property, relocating, dealing with an inherited home or trying to simplify a complicated ownership situation. However, the best option may differ if you have time to market the property, need to remain in it temporarily, or are relying on the sale proceeds to purchase another home. Set out your priorities before engaging with buyers so that you can distinguish an essential requirement from a term that is merely convenient.
Check whether everyone with an interest agrees. The registered owner is not always the only person whose position matters. Co-owners, personal representatives, beneficiaries, spouses, tenants and people with rights of occupation may all need to be considered. If the property forms part of an estate, establish who has authority to sell it. If ownership is disputed or a divorce is ongoing, obtain appropriate legal guidance before signing an agreement.
Examine the proposed contract carefully. An offer is only one part of the decision. Check:
- who is buying the property and whether the buyer intends to complete personally or assign the contract;
- whether the agreement is conditional on further checks, finance, valuation or another sale;
- what happens if the buyer withdraws or seeks to renegotiate;
- when the contract becomes binding and whether there is any right to cancel;
- which fixtures, fittings, appliances and contents are included;
- who is responsible for insurance, maintenance and risk between exchange and completion; and
- whether the completion date works with your removal, accommodation and financial arrangements.
A solicitor or licensed conveyancer should explain clauses you do not understand before you commit. Avoid signing documents under pressure or relying solely on verbal assurances that are not reflected in the written contract.
Assess completion certainty rather than focusing only on the headline amount. Ask what checks the buyer will carry out, whether the funds are available, and what evidence will be provided before exchange. A buyer who has not established their ability to proceed may create disruption even if the initial proposal appears attractive. Your conveyancer can help verify the source and transfer of funds and identify conditions that could delay or prevent completion.
Review the property’s ownership and occupancy position. Freehold and leasehold properties can involve different requirements. For a leasehold home, examine the remaining lease term, service-charge position, planned major works, restrictions on transfer and any requirement for landlord or managing-agent information. Tell the buyer about tenants, licences, informal occupants, boundary arrangements, rights of way, alterations and disputes. Selling as-is does not remove the need to provide accurate information or deal with title issues.
Be clear about defects and disclosure. You generally do not have to improve a property before an as-is sale, but you should not conceal known problems or give misleading answers. Keep records of guarantees, planning permissions, building-regulation approvals, repair reports and insurance claims where relevant. If you are uncertain about a defect or an alteration, ask your conveyancer how it should be disclosed. Openness reduces the risk of later disagreement or a failed transaction.
Calculate the practical amount you will retain. Work from the proposed completion statement rather than the offer alone. Account for any secured borrowing, redemption charges, arrears, conveyancing costs, removal expenses, storage, accommodation and costs associated with resolving title or leasehold matters. Also ask a tax adviser whether the sale could affect capital gains tax, inheritance-tax administration or other personal obligations. The tax position depends on the property and your circumstances, so it should not be assumed from the buyer’s description of the transaction.
Consider what happens after completion. Decide where you will live, where possessions will go and how important documents will be stored. If another person occupies the property, make a lawful plan for handing over vacant possession where required. Check arrangements for utilities, council tax, insurance, keys and meter readings. These practical details can affect the date on which you can complete and the costs you incur after agreeing the sale.
Compare the as-is route with realistic alternatives. You could obtain advice on limited repairs, a conventional market sale, an auction or a different completion structure. The relevant comparison is not between an as-is offer and an ideal asking price; it is between the likely net result, time, uncertainty and work involved in each option. A small amount of preparation may improve marketability, while a property with serious defects or complex ownership may be more suited to a buyer willing to handle those issues.
Before proceeding, obtain the written proposal, ask questions about every condition, verify the buyer’s identity and instruct an independent conveyancer. Keep copies of correspondence and do not treat a non-binding indication as a completed sale. A careful review of the contract, ownership position, ongoing liabilities and post-sale arrangements will show whether accepting an as-is cash offer is appropriate for your circumstances.
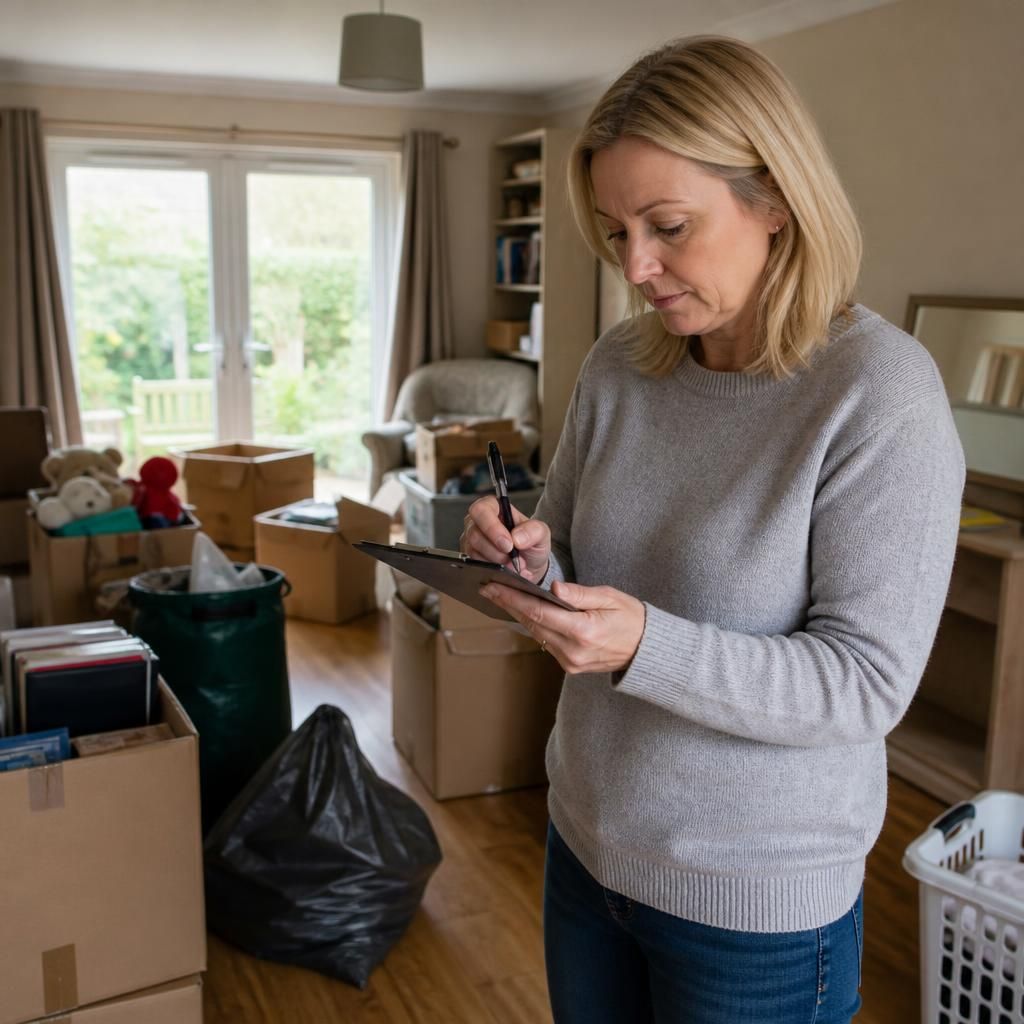
“As-is” describes the condition in which the property is sold; it does not automatically define what is included in the transaction. Before accepting an offer, clarify whether items such as garden structures, carpets, appliances, furniture, rubbish or stored belongings will remain. Removing or disposing of them may create additional cost, while leaving them behind may affect the agreed terms. Record the arrangement in writing so there is no disagreement about the property’s contents at handover.