

What is the process for selling my house as-is for quick cash?
Selling your house as-is for quick cash usually involves sharing property details, receiving an assessment and cash offer, completing legal checks through conveyancers, and agreeing a completion date. You can accept an offer without carrying out repairs or marketing through an estate agent, subject to satisfactory legal checks and the terms agreed.
Selling a house as-is for quick cash is primarily a legal and commercial process rather than a refurbishment project. The property is considered in its existing condition, while the buyer checks that the ownership, paperwork and agreed terms allow the transaction to proceed.
- Prepare the relevant information. Gather details such as the property address, tenure, approximate condition, occupancy, known defects and any outstanding mortgage or secured borrowing. Be clear about matters that could affect the transaction, including subsidence, damp, Japanese knotweed, disputes, planning issues, unauthorised alterations or restrictions on the title.
- Explain your circumstances and requirements. The buyer will need to understand whether the property is occupied, whether vacant possession is required and whether there are other owners or interested parties. Where the property is inherited, in joint names or connected with divorce or financial proceedings, the person selling must have the necessary authority to agree the transaction.
- Review the offer carefully. A cash offer should be assessed against its conditions, proposed deductions, included fixtures and fittings, responsibility for outstanding charges and the intended completion arrangements. Compare the net amount you expect to receive, not just the headline figure. Check whether the offer depends on a survey, valuation, inspection, title issue or another condition.
- Instruct a conveyancer. Your conveyancer represents your legal interests and deals with the contract, title, identity checks, property information and enquiries. They will also confirm how any mortgage, equity charge or other secured debt is to be paid from the sale proceeds. If there is a lease, additional information may be needed from the freeholder or managing agent.
- Complete the property forms accurately. An as-is sale does not remove the need to answer questions honestly. The TA6 property information form may cover boundaries, disputes, alterations, notices, services and known problems. Relevant planning permissions, building regulations approvals, guarantees, certificates and leasehold documents should be supplied where available. A missing document may lead to further enquiries or affect the terms.
- Allow the legal checks to be resolved. The buyer’s conveyancer may raise enquiries about the title, access, rights of way, restrictions, planning history, utilities and the condition-related information you have provided. A buyer may also arrange an inspection. Selling as-is usually means you are not agreeing to carry out repairs, but it does not prevent the buyer from asking questions or changing their position if significant undisclosed information emerges.
- Agree the contract and completion arrangements. The contract sets out the price, property, fixtures and fittings, vacant-possession obligations, deposit provisions and completion date. Read the contract and any special conditions before signing. The agreed date should take account of mortgage redemption, probate or other authority requirements, removals, tenants and any linked transaction.
- Exchange contracts. The transaction becomes legally binding when both sides have signed and contracts have been exchanged by their conveyancers. Before exchange, either party may generally withdraw or seek revised terms, subject to the circumstances and any agreement already made. Do not treat an accepted offer as final until your conveyancer confirms exchange.
- Complete the sale. On completion, the purchase money is transferred, ownership changes hands and the keys are released in accordance with the contract. Your conveyancer normally uses the proceeds to repay any mortgage or secured borrowing, settles agreed charges and sends the remaining balance to you. Keep copies of the completion statement and transaction documents.
The main practical difference from a conventional sale is that the buyer is accepting the property’s present condition instead of requiring you to prepare it for marketing or negotiate repairs as part of a wider chain. That does not guarantee that every issue will be ignored: legal title, ownership, disclosure and contract terms still matter. Before accepting, ask for the offer and its conditions in writing, confirm what is included, establish whether any costs or deductions apply, and have the paperwork reviewed by an independent conveyancer.
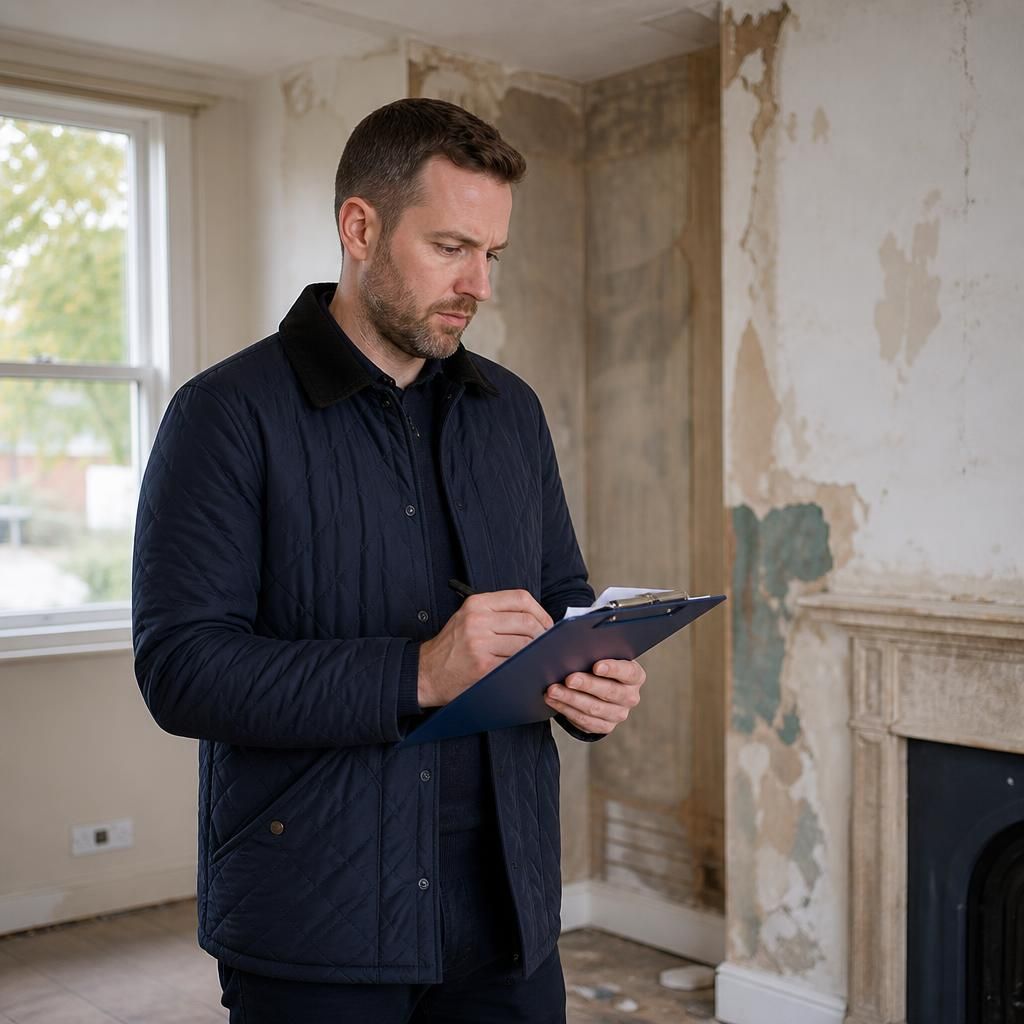
After exchange but before completion, the sale is legally binding while the property remains your responsibility under the contract. Keep it secure, avoid removing fixtures or fittings that are included in the agreement, and do not release keys or allow possession before the agreed completion arrangements. Check the contract for any requirements about insurance, access and the property’s condition during this period, particularly if the house is vacant. Your conveyancer can confirm what you must do before the purchase money is received.