

How can I prepare my property for a quick cash sale?
Prepare your property for a quick cash sale by gathering essential information, presenting the home clearly and addressing only repairs that are likely to affect its assessment. Keep paperwork accessible, remove unnecessary clutter, record known defects honestly and ensure the property can be inspected safely.
Preparing a property for a quick cash sale means making the transaction straightforward to assess, legally authorised and practically capable of progressing. The most useful preparation is not extensive cosmetic work; it is identifying anything that could delay a decision, restrict the sale or prevent the buyer from obtaining clear information about the property.
Confirm who has authority to sell. Check that the person communicating with the buyer is entitled to agree a sale. This is particularly important where the property is jointly owned, held by a company, involved in probate or affected by divorce proceedings. A personal representative may need to provide evidence of their authority, while joint owners may both need to approve the transaction. If there is a dispute about ownership or consent, obtain legal advice before accepting an offer.
Check the property’s legal position. Establish whether there are restrictions, charges or other matters recorded against the title. Examples may include an existing mortgage, a restriction requiring a third party’s consent, a right of way, a boundary issue or an unresolved transfer. These matters do not necessarily prevent a sale, but identifying them early gives the conveyancer an opportunity to explain what is required.
If the property is leasehold, identify the remaining lease term and locate the relevant lease information. Service charges, ground rent, planned major works, management-company requirements and notices affecting the flat can all be relevant to the buyer’s assessment. For a rented property, clarify the tenancy position, deposit arrangements and any notices already served. The buyer will need to understand whether the property will be vacant or occupied on completion.
Understand the financial position. Request an up-to-date mortgage redemption statement if borrowing is secured against the property. Compare the outstanding balance and any early repayment charge with the likely sale proceeds, taking account of other secured debts or restrictions. If the property is in mortgage arrears or subject to repossession action, speak to the lender and an independent adviser as early as possible. A sale may require specific coordination between the buyer, conveyancer and lender.
Also identify any sums that could need settling from the proceeds, such as unpaid service charges, council tax, ground rent or legal liabilities. Do not assume that an apparent cash sale removes these obligations. The conveyancing process will still need to establish what is owed and how it will be dealt with.
Make the property’s status clear. Prepare a concise record of facts that may affect the assessment, including whether the property is occupied, empty, tenanted, under renovation or subject to an insurance claim. Note any planning applications, building work, alterations or changes of use that may require supporting documents. If an extension, loft conversion or structural alteration was carried out, identify whether building-regulation approval, planning permission, guarantees or certificates exist.
Where documents are unavailable, say so rather than trying to reconstruct or overlook the history. Missing approvals or guarantees can often be investigated, but concealment can create greater difficulty during legal checks. A buyer should also be told about known disputes involving neighbours, boundaries, access, drainage or shared areas.
Decide what will remain in the property. Make a written note of fixtures, fittings and appliances that are included, excluded or subject to separate agreement. This can cover fitted kitchens, bathroom fixtures, built-in appliances, light fittings, sheds and other items attached to the property. Remove personal possessions and valuables that are not part of the sale, while keeping items that may be needed to operate the home, such as keys, remote controls and alarm details.
Plan access and vacant possession. Agree how the property can be viewed, inspected and measured without creating uncertainty for occupants or neighbours. If tenants, lodgers or family members live there, explain the proposed sale and establish what permissions or notice requirements apply. If vacant possession is expected, set out a realistic plan for removing belongings and handing over all keys. A property that cannot be accessed or cleared as agreed may create avoidable complications even when the buyer is ready to proceed.
Use repairs selectively. Before spending money, separate essential safety or security work from improvements that are mainly cosmetic. Repairing a dangerous fault, securing an opening or stopping an active leak may be more relevant than upgrading finishes. Obtain advice where a defect could involve structure, gas, electricity, asbestos or water ingress. Keep invoices, guarantees and certificates for work completed, and do not begin major alterations simply to influence an informal cash assessment without understanding whether the cost is likely to be recovered.
Prepare for questions about risk. A cash buyer may want to understand why the property is being sold, whether any urgent issue affects it and what timescale is realistic. Prepare a factual explanation of unusual circumstances without making claims about matters you have not verified. If there has been subsidence, flooding, Japanese knotweed, fire damage or an insurance claim, provide the available history and relevant reports. Specialist issues are easier to assess when they are disclosed at the outset.
Finally, decide what you need from the transaction before agreeing terms. Consider the acceptable sale price, preferred completion arrangements, whether you need time to relocate and whether any conditions must be included in the contract. Take independent legal or financial advice where the sale involves probate, separation, arrears, negative equity or complicated ownership. Once authority, title matters, occupancy and practical arrangements are understood, the property is better prepared for a cash buyer to assess without avoidable uncertainty.
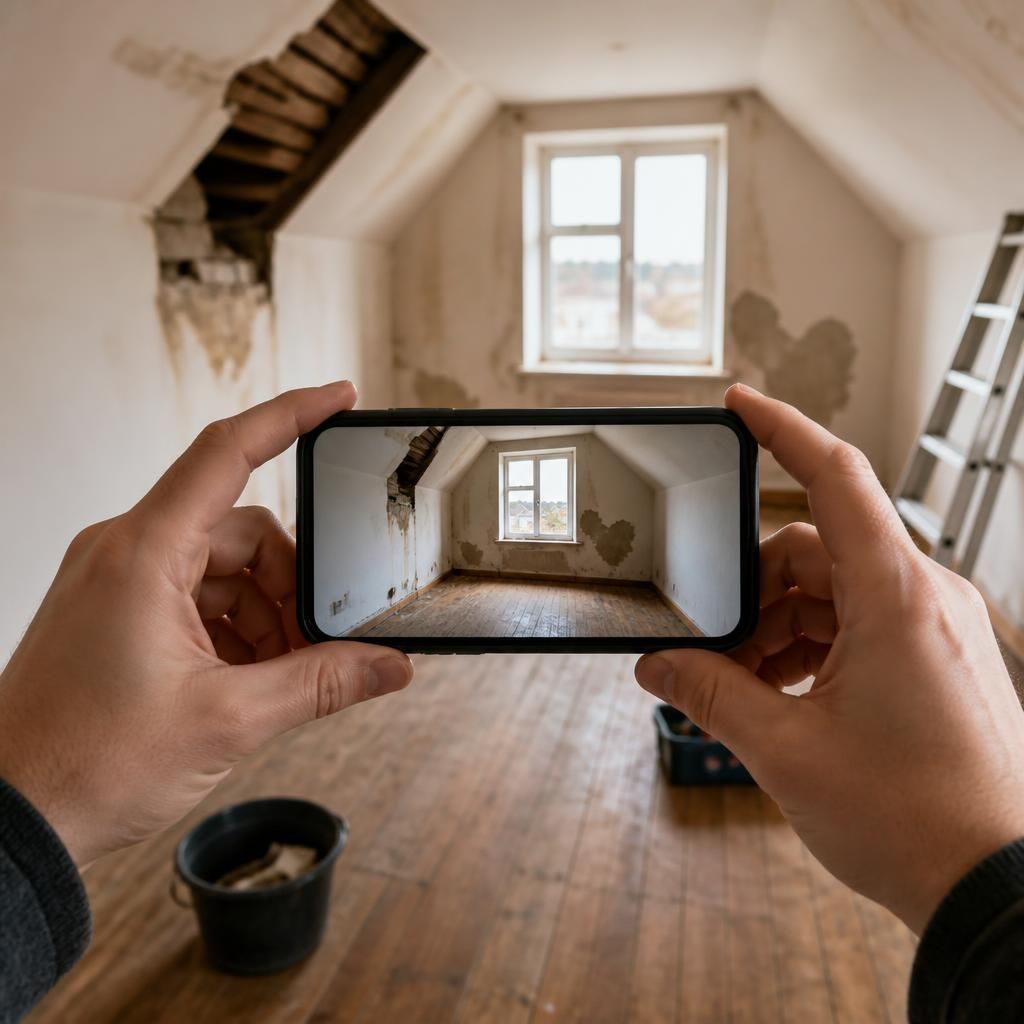
Preparing clear photographs of the property can help a cash buyer form an accurate initial view before arranging a detailed inspection. Take well-lit images of each room, the exterior, gardens, outbuildings and any visible defects. Include wider views rather than showing only recently improved areas, and make sure the images reflect the property’s current condition.
Keep supporting evidence with the images, such as photographs of damp, cracks, roof damage or unfinished work alongside any reports, invoices or guarantees you hold. Label files by room or feature and note when the images were taken. This creates a consistent record, reduces uncertainty during assessment and helps prevent disagreements if the property’s condition changes before completion.