

What factors affect the valuation of a flat when selling for cash as-is?
A flat’s cash as-is valuation is mainly affected by its location, size, layout, condition, lease length and the terms of its lease. Local demand, comparable flat sales, service charges, ground rent and any legal or building issues can also influence the offer.
A flat’s cash as-is valuation reflects the price a buyer believes the property can achieve after accounting for risk, resale prospects, funding requirements and the work needed to complete the purchase. In addition to the flat’s physical attributes and lease information, the valuation can be affected by ownership structure, occupancy, block management, planned expenditure and the quality of the evidence supplied by the seller.
Tenure and ownership structure
Whether the flat is leasehold, share of freehold or subject to another ownership arrangement can affect how straightforward it is to assess and resell. A share of freehold may be viewed positively, but its value still depends on how the freehold is managed and whether all owners cooperate with required decisions. Any unusual title arrangement, restrictions on transfer or missing ownership documents can increase legal work and may lead to a more cautious offer.
Occupancy and vacant possession
A flat that is empty and available with vacant possession is generally easier to assess than one occupied by tenants or other residents. If the property is let, the tenancy agreement, rent position, deposit records and the tenant’s rights may affect both value and the timing of resale. A buyer will also consider whether the proposed sale complies with the tenancy terms and whether vacant possession can legally be provided.
Management of the building
The standard of block management can influence a flat’s desirability and the risks attached to ownership. Relevant information includes the managing agent’s records, accounts, insurance arrangements, maintenance history and communication of works to residents. Poorly organised management, unresolved disputes between leaseholders and the freeholder, or incomplete records can make a buyer allow for additional risk even where the individual flat appears suitable.
Reserve funds and future expenditure
Service-charge information is only part of the assessment. A buyer may also examine whether the building has adequate reserves for expected maintenance and whether substantial expenditure is likely to be requested from leaseholders. A flat with a well-managed reserve fund may be easier to value than one where future contributions are uncertain. The important evidence can include recent accounts, budgets, consultation notices and details of any planned works.
Alterations and documentation
Extensions, removed walls, altered kitchens, replacement windows and changes to plumbing or electrics can affect value when they are not properly documented. A buyer may need evidence of planning consent, building-regulation approval, freeholder consent or completion certificates, depending on the work. If approvals are missing, the cost of obtaining retrospective evidence or correcting the issue may be reflected in the cash offer.
Energy efficiency and running costs
The flat’s energy performance and the practical cost of heating it can influence its appeal to future buyers or tenants. An energy performance certificate, where required, provides part of the relevant information. Outdated systems, high communal energy costs or restrictions affecting improvements may reduce the price a buyer is prepared to pay, particularly where those matters could limit future marketability.
Mortgageability and resale risk
Although a cash buyer does not need mortgage approval for the purchase, the property’s future mortgageability can still influence its valuation. Unusual construction, short or complicated legal arrangements, unresolved building concerns, insurance difficulties or restrictive lease provisions may reduce the pool of future buyers. A property that can be resold to both cash purchasers and mortgage-funded buyers may carry less resale risk than one with limited financing options.
Transaction costs and the buyer’s required margin
A cash as-is offer is not simply an estimate of the flat’s best possible asking price. The buyer may account for legal work, surveys, taxes, insurance, finance used during the holding period, clearance, remedial work and the risk that the eventual resale price differs from expectations. The greater the uncertainty around these costs, the more likely they are to influence the initial valuation.
Accuracy and completeness of the information
Valuations are more reliable when the seller supplies consistent information about ownership, occupancy, alterations, management charges and the building’s records. Missing paperwork does not necessarily make a sale impossible, but it can result in further enquiries, a revised offer or a valuation based on conservative assumptions. Providing accurate documents allows the buyer to distinguish confirmed costs from risks that have only been assumed.
For a meaningful comparison between offers, sellers should check whether each figure is based on the same assumptions. Important points include whether the offer is subject to inspection, which costs the buyer expects the seller to pay, whether the price can change after legal enquiries and how any known expenditure has been treated. A higher headline figure may not represent better value if it carries wider deductions or greater uncertainty.
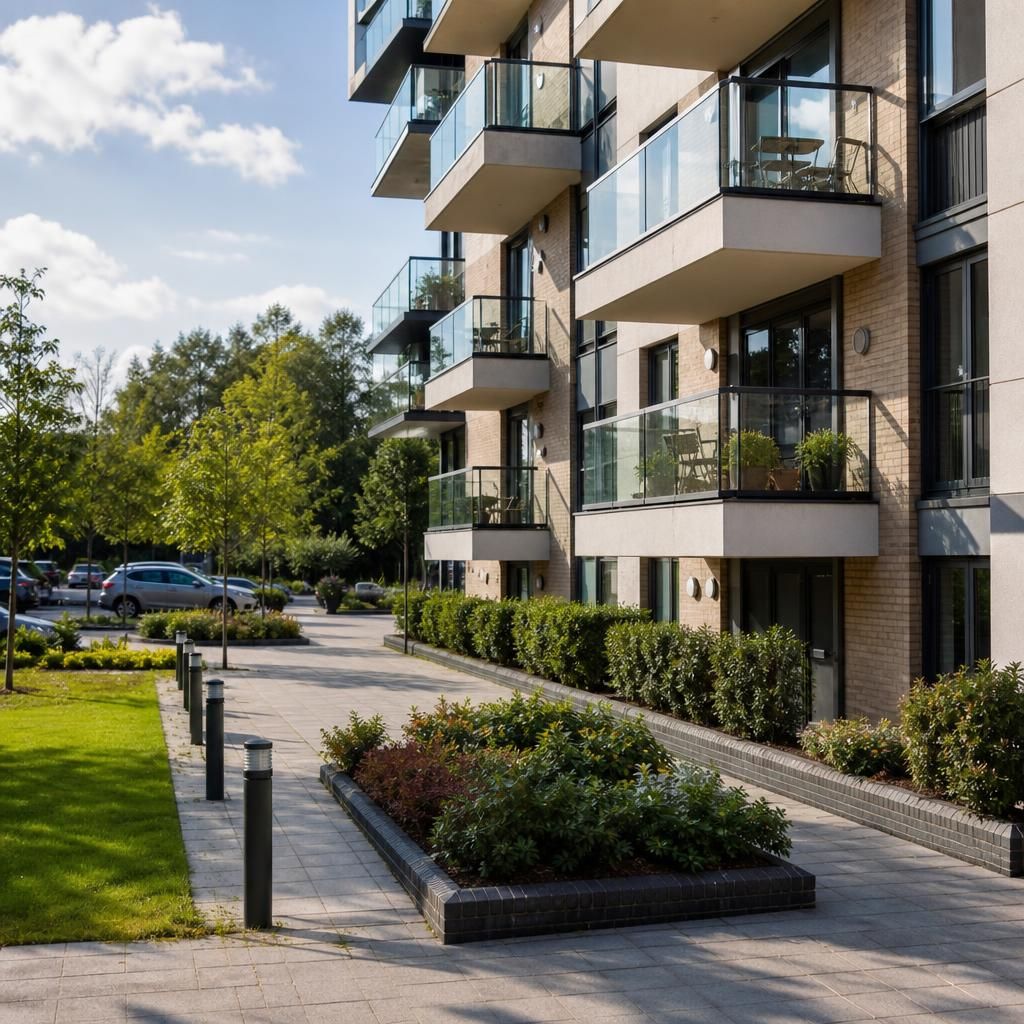
Flat-specific features such as natural light, outlook, floor level, lift access, balcony space, parking and storage can affect an as-is cash valuation. These details influence the flat’s appeal to future buyers or tenants, particularly where access is limited, rooms face a noisy road or the building lacks useful amenities.
Provide accurate information about allocated parking, storage rights, balconies, communal facilities and any access restrictions. A buyer may adjust the offer if these features are unavailable, require repair or are not clearly included in the title or lease.